PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2184738

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2184738
Hazardous Waste Logistics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the hazardous waste logistics market size was valued at USD 14.46 billion in 2025 and is estimated to grow from USD 15.45 billion in 2026 to reach USD 21.09 billion by 2031, at a CAGR of 6.42% during the forecast period (2026-2031).
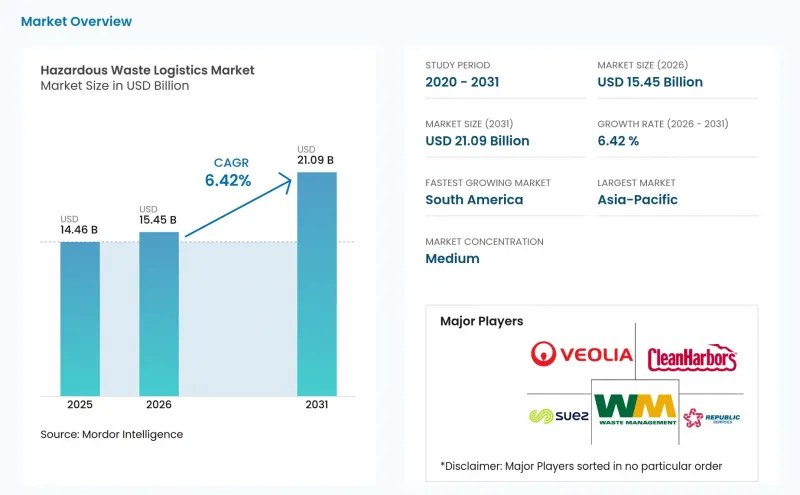
The hazardous waste logistics market is expanding as regulators bring more waste streams into formal tracking and treatment systems. This report is Segmented by Service (Transportation, Warehousing, Value Added Services), by Waste Type (Chemical, E-Waste, Industrial Process, Radioactive, Biomedical, Pharmaceutical, Others), by Industry (Chemicals/Oil and Gas, Batteries/EV, Pharma/Healthcare, and More), and by Geography (North America, South America, Europe, Asia-Pacific, MEA). The Market Forecasts are Provided in Terms of Value (USD).
Global Hazardous Waste Logistics Market Trends and Insights
Industrial and Pharmaceutical Waste Generation Growth
Industrial output and the formalization of pharmaceutical waste management support recurring demand throughout the hazardous waste logistics market. The World Health Organization states that 15% of healthcare waste is hazardous, including infectious, toxic, carcinogenic, flammable, and radioactive material. High-income countries generated as much as 0.5 kg of hazardous waste per hospital bed each day. Michigan adopted EPA Subpart P pharmaceutical waste requirements in May 2025, strengthening controls over chemotherapy agents, controlled substances, and returned drug stock. Pharmaceutical providers need chemistry-qualified personnel, controlled-substance permissions, and electronic tracking, which makes this work more specialized than standard transport. PHMSA oversees more than 1 million daily hazardous-material shipments under Title 49 CFR, which supports a broad compliance-driven service base.
Tightening Hazardous Waste Classification and Shipment Controls
The hazardous waste logistics market is gaining volume as classification rules widen the material covered by permitted handling. Beginning January 2025, Basel Convention controls applied Prior Informed Consent procedures to international shipments coded A1181 and Y49. These procedures covered hazardous and non-hazardous e-waste, creating new consent and documentation work for cross-border electronic scrap shipments. EPA launched the Hazardous Waste Information Platform in September 2025, with geospatial search, real-time visualization, and improved access to compliance data. Domestic exporters also began submitting export manifests electronically in December 2025. These changes create work for certified operators while making it harder for less-capitalized carriers to compete on documented routes.
Cross-Jurisdiction Classification and Permit Complexity
Cross-border and multi-state requirements limit network efficiency and increase compliance costs. The Basel Convention requires notification, written consent, physical movement, and disposal confirmation for each regulated shipment. National definitions of hazardous waste differ across 190 Parties, and exporters are directed to confirm requirements with authorities in destination and transit countries. EPA's January 2025 capacity assessment reported annual commercial landfill receipt limits of 600,000 tons in Alabama and 425,000 tons in New York. These limits can force rerouting and extend haul distances across the hazardous waste logistics market. The hazardous waste logistics market must also operate across RCRA rules and state-authorized programs that can differ from federal standards.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Battery, E-Waste, and Critical-Mineral Recycling Logistics
- Digital Manifesting, GPS Tracking, and Audit-Ready Chain of Custody
- Qualified Driver, Chemist, and Dangerous-Goods Specialist Shortages
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Transportation held 51.20% of the hazardous waste logistics market share in 2025. Road, rail, air, and sea networks link waste generators with RCRA-permitted treatment, storage, and disposal facilities. Road transport supports time-sensitive and small-batch industrial and pharmaceutical shipments. Rail serves large-volume bulk chemical generators because it can move higher payloads efficiently. Warehousing and storage services command higher unit pricing because they require RCRA Part B permissions. These facilities need secondary containment, temperature control, and separation of incompatible chemicals.
Value-added services are projected to expand at an 8.05% CAGR through 2031. Waste profiling, laboratory analysis, reporting, and electronic manifest preparation are becoming central vendor-selection criteria. Michigan's adoption of pharmaceutical waste rules in May 2025 increased documentation work within these services. Electronic export manifest requirements that began in December 2025 also strengthened the need for compliance support. The hazardous waste logistics industry is rewarding providers that combine software, certified chemistry expertise, and permit management. These capabilities help providers earn more on multi-stream contracts than single-mode carriers in the hazardous waste logistics market.
Complete Report Scope:
- By Service
- Transportation
- Road
- Rail
- Air
- Sea and Inland Waterway
- Warehousing and Storage
- Value Added Services
- Transportation
- By Waste Type
- Chemical Waste
- Industrial Process Waste
- E-waste
- Radioactive and Nuclear-Related Waste
- Biomedical and Clinical Waste
- Pharmaceutical and Hazardous Drug Waste
- Other Waste Types
- By Waste-Generating Industry
- Agriculture and Fertilizers
- Batteries and Electric Vehicles
- Chemicals, Petrochemicals, Oil & Gas
- Construction, Infrastructure, and Remediation
- Hi-Tech Industry
- Energy and Utilities
- Government and Defense
- Pharmaceuticals, Healthcare & Laboratories
- Manufacturing and Automotive
- Mining and Metals
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Peru
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Nordics (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Southeast Asia (ASEAN)
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Qatar
- South Africa
- Nigeria
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific held 31.15% of the hazardous waste logistics market share in 2025. China's industrial waste output and its concentration of semiconductor, battery, and petrochemical production underpin regional logistics demand. Co-processing programs direct hazardous residues to permitted cement kilns, supporting collection and transport while reducing tipping fees. These programs do not address PFAS, battery, or pharmaceutical materials that require conventional treatment. India expanded formal electronics dismantling and logistics infrastructure in 2025 through its Battery Waste Management Rules. Japan and South Korea support premium services linked to electronics and automotive manufacturing in the hazardous waste logistics market.
North America is the second-largest geography, supported by RCRA, PHMSA regulations, and the e-Manifest platform. The platform processed 11.6 million manifests between 2018 and September 2024. Canada and Mexico support cross-border waste flows under bilateral arrangements with the United States. Europe operates under the EU Waste Framework Directive and the Basel Convention regime. The amended directive entered into force in October 2025, shaping documentation expectations for the hazardous waste logistics market. Germany, France, and the United Kingdom generate substantial industrial waste volumes, while the Nordic countries sustain premium compliance services.
South America is forecast to grow at a 7.96% CAGR through 2031. Brazil's producer-responsibility requirements for batteries and electronics underpin regional demand in the hazardous waste logistics market. Chile and Peru generate mining-related process chemical and tailings waste that is increasingly subject to environmental enforcement. Argentina adds hazardous volumes through petrochemical and agribusiness activity. Saudi Arabia, the United Arab Emirates, and Qatar support hydrocarbon-related logistics under high-enforcement regulatory settings. South Africa and Nigeria remain early-stage formalization locations where certified operators serve a premium niche alongside wider informal waste systems.
- Veolia Environnement S.A.
- Clean Harbors, Inc.
- Waste Management, Inc.
- SUEZ S.A.
- Republic Services, Inc.
- REMONDIS SE & Co. KG
- GFL Environmental Inc.
- Cleanaway Waste Management Limited
- Biffa plc
- Covanta Holding Corporation
- Seche Environnement SA
- Grupo Tradebe Medioambiente SL
- Daiseki Co., Ltd.
- Beijing Capital Eco-Environment Protection Group Co., Ltd.
- Triumvirate Environmental, Inc.
- EnviroServ Waste Management (Pty) Ltd
- Perma-Fix Environmental Services, Inc.
- Sharps Compliance, Inc.
- Valicor Environmental Services
- Sims Lifecycle Services
- Arcwood Environmental, LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Tightening Hazardous Waste Classification and Shipment Controls
- 4.2.2 Industrial and Pharmaceutical Waste Generation Growth
- 4.2.3 Expansion of Battery, E-Waste, and Critical-Mineral Recycling Logistics
- 4.2.4 Digital Manifesting, GPS Tracking, and Audit-Ready Chain of Custody
- 4.2.5 Outsourcing of Generator Compliance and Multi-Site Waste Programs
- 4.2.6 Under-Reported Driver: PFAS and Emerging-Contaminant Characterization Creating Premium Logistics Demand
- 4.3 Market Restraints
- 4.3.1 Cross-Jurisdiction Classification and Permit Complexity
- 4.3.2 High Insurance, Liability, and Specialized Fleet Costs
- 4.3.3 Qualified Driver, Chemist, and Dangerous-Goods Specialist Shortages
- 4.3.4 Under-Reported Restraint: Treatment-Facility Acceptance Risk for Battery, PFAS, and Unknown Chemical Loads
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact of Geopolitical Events on the Market
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Service
- 5.1.1 Transportation
- 5.1.1.1 Road
- 5.1.1.2 Rail
- 5.1.1.3 Air
- 5.1.1.4 Sea and Inland Waterway
- 5.1.2 Warehousing and Storage
- 5.1.3 Value Added Services
- 5.1.1 Transportation
- 5.2 By Waste Type
- 5.2.1 Chemical Waste
- 5.2.2 Industrial Process Waste
- 5.2.3 E-waste
- 5.2.4 Radioactive and Nuclear-Related Waste
- 5.2.5 Biomedical and Clinical Waste
- 5.2.6 Pharmaceutical and Hazardous Drug Waste
- 5.2.7 Other Waste Types
- 5.3 By Waste-Generating Industry
- 5.3.1 Agriculture and Fertilizers
- 5.3.2 Batteries and Electric Vehicles
- 5.3.3 Chemicals, Petrochemicals, Oil & Gas
- 5.3.4 Construction, Infrastructure, and Remediation
- 5.3.5 Hi-Tech Industry
- 5.3.6 Energy and Utilities
- 5.3.7 Government and Defense
- 5.3.8 Pharmaceuticals, Healthcare & Laboratories
- 5.3.9 Manufacturing and Automotive
- 5.3.10 Mining and Metals
- 5.3.11 Others
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Peru
- 5.4.2.4 Chile
- 5.4.2.5 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Nordics (Denmark, Finland, Iceland, Norway, and Sweden)
- 5.4.3.8 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 India
- 5.4.4.3 Japan
- 5.4.4.4 South Korea
- 5.4.4.5 Australia
- 5.4.4.6 Southeast Asia (ASEAN)
- 5.4.4.7 Rest of Asia-Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Qatar
- 5.4.5.4 South Africa
- 5.4.5.5 Nigeria
- 5.4.5.6 Egypt
- 5.4.5.7 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Key Strategic Moves in the Market
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Geographic/Network Coverage, Products and Services, Recent Developments)
- 6.4.1 Veolia Environnement S.A.
- 6.4.2 Clean Harbors, Inc.
- 6.4.3 Waste Management, Inc.
- 6.4.4 SUEZ S.A.
- 6.4.5 Republic Services, Inc.
- 6.4.6 REMONDIS SE & Co. KG
- 6.4.7 GFL Environmental Inc.
- 6.4.8 Cleanaway Waste Management Limited
- 6.4.9 Biffa plc
- 6.4.10 Covanta Holding Corporation
- 6.4.11 Seche Environnement SA
- 6.4.12 Grupo Tradebe Medioambiente SL
- 6.4.13 Daiseki Co., Ltd.
- 6.4.14 Beijing Capital Eco-Environment Protection Group Co., Ltd.
- 6.4.15 Triumvirate Environmental, Inc.
- 6.4.16 EnviroServ Waste Management (Pty) Ltd
- 6.4.17 Perma-Fix Environmental Services, Inc.
- 6.4.18 Sharps Compliance, Inc.
- 6.4.19 Valicor Environmental Services
- 6.4.20 Sims Lifecycle Services
- 6.4.21 Arcwood Environmental, LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

