PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2185103

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2185103
Industrial Imaging API Platforms - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
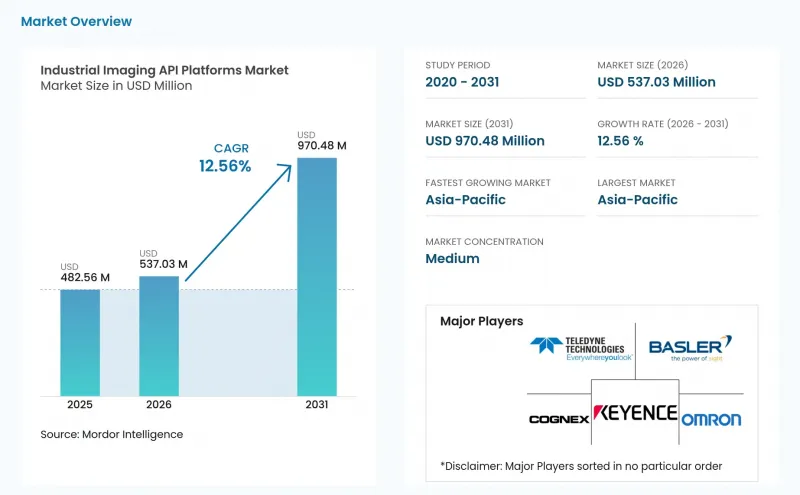
According to Mordor Intelligence, the industrial imaging API platforms market size is projected to expand from USD 482.18 million in 2025 and USD 537.03 million in 2026 to USD 970.48 million by 2031, registering a CAGR of 12.56% between 2026 to 2031.
Global Industrial Imaging API Platforms Market Trends and Insights
Factory Automation and Quality Inspection Adoption Drive Baseline Demand
The industrial imaging API platforms market benefits directly from factory automation spending and broader use of automated quality inspection. The International Federation of Robotics reported 542,000 industrial robot installations in 2024, and the operational robot fleet reached 4.66 million units globally. Robots used for inspection or pick-and-place work need camera control, image acquisition, and computer vision capabilities to perform their assigned tasks. The installed fleet creates replacement and expansion demand even when annual robot orders stabilize. The move toward 100% inline coverage increases the number of inspection points on a line and makes centralized software management more relevant. ISO 9001, IATF 16949, and pharmaceutical good manufacturing practice requirements make inspection systems more difficult to treat as optional productivity investments.
AI-Enabled Defect Detection and Adaptive Inspection Reshape Inspection Economics
The industrial imaging API platforms market is being shaped by AI functions that improve defect identification within production-line imaging workflows. A review found that machine-learning vision studies often reported defect-detection accuracy above 95%, with controlled settings reporting 98% to 100%. MVTec released HALCON 26.05 in May 2026 with a deep-learning object-detection architecture that provides up to 5x faster inference. Cognex stated that its In-Sight 6900 controller supports few-sample classification using 10-20 training images, reducing the amount of training data needed for some applications. Lower training-data requirements can shorten deployment work for smaller manufacturers that lack large labeled image libraries. The IMDD-1M dataset introduced at CVPR 2026 contains 1,000,000 aligned image-text pairs across more than 60 material categories and over 400 defect types, supporting wider availability of pretrained industrial vision models.
Integration Complexity With Legacy Automation Stacks Constrains Deployment Velocity
Legacy PLC, SCADA, and machine-controller systems remain a major barrier to wider platform deployment. Mature plants in North America and Europe often use Modbus, PROFIBUS, and DeviceNet architectures that were not designed for high-bandwidth image metadata or asynchronous image events. Modern imaging interfaces can therefore require custom middleware, protocol translation, and lengthy validation work. These requirements can extend projects by 12-18 months and consume budgets close to the software platform cost. Multi-vendor production lines can introduce additional issues even when camera devices follow GenICam standards. Food and beverage, pharmaceutical, and older automotive facilities often schedule installation work during maintenance windows because production interruptions carry a high operating cost.
Other drivers and restraints analyzed in the detailed report include:
- Edge Processing APIs Enable Low-Latency Industrial Decisions
- Vision-Guided Robotics Integration Extends the API Deployment Footprint
- Engineering Skills Scarcity Limits Deployment Scale Across All Verticals
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Computer Vision and AI Analytics APIs held 27.89% of the industrial imaging API platforms market share in 2025. The lead reflects a shift from transport functions toward software that interprets images and makes production decisions. Image acquisition and camera-control capabilities remain necessary for every inspection deployment. Their value is increasingly tied to AI functions for defect detection, measurement, and classification.
Image Management and Data APIs are projected to expand at a 13.78% CAGR through 2031. Manufacturers operating several sites need consistent management of images, model versions, and inspection records. EMVA released GenICam Package Version 2026.07 in July 2026, including GenApi 3.5.1, GenTL 1.6, SFNC 2.8, and GenDC 1.2. Cognex reported up to 50% lower scaling costs through centralized edge model management with OneVision. Camera-agnostic designs can reduce rework and support third-party analytics overlays.
Edge and On-Premises deployment held 62.34% of the industrial imaging API platforms market share in 2025. High-speed lines need prompt responses because delayed rejection signals can affect downstream output. Local architectures also align with data sovereignty and operational-network segmentation. IEC 62443 and the EU Cyber Resilience Act reinforce the focus on security for industrial control environments.
Cloud-Based deployment is projected to expand at a 13.21% CAGR through 2031. It is most relevant for centralized training, cross-site rollout, data governance, and version control. Cognex's OneVision architecture combines central development with local execution on In-Sight devices. Hybrid environments offer local response times and common model management across many production lines.
Complete Report Scope:
- By API Function
- Camera Control and Configuration APIs
- Image Acquisition and Streaming APIs
- Image Processing and Enhancement APIs
- Computer Vision and AI Analytics APIs
- Image Management and Data APIs
- Other API Functions
- By Deployment Model
- Edge / On-Premises
- Cloud-Based
- Hybrid
- By Imaging Technology
- 2D Area-Scan Imaging
- 2D Line-Scan Imaging
- 3D Imaging
- Thermal / Infrared Imaging
- Multispectral / Hyperspectral Imaging
- Other Imaging Technologies
- By Application
- Quality Inspection and Defect Detection
- Identification, Barcode Reading, and OCR
- Measurement and Gauging
- Positioning and Robot Guidance
- Predictive Maintenance and Process Monitoring
- Other Applications
- By End-User
- Automotive and Transportation
- Electronics and Semiconductors
- Pharmaceuticals and Medical Devices
- Food and Beverage
- Logistics and Warehousing
- Other End-Users
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of the Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific held 35.89% of the industrial imaging API platforms market share in 2025 and is projected to expand at a 13.55% CAGR through 2031. China supports demand through semiconductor capacity additions, advanced packaging, DRAM fabrication, and consumer-electronics production. Japan's precision manufacturing and robotics base supports automotive assembly, semiconductor inspection, and high-speed electronics. Mitsubishi Electric and Sony Semiconductor Solutions announced in July 2026 that their Advanced Vision Solutions Co., Ltd. joint venture is scheduled to begin operations in October 2026.
North America held the second-largest regional position in 2025. Its automotive, aerospace, semiconductor, pharmaceutical, and food-processing facilities face inspection requirements that support software deployment. The region also has a large installed base of collaborative robots and autonomous mobile robots. Europe remains important for automotive and machine-tool manufacturing in Germany, France, Italy, and the United Kingdom. VDMA stated that European machine vision expects 3% growth in 2026 after a three-year revenue contraction.
European component manufacturers reported 4% revenue expansion in 2025 even as system demand remained soft. The EU Cyber Resilience Act is affecting procurement requirements for connected industrial devices. TUV Rheinland issued the first IEC 62443-4-2:2026 certification for an industrial vision controller in May 2026. South America is an emerging demand base led by Brazil's automotive and agricultural-machinery sectors and Argentina's agri-food processing. The Middle East and Africa has greenfield demand that can use cloud-hybrid architectures without legacy integration barriers.
- Basler AG
- Cognex Corporation
- KEYENCE CORPORATION
- Teledyne Technologies Incorporated
- OMRON Corporation
- Allied Vision Technologies GmbH
- IDS Imaging Development Systems GmbH
- JAI A/S
- Baumer Holding AG
- SICK AG
- TKH Group N.V.
- MVTec Software GmbH
- National Instruments Corporation
- Pleora Technologies Inc.
- Euresys S.A.
- Matrox Electronic Systems Ltd.
- The Imaging Source Europe GmbH
- LMI Technologies Inc.
- Zebra Technologies Corporation
- NVIDIA Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Factory Automation and Quality-Inspection Adoption
- 4.2.2 AI-Enabled Defect Detection and Adaptive Inspection
- 4.2.3 Edge Processing for Low-Latency Industrial Decisions
- 4.2.4 Robotics and Vision-Guided Automation Integration
- 4.2.5 GenICam and GenTL Interoperability Demand
- 4.2.6 Camera-Agnostic APIs Reducing Application Rework
- 4.3 Market Restraints
- 4.3.1 Integration Complexity Across Legacy Automation Stacks
- 4.3.2 Shortage of Imaging and Industrial AI Engineering Skills
- 4.3.3 Deterministic-Latency Trade-Offs in Heterogeneous Edge Systems
- 4.3.4 Cybersecurity Exposure from Connected Imaging Endpoints
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Competitive Rivalry
- 4.8.2 Threat of New Entrants
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Bargaining Power of Buyers
- 4.8.5 Threat of Substitutes
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By API Function
- 5.1.1 Camera Control and Configuration APIs
- 5.1.2 Image Acquisition and Streaming APIs
- 5.1.3 Image Processing and Enhancement APIs
- 5.1.4 Computer Vision and AI Analytics APIs
- 5.1.5 Image Management and Data APIs
- 5.1.6 Other API Functions
- 5.2 By Deployment Model
- 5.2.1 Edge / On-Premises
- 5.2.2 Cloud-Based
- 5.2.3 Hybrid
- 5.3 By Imaging Technology
- 5.3.1 2D Area-Scan Imaging
- 5.3.2 2D Line-Scan Imaging
- 5.3.3 3D Imaging
- 5.3.4 Thermal / Infrared Imaging
- 5.3.5 Multispectral / Hyperspectral Imaging
- 5.3.6 Other Imaging Technologies
- 5.4 By Application
- 5.4.1 Quality Inspection and Defect Detection
- 5.4.2 Identification, Barcode Reading, and OCR
- 5.4.3 Measurement and Gauging
- 5.4.4 Positioning and Robot Guidance
- 5.4.5 Predictive Maintenance and Process Monitoring
- 5.4.6 Other Applications
- 5.5 By End-User
- 5.5.1 Automotive and Transportation
- 5.5.2 Electronics and Semiconductors
- 5.5.3 Pharmaceuticals and Medical Devices
- 5.5.4 Food and Beverage
- 5.5.5 Logistics and Warehousing
- 5.5.6 Other End-Users
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 ASEAN
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Rest of the Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Basler AG
- 6.4.2 Cognex Corporation
- 6.4.3 KEYENCE CORPORATION
- 6.4.4 Teledyne Technologies Incorporated
- 6.4.5 OMRON Corporation
- 6.4.6 Allied Vision Technologies GmbH
- 6.4.7 IDS Imaging Development Systems GmbH
- 6.4.8 JAI A/S
- 6.4.9 Baumer Holding AG
- 6.4.10 SICK AG
- 6.4.11 TKH Group N.V.
- 6.4.12 MVTec Software GmbH
- 6.4.13 National Instruments Corporation
- 6.4.14 Pleora Technologies Inc.
- 6.4.15 Euresys S.A.
- 6.4.16 Matrox Electronic Systems Ltd.
- 6.4.17 The Imaging Source Europe GmbH
- 6.4.18 LMI Technologies Inc.
- 6.4.19 Zebra Technologies Corporation
- 6.4.20 NVIDIA Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

