PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2185161

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2185161
Barrier Resins - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
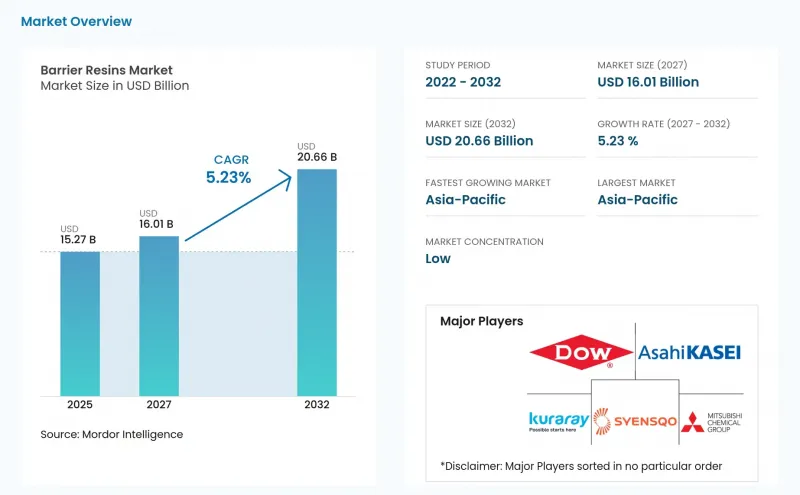
According to Mordor Intelligence, the barrier resins market size was valued at USD 15.27 billion in 2026 and is estimated to grow from USD 16.01 billion in 2027 to reach USD 20.66 billion by 2032, at a CAGR of 5.23% during the forecast period (2027-2032).
Global Barrier Resins Market Trends and Insights
Extended Shelf-Life Requirements for Packaged Foods and Beverages
Shelf-life extension reduces product losses across retail and foodservice supply chains, so it has direct value for retailers managing spoilage, inventory rotation, and product availability across different food categories, and it also helps food producers meet distribution requirements without relying only on heavier packaging or shorter delivery routes. A 1 mm EVOH layer can provide an oxygen barrier comparable to a 10-meter wall of Low-Density Polyethylene (LDPE), allowing thinner multilayer structures to protect food freshness. Ready-to-eat meals and quick-commerce grocery orders need films that can withstand more demanding handling conditions than conventional shelf display, including repeated loading, delivery, and temporary temperature changes. This need is particularly relevant where cold-chain capacity is limited, and packages need to maintain performance beyond a standard retail shelf cycle. Modified Atmosphere Packaging (MAP) using EVOH can extend refrigerated protein shelf life to 21-28 days, compared with 7-10 days without barrier protection. These operating needs keep food packaging as an important demand base for the barrier resins market because they support both waste reduction and product-quality requirements.
Pharmaceutical Cold-Chain and Sensitive-Drug Packaging
Pharmaceutical cold-chain use requires more exacting barrier specifications than food packaging because the contents can lose stability after moisture or oxygen exposure, and the material must also perform consistently across storage, handling, transport, and the final dispensing environment. A packaging failure can affect product quality, documentation requirements, and patient supply, making validated materials and suppliers important to pharmaceutical customers. Cell and gene therapies stored at -70 °C need films that retain structural integrity through cryogenic distribution and subsequent handling. Specialized Polyamide (PA) and EVOH multilayer structures are suited to these requirements because they combine protection with the mechanical performance needed in distribution. Biologics, messenger RNA vaccines, and gene therapies are sensitive to moisture and oxygen, which supports demand for premium grades in the barrier resins market. This application base gives suppliers a source of demand that is less tied to routine food-packaging volumes and more closely tied to validated technical performance.
Multilayer Packaging Recycling and Separation Complexity
Multilayer structures can protect products effectively but are difficult to separate in conventional mechanical recycling systems that were not designed for complex film constructions, and the problem is most visible in flexible packaging because thin layers are optimized for performance in use rather than for separation after use. They often combine EVOH, PA, polyethylene terephthalate (PET), and polyolefin layers with different processing behavior and different recycling pathways. Researchers reported that EVOH and non-polar polyethylene can phase-separate during melt processing, reducing recycled-material properties unless compatibilizers are used. This technical issue limits the use of high-barrier loading in locations with stricter recycling rules and raises the development burden for film producers. Michigan State University is developing polyester-based multilayer films intended for existing recycling streams with support from the U.S. Department of Energy. Until such solutions are used at scale, recycling complexity will remain a restraint on the barrier resins market because brand owners and converters need practical end-of-life routes.
Other drivers and restraints analyzed in the detailed report include:
- Recyclable Mono-Material Barrier Packaging Development
- PFAS-Free and Fluorine-Free Barrier Material Substitution
- Feedstock Price Volatility and Specialty Resin Premiums
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
EVOH held 24.86% of the barrier resins market share in 2026 and is projected to advance at a 5.76% CAGR through 2032. Its performance in oxygen-sensitive food and pharmaceutical packaging supports its position in premium applications. KURARAY CO., LTD. states that a 20 µm EVOH film has oxygen transmission below 1 cm3/m2*day under dry conditions. The company introduced Circular Eval, a 100% bio-based EVOH, in 2025 with International Sustainability and Carbon Certification Plus coverage for food-contact applications in the United States and Japan, giving packaging buyers a certified material choice. EVOH remains central to the barrier resins market as packaging designs seek barrier performance and circularity credentials.
Polyvinylidene chloride (PVDC) continues to serve pharmaceutical blister and shrink-wrap uses in Asia-Pacific, while KUREHA CORPORATION's Kuredux technology supports applications that require moisture protection and material compatibility. PA contributes structural strength and moderate barrier performance, while MXD6-grade PA can provide improved oxygen resistance and humidity tolerance. PET and polypropylene (PP) are generally used as structural outer layers in coextruded films, while polyvinyl alcohol (PVA) is gaining use as a water-soluble coating material for unit-dose products. Polyethylene naphthalate (PEN) and other resins serve high-temperature and high-clarity packaging formats. These materials give converters choices where the use environment requires a balance of barrier, strength, and clarity.
Oxygen and gas barrier held 60.12% of the barrier resins market share in 2026 and is projected to advance at a 5.91% CAGR through 2032. Oxygen exclusion is essential for food, pharmaceutical, and cosmetics supply chains that need to protect sensitive contents. EVOH is often selected where a low oxygen transmission rate is required. Pharmaceutical packaging can combine EVOH with PA in one coextruded structure to address both oxygen and moisture requirements, supporting demand across the principal material families. The scale of oxygen protection makes it a central functional requirement in the barrier resins market.
Moisture and water-vapor barrier serves tablets, agricultural chemicals, and water-soluble confectionery. PA and PVDC are important in these uses because EVOH performance can be affected by high humidity. South Asia and the Association of Southeast Asian Nations (ASEAN) have a stronger demand for moisture-focused barrier grades because of local ambient conditions. PET and PEN grades support applications that need both clarity and functional protection.
Complete Report Scope:
- By Resin Type
- Ethylene Vinyl Alcohol (EVOH)
- Polyvinylidene Chloride (PVDC)
- Polyethylene Naphthalate (PEN)
- Polyamide (PA)
- Polyethylene Terephthalate (PET)
- Polyethylene (PE)
- Polypropylene (PP)
- Polyvinyl Alcohol (PVA/PVOH)
- Bio-Based Barrier Resins
- Other Resin Types
- By Barrier Function
- Oxygen and Gas Barrier
- Moisture and Water-Vapor Barrier
- Other Barrier Functions
- By Packaging Type
- Flexible Packaging
- Rigid Packaging
- By End-Use Industry
- Food and Beverage
- Pharmaceutical and Medical
- Cosmetics and Personal Care
- Agriculture
- Industrial
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 42.35% of the barrier resins market share in 2026 and is projected to advance at a 6.27% CAGR through 2032. China supports regional demand through its food processing and pharmaceutical manufacturing base, while India is expanding through higher packaged food consumption and pharmaceutical production. Japan's Positive List system for food-contact packaging entered full implementation on June 1, 2025, which tightened compliance requirements for synthetic resins. Established suppliers with certified products may have an advantage in this environment. South Korea and ASEAN add demand through the development of mono-material EVOH films.
North American food processors use EVOH in ketchup bottles, juice containers, and vacuum-packaged meat, while state-level Extended Producer Responsibility requirements encourage recycle-compatible mono-material structures. In Europe, the Packaging and Packaging Waste Regulation is changing converter investment priorities toward recyclable packaging. Germany supports pharmaceutical packaging demand through specialized manufacturing clusters. Nordic markets are adopting EVOH and PVOH coatings as alternatives for paper-based barrier structures.
South America and the Middle East and Africa represent smaller but relevant areas for the barrier resins market. Brazil's processed food and beverage sector underpins demand in South America, while pharmaceutical packaging adds specialized requirements, and Argentina's economic volatility can favor simpler packaging structures. In the Middle East and Africa, retail modernization in Saudi Arabia and South Africa supports cold-chain packaging for fresh and chilled foods. Pharmaceutical expansion and wider organized retail distribution can add demand in secondary cities, although feedstock and freight costs can affect material selection.
- Arkema
- Asahi Kasei Corporation
- BASF
- Dow
- DuPont
- Henan Chuange Industry CO.,LTD
- KURARAY CO., LTD.
- KUREHA CORPORATION
- Mitsubishi Chemical Group Corporation
- Mitsui Chemicals, Inc.
- NIHON GOSEI KAKO Co.,Ltd.
- SABIC
- Syensqo
- TORAY INDUSTRIES, INC.
- UBE Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Extended Shelf-Life Requirements for Packaged Foods and Beverages
- 4.2.2 Pharmaceutical Cold-Chain and Sensitive-Drug Packaging
- 4.2.3 Recyclable Mono-Material Barrier Packaging Development
- 4.2.4 E-Commerce and Convenience Packaging Durability Requirements
- 4.2.5 PFAS-Free and Fluorine-Free Barrier Material Substitution
- 4.3 Market Restraints
- 4.3.1 Multilayer Packaging Recycling and Separation Complexity
- 4.3.2 Feedstock Price Volatility and Specialty Resin Premiums
- 4.3.3 Food-Contact Approval and Recyclability Certification Risk
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Resin Type
- 5.1.1 Ethylene Vinyl Alcohol (EVOH)
- 5.1.2 Polyvinylidene Chloride (PVDC)
- 5.1.3 Polyethylene Naphthalate (PEN)
- 5.1.4 Polyamide (PA)
- 5.1.5 Polyethylene Terephthalate (PET)
- 5.1.6 Polyethylene (PE)
- 5.1.7 Polypropylene (PP)
- 5.1.8 Polyvinyl Alcohol (PVA/PVOH)
- 5.1.9 Bio-Based Barrier Resins
- 5.1.10 Other Resin Types
- 5.2 By Barrier Function
- 5.2.1 Oxygen and Gas Barrier
- 5.2.2 Moisture and Water-Vapor Barrier
- 5.2.3 Other Barrier Functions
- 5.3 By Packaging Type
- 5.3.1 Flexible Packaging
- 5.3.2 Rigid Packaging
- 5.4 By End-Use Industry
- 5.4.1 Food and Beverage
- 5.4.2 Pharmaceutical and Medical
- 5.4.3 Cosmetics and Personal Care
- 5.4.4 Agriculture
- 5.4.5 Industrial
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN Countries
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 NORDIC Countries
- 5.5.3.6 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Arkema
- 6.4.2 Asahi Kasei Corporation
- 6.4.3 BASF
- 6.4.4 Dow
- 6.4.5 DuPont
- 6.4.6 Henan Chuange Industry CO.,LTD
- 6.4.7 KURARAY CO., LTD.
- 6.4.8 KUREHA CORPORATION
- 6.4.9 Mitsubishi Chemical Group Corporation
- 6.4.10 Mitsui Chemicals, Inc.
- 6.4.11 NIHON GOSEI KAKO Co.,Ltd.
- 6.4.12 SABIC
- 6.4.13 Syensqo
- 6.4.14 TORAY INDUSTRIES, INC.
- 6.4.15 UBE Corporation
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

