PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2185882

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2185882
North America Inspection Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2032)
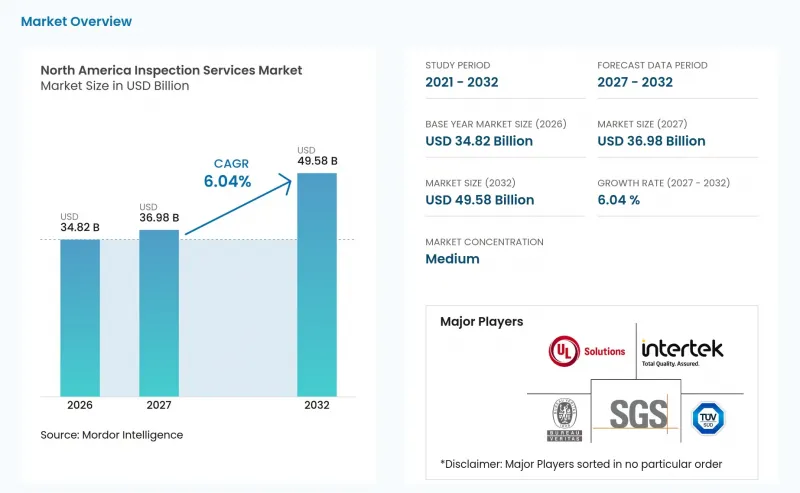
According to Mordor Intelligence, the North America inspection services market size is expected to grow from USD 34.82 billion in 2026 to USD 36.98 billion in 2027 and is forecast to reach USD 49.58 billion by 2032 at 6.04% CAGR over 2027-2032.
North America Inspection Services Market Trends and Insights
Stringent Regulatory and Standards Compliance
Compliance requirements create a durable demand floor for the North America inspection services market. In fiscal year 2025, OSHA conducted 30,273 inspections through programmed, complaint-driven, and fatality-related activities. These programs cover hazards that include respirable silica, combustible dust, and chemical processing. PHMSA requires hazardous-liquid pipeline patrols at frequencies that can reach 26 times each year. The May 2025 proposal on repair criteria and the August 2025 Periodic Standards Update II also reinforce the need for documented integrity assessments. These regulatory obligations support recurring demand for workplace safety inspections, pipeline integrity verification, equipment condition assessments, and corrective-action monitoring. Operators must maintain inspection records, demonstrate compliance with applicable standards, and address identified deficiencies, creating opportunities for providers that offer both field inspections and documentation support. The need for qualified personnel and technically reliable assessment methods further favors inspection firms with specialized expertise in industrial facilities, energy infrastructure, and hazardous operating environments.
Aging Industrial and Public Infrastructure
The North America inspection services market also benefits from maintenance and rehabilitation needs across public assets. ASCE gave the United States infrastructure a C grade in 2025, its highest grade to date, but identified a USD 3.7 trillion gap between planned investment and the needs required to restore assets to good condition. The assessment retained D-range grades for nine categories, including aviation, dams, energy, and roads. Federal bridge standards require inspection of eligible publicly owned bridges, while structures in fair condition can later require preservation and rehabilitation work. The Bridge Formula Program had apportioned USD 21.2 billion through fiscal year 2025 for 12,306 projects. This spending creates demand for pre-construction assessment, conformance checks, and post-rehabilitation documentation.
Price Competition and Cost Pressures in Standard Work
Routine property inspections, standard NDT screening, and periodic integrity checks face persistent price competition. Entry barriers are lower in these assignments, and clients can change providers with limited disruption. Smaller operators can compete for volume by offering lower prices, even when labor costs rise. Large providers seek to protect margins by combining field work with analytics, digital reporting, and condition-monitoring subscriptions. Those bundled offerings are harder for regional firms to replicate at scale. The North America inspection services market, therefore, has differing pricing conditions between standardized work and high-complexity assignments.
Other drivers and restraints analyzed in the detailed report include:
- Outsourcing and Cross-Border Supplier Qualification
- EV, Battery, Semiconductor, and Clean-Energy Asset Complexity
- Shortage of Certified Inspectors and Advanced Laboratory Specialists
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Building and property inspection services held 32% of the North America inspection services market share in 2026. The North America inspection services market has a recurring base in residential and commercial transactions where lenders require property-condition assessments. It also benefits from building-envelope, energy-code, and fire-safety checks for commercial properties. Owners of larger portfolios increasingly require ongoing documentation for resilience requirements and insurance reviews. These needs can lift assignment values above those of a single pre-sale inspection. UL Solutions launched ULTRUS Records for Buildings in North America in June 2026 to centralize inspection records and corrective-action management for multi-site portfolios. The North America inspection services market is moving from isolated field events toward ongoing compliance administration.
Civil infrastructure inspection services are forecast to grow at a 7.1% CAGR through 2032. The North America inspection services market size for this service domain is supported by bridge construction and rehabilitation activity under federal programs. The Bridge Formula Program had apportioned USD 21.2 billion for 12,306 projects through fiscal year 2025. The North America inspection services industry includes stable mid-tier demand from manufactured product and production-process inspection services and vehicle and mobile asset inspection services under original equipment manufacturer quality requirements. Commodity, cargo, and trade inspection services are projected to grow at a 7.5% CAGR through 2032. Its expansion is linked to supplier documentation and origin-verification needs across North American trade flows. The North America inspection services market, therefore, extends its customer base beyond construction and property activity.
Complete Report Scope:
- By Inspection Service Domain
- Building and Property Inspection Services
- Residential, Commercial and Institutional Building Inspections
- Structural, Building Envelope, MEP and Fire-Safety Inspections
- Property Condition, Construction and Handover Inspections
- Civil Infrastructure Inspection Services
- Roads, Bridges, Tunnels and Rail Track Infrastructure
- Dams, Civil Water Infrastructure and Other Civil Engineering Structures
- Industrial Facilities and Fixed Asset Inspection Services
- Industrial Plants and Installed Process Equipment
- Pressure Vessels, Pipelines and Storage Tanks
- Energy Generation and Utility Systems
- Other Stationary Industrial Equipment
- Manufactured Product and Production-Process Inspection Services
- Raw Material and Component Inspection
- In-Process Manufacturing Inspection
- Finished-Product and Production-Process Conformity Inspection
- Transportation Vehicle and Mobile Asset Inspection Services
- Road Vehicles and Commercial Fleets
- Rail Rolling Stock
- Aircraft and Aviation Assets
- Ships and Other Marine Vessels
- Other Mobile Transportation Assets
- Commodity, Cargo and Trade Inspection Services
- Bulk and Containerized Cargo Inspection
- Traded Commodity Inspection
- Consignment Condition, Quantity and Quality Verification
- Loading, Unloading and Custody-Transfer Inspection
- Other Operational Site and Process Inspection Services
- Physical Hygiene and Workplace Safety Inspection
- Agricultural Site Inspection
- Other Operational Compliance Inspection
- Building and Property Inspection Services
- By End-Use Industry
- Oil and Gas, Including Petroleum Refining and Petrochemicals
- Power Generation, Renewable Energy and Utilities
- Manufacturing and Industrial Processing (Excluding Industries Separately Classified)
- Construction, Real Estate and Civil Infrastructure
- Transportation and Logistics Operations
- Mining and Quarrying
- Agriculture, Food and Beverage
- Wholesale, Retail and Commodity Trading
- Healthcare, Pharmaceuticals and Life Sciences
- Households and Individual Consumers
- Other Commercial Services and Public Institutions
- By Geography
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- SGS SA
- Intertek Group plc
- Bureau Veritas SA
- UL Solutions Inc.
- TUV SUD AG
- TUV Rheinland AG
- Applus+ Services SA
- Eurofins Scientific SE
- DEKRA SE
- DNV AS
- TUV NORD GROUP
- ALS Limited
- Element Materials Technology Group Ltd.
- MISTRAS Group, Inc.
- Baker Hughes Company
- Acuren
- TEAM, Inc.
- Eddyfi Technologies
- FPrimeC Solutions Inc.
- CSA Group Testing and Certification Inc.
- NTS (National Technical Systems)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stringent Regulatory and Standards Compliance
- 4.2.2 Aging Industrial and Public Infrastructure
- 4.2.3 Outsourcing of Specialized Inspection Capabilities
- 4.2.4 EV, Battery, Semiconductor, and Clean-Energy Asset Complexity
- 4.2.5 Digital Inspection, AI, Robotics, and Remote-Delivery Adoption
- 4.2.6 Nearshoring-Driven Supplier Qualification in Mexico
- 4.3 Market Restraints
- 4.3.1 Price Competition and Commoditization of Standardized Inspection Work
- 4.3.2 Shortage of Certified Inspectors and Advanced Laboratory Specialists
- 4.3.3 High Cost of Advanced Inspection Equipment and Data Infrastructure
- 4.3.4 Unclear Evidentiary Acceptance of Remote and AI-Assisted Findings
- 4.4 Value and Supply-Chain Analysis
- 4.4.1 Inspection Equipment, Instrumentation and Software Providers
- 4.4.2 Independent Inspection Service Providers and Specialist Operators
- 4.4.3 Accreditation Bodies, Standards Organizations and Regulators
- 4.4.4 Supporting Testing Laboratories and Technical Service Providers
- 4.4.5 End Users, Asset Owners and Procurement Channels
- 4.5 Regulatory Landscape
- 4.5.1 United States Regulatory Bodies and Standards(FDA, EPA, OSHA, FCC, NHTSA, NIST, ANSI, and NRTL Requirements)
- 4.5.2 Canada Regulatory Bodies and Standards(Health Canada, CSA Group, Transport Canada, and Provincial Requirements)
- 4.5.3 Mexico Regulatory Bodies and Standards(NOM Standards, EMA, SENER, and Industrial Safety Requirements)
- 4.6 Technological Outlook
- 4.6.1 Conventional Visual and Manual Inspection Techniques
- 4.6.2 NDT-Based Inspection Techniques (Ultrasonic, Radiographic, Eddy Current, Magnetic Particle, Liquid Penetrant and Acoustic Methods)
- 4.6.3 Thermal Imaging, Laser Scanning and 3D Inspection Technologies
- 4.6.4 Drone, ROV, Crawler and Robotic Inspection Platforms
- 4.6.5 AI-Assisted Defect Detection and Computer Vision
- 4.6.6 IoT-Enabled Monitoring, Digital Twins and Predictive Inspection Analytics
- 4.6.7 Digital Inspection Reporting, Traceability and Data Interoperability
- 4.7 Inspection Service Procurement and Commercial Models
- 4.7.1 Statutory and Mandatory Inspection Demand versus Voluntary Inspection Demand
- 4.7.2 Project-Based versus Recurring Inspection Contracts
- 4.7.3 Pricing Structures - Per Inspection, Time-Based, Asset-Based and Contract-Based Fees
- 4.7.4 Inspection Frequency, Asset Criticality and Contract Renewal Dynamics
- 4.8 Macroeconomic and Industry Investment Cycle Impact
- 4.8.1 Impact of Industrial Capital Expenditure and Manufacturing Activity
- 4.8.2 Impact of Infrastructure Investment and Construction Cycles
- 4.8.3 Impact of Trade Activity and Global Supply-Chain Reconfiguration
5 Market Size And Growth Forecasts
- 5.1 By Inspection Service Domain
- 5.1.1 Building and Property Inspection Services
- 5.1.1.1 Residential, Commercial and Institutional Building Inspections
- 5.1.1.2 Structural, Building Envelope, MEP and Fire-Safety Inspections
- 5.1.1.3 Property Condition, Construction and Handover Inspections
- 5.1.2 Civil Infrastructure Inspection Services
- 5.1.2.1 Roads, Bridges, Tunnels and Rail Track Infrastructure
- 5.1.2.2 Dams, Civil Water Infrastructure and Other Civil Engineering Structures
- 5.1.3 Industrial Facilities and Fixed Asset Inspection Services
- 5.1.3.1 Industrial Plants and Installed Process Equipment
- 5.1.3.2 Pressure Vessels, Pipelines and Storage Tanks
- 5.1.3.3 Energy Generation and Utility Systems
- 5.1.3.4 Other Stationary Industrial Equipment
- 5.1.4 Manufactured Product and Production-Process Inspection Services
- 5.1.4.1 Raw Material and Component Inspection
- 5.1.4.2 In-Process Manufacturing Inspection
- 5.1.4.3 Finished-Product and Production-Process Conformity Inspection
- 5.1.5 Transportation Vehicle and Mobile Asset Inspection Services
- 5.1.5.1 Road Vehicles and Commercial Fleets
- 5.1.5.2 Rail Rolling Stock
- 5.1.5.3 Aircraft and Aviation Assets
- 5.1.5.4 Ships and Other Marine Vessels
- 5.1.5.5 Other Mobile Transportation Assets
- 5.1.6 Commodity, Cargo and Trade Inspection Services
- 5.1.6.1 Bulk and Containerized Cargo Inspection
- 5.1.6.2 Traded Commodity Inspection
- 5.1.6.3 Consignment Condition, Quantity and Quality Verification
- 5.1.6.4 Loading, Unloading and Custody-Transfer Inspection
- 5.1.7 Other Operational Site and Process Inspection Services
- 5.1.7.1 Physical Hygiene and Workplace Safety Inspection
- 5.1.7.2 Agricultural Site Inspection
- 5.1.7.3 Other Operational Compliance Inspection
- 5.1.1 Building and Property Inspection Services
- 5.2 By End-Use Industry
- 5.2.1 Oil and Gas, Including Petroleum Refining and Petrochemicals
- 5.2.2 Power Generation, Renewable Energy and Utilities
- 5.2.3 Manufacturing and Industrial Processing (Excluding Industries Separately Classified)
- 5.2.4 Construction, Real Estate and Civil Infrastructure
- 5.2.5 Transportation and Logistics Operations
- 5.2.6 Mining and Quarrying
- 5.2.7 Agriculture, Food and Beverage
- 5.2.8 Wholesale, Retail and Commodity Trading
- 5.2.9 Healthcare, Pharmaceuticals and Life Sciences
- 5.2.10 Households and Individual Consumers
- 5.2.11 Other Commercial Services and Public Institutions
- 5.3 By Geography
- 5.3.1 United States
- 5.3.2 Canada
- 5.3.3 Mexico
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Developments (Mergers/Acquisitions, Expansion and Service Portfolio Diversification, Investments in Digital Capabilities, Long-Term Inspection Contracts)
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 SGS SA
- 6.4.2 Intertek Group plc
- 6.4.3 Bureau Veritas SA
- 6.4.4 UL Solutions Inc.
- 6.4.5 TUV SUD AG
- 6.4.6 TUV Rheinland AG
- 6.4.7 Applus+ Services SA
- 6.4.8 Eurofins Scientific SE
- 6.4.9 DEKRA SE
- 6.4.10 DNV AS
- 6.4.11 TUV NORD GROUP
- 6.4.12 ALS Limited
- 6.4.13 Element Materials Technology Group Ltd.
- 6.4.14 MISTRAS Group, Inc.
- 6.4.15 Baker Hughes Company
- 6.4.16 Acuren
- 6.4.17 TEAM, Inc.
- 6.4.18 Eddyfi Technologies
- 6.4.19 FPrimeC Solutions Inc.
- 6.4.20 CSA Group Testing and Certification Inc.
- 6.4.21 NTS (National Technical Systems)
7 Market Opportunities And Future Outlook
- 7.1 White-Space and Unmet-Need Assessment
- 7.1.1 AI-Validated Inspection Evidence for Regulated Assets
- 7.1.2 Cross-Border Supplier Qualification for Nearshored Manufacturing
- 7.1.3 Battery, Semiconductor, and Advanced-Materials Inspection Capacity
- 7.1.4 Remote Inspection Acceptance and Interoperability Standards

