PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2186061

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2186061
Steel Casting - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
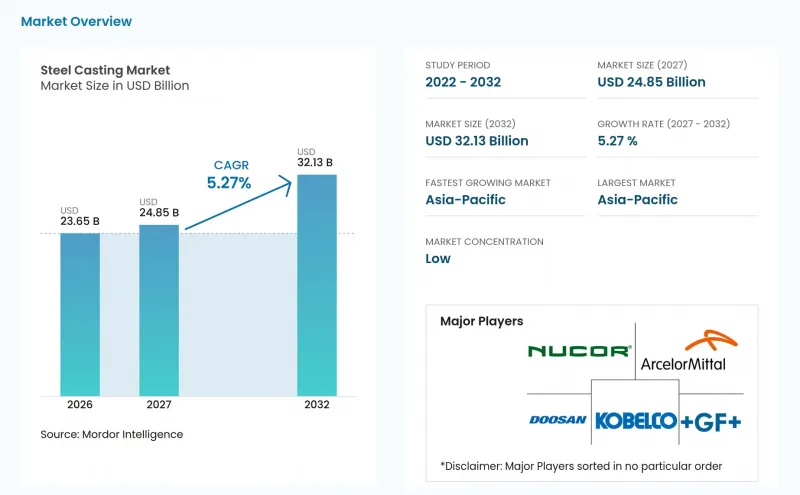
According to Mordor Intelligence, the steel casting market size was valued at USD 23.65 billion in 2026 and is estimated to grow from USD 24.85 billion in 2027 to reach USD 32.13 billion by 2032, at a CAGR of 5.27% during the forecast period (2027-2032).
Global Steel Casting Market Trends and Insights
Industrialization and Infrastructure Investment in Asia-Pacific
The steel casting market in Asia-Pacific benefits from public and private investment in transport, urban infrastructure, manufacturing, and power systems. India's steel demand grew 8.5% in 2025, compared with a global average of 1.2%, as spending on transportation, urban projects, and manufacturing remained strong. The region's demand base is changing as India, Vietnam, Thailand, and Indonesia add industrial capacity and expand casting-intensive sectors such as railways, mining equipment, and construction machinery. China remains an important consumer, but lower real estate investment has reduced the role of construction as the region's principal growth engine. This shifts supplier attention toward countries where industrial development is at an earlier stage and equipment procurement is rising. The steel casting market can benefit when foundries build certified relationships with local buyers before supply networks become established.
Railway Network Expansion and Rail-Freight Modernization
Rail systems require cast components for bogie frames, coupler systems, wheelsets, and track infrastructure because these parts work under repeated heavy loads. The steel casting market, therefore, has a durable connection to rail freight and passenger rail investment. India's Union Budget for fiscal year 2026 allocated INR 2.93 lakh crore (approximately USD 35.2 billion) for railway capacity growth, while Indian Railways planned procurement of 300,000 freight cars under its multi-year expansion program. The Steel Founders' Society of America projected North American railroad steel casting tonnage to rise 3% in 2026 after a 4% decline in 2025. Buyers are increasingly requiring longer fatigue life and closer dimensional control in rail parts.
Energy-Intensive Melting and Electricity-Price Volatility
Electric arc furnace melting is energy-intensive, and energy costs can account for 20%-40% of total production costs, depending on the operating configuration. The steel casting market is sensitive to electricity and gas price changes because melting is essential to every production cycle. The U.S. Energy Information Administration stated that natural gas delivered to power generators at USD 3.37 per million British thermal units in 2025, 24% above 2024 levels. Industrial electricity rates also face pressure from grid modernization, data center demand, and transport electrification. Smaller foundries have less ability to secure long-term energy contracts or operate co-located power assets. This can favor larger producers and lower-cost regions, while increasing cost pressure on independent operators in Europe and North America.
Other drivers and restraints analyzed in the detailed report include:
- Renewable-Power and Grid-Equipment Buildout
- Electric Vehicle and Heavy Vehicle Component Reconfiguration
- Competition from Aluminum, Composites, Forgings, and Fabrications
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Carbon steel casting held 33.51% of the market share in 2026, supported by a favorable cost-to-strength balance and broad use in rail, construction machinery, and general engineering. Its established position reflects existing processing infrastructure and long-running customer specifications. Standard carbon grades face price competition from foundries in China and India that serve commodity requirements. Low-alloy steel casting serves heavy machinery frames, pressure vessel shells, and pump housings where service conditions justify improved tensile and impact properties. These grades provide an intermediate option for buyers who do not require the cost and performance profile of high-alloy materials.
High-alloy steel casting is projected to advance at a 5.83% CAGR through 2032. It serves gas turbines, nuclear reactor internals, and subsea oil and gas equipment that operate in high-temperature, corrosive, or high-pressure conditions. The steel casting market benefits when these applications require duplex stainless steel or nickel-based compositions. A 2025 review identified integrated computational materials engineering as a tool for designing and optimizing complex metal casting geometries more efficiently. Standards including (American Society for Testing and Materials) A743/A744 and ASME SA-351 require material traceability for corrosion-resistant and pressure-retaining castings.
Complete Report Scope:
- By Type
- Carbon Steel Casting
- Low-Alloy Steel Casting
- High-Alloy Steel Casting
- Other Types
- By Process
- Sand Casting
- Investment Casting
- Die Casting
- Other Processes
- By Application
- Power Generation
- Rail and Transit
- Mining
- Construction Machinery
- Oil and Gas
- Aerospace and Defense
- Shipbuilding
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 54.62% of the steel casting market share in 2026 and is projected to advance at a 6.07% CAGR through 2032. The region has a large foundry base and receives substantial investment in power, transport, mining, and manufacturing equipment. India's steel demand grew 8.5% in 2025, compared with the global average of 1.2%, supported by spending on transportation, railways, and renewable energy. China remains a major steel consumer, although declining real estate investment is changing the composition of regional demand. India, Vietnam, Thailand, and Indonesia offer growing demand for rail, construction machinery, and mining equipment.
North America is a major regional buyer of cast steel for infrastructure, defense, energy, and critical supply chains. The Steel Founders' Society of America projected the North American steel castings market to grow 4% in 2026 after 2% growth in 2025. It also projected military segment tonnage to increase 8% in 2026, supported by ground vehicle and naval system demand. Europe has higher industrial electricity costs, which limits cost competitiveness in energy-intensive production. However, Europe retains technical strength in ultra-large and complex castings for defense, offshore energy, and nuclear applications.
South America is developing as a production base for mining wear castings, especially for copper and gold extraction. Bradken opened its Chilca, Peru, foundry in July 2026 with annual capacity of up to 20,000 metric tons and an investment exceeding USD 100 million. More than 99% of the facility's electricity comes from renewable sources. Middle East and Africa has favorable demand conditions from industrial diversification, oil and gas, and petrochemical projects.
- ArcelorMittal
- Bradken
- Doosan Enerbility
- Ferralloy Inc.
- Georg Fischer Ltd.
- Isgec Heavy Engineering Ltd.
- KOBE STEEL, LTD.
- Magotteaux
- Nelcast Limited
- Nucor Corporation
- POSCO
- Precision Castparts Corp.
- Sheffield Forgemasters
- The Japan Steel Works, Ltd.
- voestalpine Stahl GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Railway Network Expansion and Rail-Freight Modernization
- 4.2.2 Renewable-Power and Grid-Equipment Buildout
- 4.2.3 Industrialization and Infrastructure Investment in Asia-Pacific
- 4.2.4 Electric Vehicle and Heavy Vehicle Component Reconfiguration
- 4.2.5 Digital Casting, Simulation, and Automated Quality Control
- 4.3 Market Restraints
- 4.3.1 Energy-Intensive Melting and Electricity-Price Volatility
- 4.3.2 Competition from Aluminum, Composites, Forgings, and Fabrications
- 4.3.3 Scarcity of Patternmakers, Metallurgists, and Skilled Foundry Labor
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Carbon Steel Casting
- 5.1.2 Low-Alloy Steel Casting
- 5.1.3 High-Alloy Steel Casting
- 5.1.4 Other Types
- 5.2 By Process
- 5.2.1 Sand Casting
- 5.2.2 Investment Casting
- 5.2.3 Die Casting
- 5.2.4 Other Processes
- 5.3 By Application
- 5.3.1 Power Generation
- 5.3.2 Rail and Transit
- 5.3.3 Mining
- 5.3.4 Construction Machinery
- 5.3.5 Oil and Gas
- 5.3.6 Aerospace and Defense
- 5.3.7 Shipbuilding
- 5.3.8 Other Applications
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 ArcelorMittal
- 6.4.2 Bradken
- 6.4.3 Doosan Enerbility
- 6.4.4 Ferralloy Inc.
- 6.4.5 Georg Fischer Ltd.
- 6.4.6 Isgec Heavy Engineering Ltd.
- 6.4.7 KOBE STEEL, LTD.
- 6.4.8 Magotteaux
- 6.4.9 Nelcast Limited
- 6.4.10 Nucor Corporation
- 6.4.11 POSCO
- 6.4.12 Precision Castparts Corp.
- 6.4.13 Sheffield Forgemasters
- 6.4.14 The Japan Steel Works, Ltd.
- 6.4.15 voestalpine Stahl GmbH
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

