PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2186066

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2186066
Hydrogen Sulfide Scavengers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
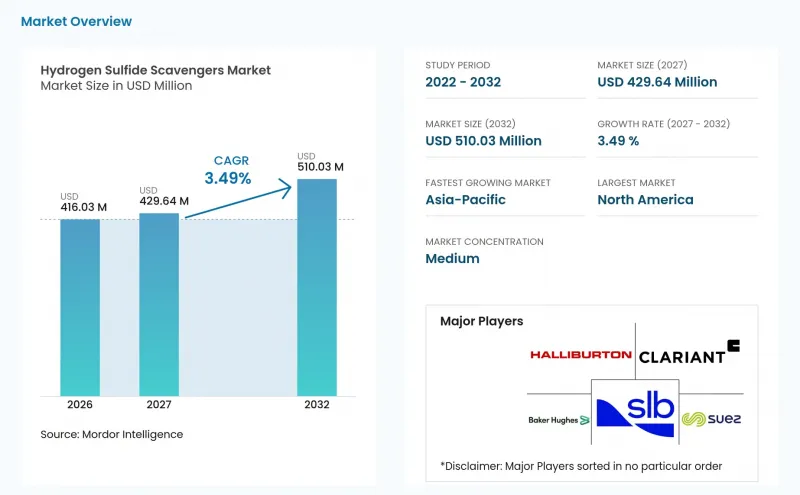
According to Mordor Intelligence, the hydrogen sulfide scavengers market size was valued at USD 416.03 million in 2026 and is estimated to grow from USD 429.64 million in 2027 to USD 510.03 million by 2032, at a CAGR of 3.49% during the forecast period (2027-2032).
Global Hydrogen Sulfide Scavengers Market Trends and Insights
Expansion of Sour Oil and Gas Production
The hydrogen sulfide scavengers market benefits as sour field development continues to attract capital, particularly in the Middle East and offshore Latin America. China reported record crude output of 216.09 million metric tons in 2025, while its natural gas output reached 261.89 billion cubic meters. Gas production recorded its ninth consecutive annual increase of more than 10 billion cubic meters, supporting additional treatment demand across production and processing facilities. H2S levels can be variable and unpredictable in these fields, prompting operators to secure scavenger supplies at an early stage of development. A 2025 deepwater study documented H2S concentrations exceeding 100 parts per million (ppm) in a field previously described as sweet, underscoring the need for treatment planning to account for geological uncertainty.
Stricter H2S Exposure, Emissions, and Product-Specification Requirements
Enforcement actions are influencing procurement decisions across the hydrogen sulfide scavengers market. On April 15, 2025, the U.S. Department of Justice announced a USD 1 million fine and 2-year probation for Aghorn Operating following worker-safety and Clean Air Act violations related to H2S incidents. A co-defendant also received a 5-month prison sentence. OSHA Process Safety Management rules identify H2S as a highly hazardous chemical, while the U.S. EPA extended selected oil and gas compliance deadlines through its 2025 interim final rule. Pipeline gas specifications also require controlled H2S levels, making chemical treatment necessary for access to transmission systems. China tightened its natural gas sulfur specification to 15 mg/m3 from 20 mg/m3, increasing the need for treatment at processing and downstream nodes. These requirements extend demand from upstream production into midstream polishing applications.
Spent-Scavenger Disposal and Byproduct Compliance Costs
Spent-scavenger management adds an additional operating cost to the hydrogen sulfide scavenger market that increases with treatment quantities. MEA-triazine produces spent and unspent scavenger wastewater that can be difficult to manage in offshore operations. A 2025 study examined the hydrothermal oxidation of this stream and identified the need for treatment pathways to address its chemical burden. North Sea operators face increasing scrutiny of triazine discharge in produced-water streams. Residual triazine can also introduce nitrogen compounds into crude feedstock, which may contribute to fouling and refinery penalties. This cost exposure drives work on non-triazine formulations and recovery technologies that may recycle unspent chemicals. The Convention for the Protection of the Marine Environment of the North-East Atlantic (OSPAR) discharge requirements set an additional practical limit on triazine dosing at offshore installations.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Liquefied Natural Gas (LNG), Biogas, and Decentralized Gas Processing
- Offshore and Deepwater Production Requiring In-Situ H2S Control
- Variable H2S Loading Increases Overdosing and Treatment Uncertainty
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Water-soluble scavengers held 60.13% of the hydrogen sulfide scavengers market share in 2026, reflecting their broad use in produced-water streams, pipeline gas, and surface crude treatment. Aqueous-phase injection is well-suited to conventional onshore and shallow-offshore sites because it aligns with existing equipment and operating practices used by field teams. These products support continuous treatment where H2S must be controlled before fluids enter separation, handling, storage, or export systems. Their established role also gives operators familiar approaches to managing routine H2S exposure and meeting product specifications. This installed operational base keeps water-soluble products central to the hydrogen sulfide scavengers market, even as more demanding wells require other formulations.
Oil-soluble scavengers are projected to grow at a 3.78% CAGR through 2032 because deepwater and high-temperature completions can limit the reactivity or phase distribution of water-based products. A Petrobras study tested products at 130°C and 33.1 kPa across oils of different densities and found that ethoxylated oil-phase scavengers outperformed monoethanolamine (MEA), triazine, and glyoxal under these conditions. Gas-phase scavengers remain necessary in dry-gas pipelines and at wellheads where liquid application is not practical, while non-formaldehyde and non-triazine options are also advancing. A 2025 Society of Petroleum Engineers (SPE) paper reported that lignosulfonate-based products achieved competitive H2S removal with lower pH elevation. This feature can reduce the risk of calcite scaling in offshore carbonate reservoirs. The resulting type mix allows treatment programs to be adapted to phase behavior, operating temperature, equipment design, and the constraints of downstream facilities.
Complete Report Scope:
- By Type
- Water-Soluble Scavengers
- Oil-Soluble Scavengers
- Gas-Phase Scavengers
- By Chemistry
- Triazine
- Nitrite
- Iron Sponge
- Other Chemistries
- By End-Use Industry
- Crude Oil Production and Stabilization
- Natural Gas Processing and Pipeline Gas
- Refining and Refined Products
- Geothermal Energy
- Industrial Processes
- Other End-Uses
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
North America accounted for 31.48% of the hydrogen sulfide scavengers market share in 2026, supported by Permian Basin sour-crude production and dense infrastructure for crude oil and associated gas. US Process Safety Management rules and Texas H2S contingency requirements establish a compliance baseline, while Permian wells may require continuous injection as H2S levels change with production stage and water cut. Canada adds demand through Alberta oil sands and heavy-crude activity, where bitumen upgrading produces H2S streams that require dedicated treatment. Mexico contributes through mature Gulf of Mexico assets that increasingly use chemical scavengers as gas-sweetening capacity ages. Together, these conditions support recurring use across production, processing, transport, and related field services.
In the hydrogen sulfide scavengers market, Asia-Pacific is forecast to grow at a 4.03% CAGR through 2032 as upstream activity, refinery sour-feedstock throughput, LNG infrastructure, and biogas facilities expand. China's record gas production in 2025 and its stricter 15 mg/m3 sulfur specification support investment at processing nodes. India, South Korea, and Southeast Asian countries process increasing quantities of sour crude that require refinery-side treatment. Japan's declining crude demand is an offset, but does not alter the wider regional pattern of upstream and refinery-side growth. This mix of oil, gas, LNG, biogas, and refining activity makes Asia-Pacific the fastest-growing regional demand base.
Europe has a mature base in the hydrogen sulfide scavengers market, centered on the North Sea, where aging wells with higher water cuts create variable H2S loading and encourage automated dosing. Disposal rules under the OSPAR Convention and the EU Industrial Emissions Directive support lower-footprint formulations. Brazil and Guyana generate offshore demand for subsea-qualified programs, and Baker Hughes' 2025 contract with ExxonMobil Guyana demonstrates the scale of integrated chemical supply at those Floating Production, Storage, and Offloading (FPSO) developments. The Middle East and Africa have significant structural exposure to sour-gas fields in Saudi Arabia, Kuwait, and Abu Dhabi, while the development of LNG import activity in South Africa and other sub-Saharan markets supports related gas-treatment investment.
- Arkema
- Baker Hughes Company
- BASF
- ChemTreat, Inc.
- CLARIANT
- Dorf Ketal
- Ecolab Inc.
- Halliburton
- Hexion Inc.
- Kurita Water Industries Ltd.
- Lubrizol
- Merichem Technologies
- Q2Technologies
- SLB
- SUEZ
- Veolia
- Vink Chemicals GmbH & Co. KG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Sour Oil and Gas Production
- 4.2.2 Stricter H2S Exposure, Emissions, and Product-Specification Requirements
- 4.2.3 Growth of LNG, Biogas, and Decentralized Gas Processing
- 4.2.4 Offshore and Deepwater Production Requiring In-Situ H2S Control
- 4.2.5 Digital Monitoring and Automated Chemical Dosing
- 4.3 Market Restraints
- 4.3.1 Spent-Scavenger Disposal and Byproduct Compliance Costs
- 4.3.2 Variable H2S Loading Increases Overdosing and Treatment Uncertainty
- 4.3.3 High Water Cut, Temperature, and Multiphase Conditions Reduce Efficiency
- 4.4 Value and Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Water-Soluble Scavengers
- 5.1.2 Oil-Soluble Scavengers
- 5.1.3 Gas-Phase Scavengers
- 5.2 By Chemistry
- 5.2.1 Triazine
- 5.2.2 Nitrite
- 5.2.3 Iron Sponge
- 5.2.4 Other Chemistries
- 5.3 By End-Use Industry
- 5.3.1 Crude Oil Production and Stabilization
- 5.3.2 Natural Gas Processing and Pipeline Gas
- 5.3.3 Refining and Refined Products
- 5.3.4 Geothermal Energy
- 5.3.5 Industrial Processes
- 5.3.6 Other End-Uses
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Arkema
- 6.4.2 Baker Hughes Company
- 6.4.3 BASF
- 6.4.4 ChemTreat, Inc.
- 6.4.5 CLARIANT
- 6.4.6 Dorf Ketal
- 6.4.7 Ecolab Inc.
- 6.4.8 Halliburton
- 6.4.9 Hexion Inc.
- 6.4.10 Kurita Water Industries Ltd.
- 6.4.11 Lubrizol
- 6.4.12 Merichem Technologies
- 6.4.13 Q2Technologies
- 6.4.14 SLB
- 6.4.15 SUEZ
- 6.4.16 Veolia
- 6.4.17 Vink Chemicals GmbH & Co. KG
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

