PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2186099

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2186099
Thailand Beach Hotels and Resorts - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
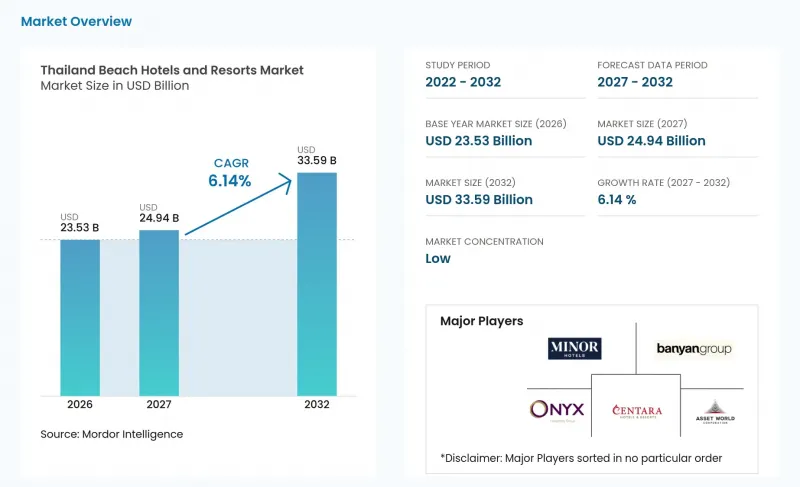
According to Mordor Intelligence, the Thailand beach hotels and resorts market size was valued at USD 23.53 billion in 2026 and is estimated to grow from USD 24.94 billion in 2027 to reach USD 33.59 billion by 2032, at a CAGR of 6.14% during the forecast period (2027-2032).
Thailand Beach Hotels and Resorts Market Trends and Insights
Recovery and Diversification of International Arrivals
Thailand recorded 32.97 million international arrivals in 2025, down 7.23% from the previous year. However, shifts in the visitor mix have affected demand for beach resorts. India contributed 2.49 million arrivals and THB 93.86 billion (USD 2.98 billion) in tourism revenue in 2025, while the Ministry of Tourism and Sports reported a 22.61% increase in spending. This trend diversified the demand base for the Thailand beach hotels and resorts market and reduced reliance on large group-tour volumes from a single source market. Indian travelers were particularly relevant to Phuket, Krabi, and Koh Samui, given demand for destination weddings, family vacations, luxury stays, and short-haul international travel. Thailand's 2026 target of 36.7 million international arrivals and THB 2.78 trillion (USD 88.3 billion) in tourism revenue depends on demand from Western Europe, India, Russia, the Middle East, and China. Properties offering personalized services, flexible family accommodation, and credible wedding or wellness packages were better positioned to address this diverse visitor mix.
Premiumization of Coastal Stays and Experiential Hospitality
Coastal stays are becoming more central to the Thailand beach hotels and resorts market, as guests pay for privacy, wellness, dining, and distinctive resort settings. Luxury and upper-upscale properties can command higher rates by offering private villas, tailored activities, and strong service standards. International hotel groups' development pipelines continue to include luxury resort concepts in Phuket and Koh Samui. This trend is widening the gap between luxury resorts and properties that compete primarily on room rates. Destination wedding groups, including those from India, also support this positioning, as event budgets can include accommodations, food and beverage, ceremony venues, and extended stays. Operators gain the greatest commercial benefit when they position beach locations as complete stays rather than room-only products.
Seasonal Demand Fluctuations
Seasonal demand poses an operational challenge for beach hotels, as room demand, occupancy, and guest spending vary significantly by month. The Andaman Coast experiences a monsoon period from May to October, while the Gulf of Thailand follows a different rainfall pattern, providing portfolio balance. The Thailand beach hotels and resorts market requires flexible staffing, pricing, and promotional strategies during off-peak periods. Domestic tourism provides an occupancy base, with Thailand recording 202.37 million domestic trips in 2025. Domestic travelers may book closer to travel dates and respond to package offers, making effective rate management essential for coastal operators. Resorts with properties in both the Andaman and Gulf regions can leverage their differing peak seasons more effectively than single-destination operators.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Integrated Resorts
- Growth in Mobile, OTA, and Direct Reservations
- Exposure to International Tourism Downturns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Luxury beach hotels and resorts accounted for 32.94% of the Thailand beach hotels and resorts market in 2026. International demand drives the segment through private villas, oceanfront locations, wellness facilities, high-quality dining, and personalized service. Luxury operators attract international wedding groups and affluent families requiring event spaces and larger accommodations. Hilton initially planned to open the 55-room Nivata Koh Samui, Tapestry Collection by Hilton, on Thong Tanote Beach in June 2026, and reservations are now open from November 2026. The project reflects the expansion of smaller, locally distinctive coastal resorts, while mid-range properties face competition from internationally branded upscale hotels and alternative accommodations.
Eco-resorts and regenerative beach resorts are projected to grow at a CAGR of 6.94% through 2032. Phuket's GSTC Destination Assessment scored environmental sustainability at 1.43 out of 5, its weakest pillar and an area of moderate risk, highlighting the need for stronger visitor management, environmental protection, and resource management. In June 2026, OUTRIGGER achieved Green Key certification for three Thailand beachfront resorts. Budget, boutique, and lifestyle formats continue to serve domestic, backpacker, design-led, and location-sensitive demand.
Online travel agencies (OTAs) accounted for 40.72% of the Thailand beach hotels and resorts market size in 2026. They help international travelers compare rates, reviews, locations, and room types before selecting coastal properties. OTAs are particularly important for independent resorts without large marketing budgets or global loyalty programs. However, commissions reduce the net room revenue retained per reservation. Hotels therefore need to manage their channel mix, using OTAs for visibility while strengthening direct websites for repeat guests and higher-value inquiries.
Direct booking channels are forecast to grow at a CAGR of 7.24% through 2032, supported by investments in booking engines, loyalty programs, direct-only packages, and hotel applications. Minor Hotels' unified app strategy facilitates repeat bookings across multiple brands. Direct channels can help international travelers by clearly communicating room occupancy policies, wedding services, family facilities, meal options, and guest support. Corporate and travel management company bookings remain relevant in destinations with meetings and events activity, including Pattaya and Phuket. Offline agents also support travelers seeking packaged beach holidays or assistance with complex group arrangements.
Complete Report Scope:
- By Accommodation Type
- Luxury Beach Hotels and Resorts
- Mid-Range Beach Hotels and Resorts
- Budget Beach Hotels, Hostels, and Guesthouses
- Boutique and Lifestyle Beach Hotels
- Eco-Resorts and Regenerative Beach Resorts
- By Booking Channel
- Direct Booking Channels
- Online Travel Agencies (OTAs)
- Corporate / Travel Management Companies
- Offline Travel Agents
- By Property Type
- Chain / Branded Properties
- Independent Properties
- By Tourism Type
- Domestic Tourism
- International Tourism
- By Geography
- Southern Thailand - Andaman Coast (Phuket, Krabi, etc.)
- Southern Thailand - Gulf Coast (Koh Samui, Koh Phangan, Koh Tao)
- Eastern Thailand (Pattaya, Koh Samet, Koh Chang)
- Other Coastal Destinations (Hua Hin, Cha-Am, other coastal areas)
List of Companies Covered in this Report:
- Minor Hotels
- Centara Hotels & Resorts
- ONYX Hospitality Group
- Dusit Hotels and Resorts
- Banyan Group
- Marriott International
- Hilton
- Hyatt Hotels Corporation
- Accor
- InterContinental Hotels Group (IHG)
- Kata Group Resorts
- S Hotels and Resorts
- Asset World Corporation
- Cape & Kantary Hotels
- Ravindra Beach Resort & Spa
- Aleenta Resorts
- Four Seasons Hotels and Resorts
- Outrigger Hospitality Group
- Aman Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Executive Summary
3 Market Landscape
- 3.1 Market Overview
- 3.2 Market Drivers
- 3.2.1 Recovery and diversification of international arrivals across Phuket, Krabi, Koh Samui, Pattaya, and Khao Lak
- 3.2.2 Premiumization of coastal stays, luxury resorts, private pool villas, and experiential hospitality
- 3.2.3 Expansion of integrated resorts combining accommodation, dining, wellness, marine activities, and entertainment
- 3.2.4 Growth in mobile bookings, OTAs, social-media discovery, and direct hotel reservations
- 3.2.5 Rising demand for destination weddings, wellness retreats, island-hopping, and family resort holidays
- 3.2.6 Hotel investment and upgrades supported by tourism infrastructure and connectivity improvements
- 3.3 Market Restraints
- 3.3.1 Seasonal demand fluctuations across the Andaman coast and Gulf of Thailand
- 3.3.2 Exposure to international tourism downturns and fluctuations in key source markets
- 3.3.3 Competition from villas, condominiums, holiday rentals, and unlicensed accommodation
- 3.3.4 Environmental restrictions, coastal land-use rules, and infrastructure pressures in high-density resort destinations
- 3.4 Regulatory Landscape
- 3.5 Technological Outlook
- 3.6 Porter's Five Forces Analysis
- 3.6.1 Threat of New Entrants
- 3.6.2 Bargaining Power of Suppliers
- 3.6.3 Bargaining Power of Buyers
- 3.6.4 Threat of Substitutes
- 3.6.5 Intensity of Competitive Rivalry
4 Hospitality Supply & Development Intelligence
- 4.1 Supply Landscape & Development Trends
- 4.2 Existing Hospitality Supply and Room Inventory
5 Hospitality Performance Intelligence
- 5.1 Occupany Rates
- 5.2 Averages Daily Rates
6 Consumer Behavior Analysis
- 6.1 Traveler Preferences and Demand Patterns
- 6.2 Booking Behavior and Channel Preferences
- 6.3 Travel Spending and Emerging Preferences
7 Global Beach Hotels and Resorts Market Size & Growth Forecasts (Value) 2022- 2032
- 7.1 By Accommodation Type
- 7.1.1 Luxury Beach Hotels and Resorts
- 7.1.2 Mid-Range Beach Hotels and Resorts
- 7.1.3 Budget Beach Hotels, Hostels, and Guesthouses
- 7.1.4 Boutique and Lifestyle Beach Hotels
- 7.1.5 Eco-Resorts and Regenerative Beach Resorts
- 7.2 By Booking Channel
- 7.2.1 Direct Booking Channels
- 7.2.2 Online Travel Agencies (OTAs)
- 7.2.3 Corporate / Travel Management Companies
- 7.2.4 Offline Travel Agents
- 7.3 By Property Type
- 7.3.1 Chain / Branded Properties
- 7.3.2 Independent Properties
- 7.4 By Tourism Type
- 7.4.1 Domestic Tourism
- 7.4.2 International Tourism
- 7.5 By Geography
- 7.5.1 Southern Thailand - Andaman Coast (Phuket, Krabi, etc.)
- 7.5.2 Southern Thailand - Gulf Coast (Koh Samui, Koh Phangan, Koh Tao)
- 7.5.3 Eastern Thailand (Pattaya, Koh Samet, Koh Chang)
- 7.5.4 Other Coastal Destinations (Hua Hin, Cha-Am, other coastal areas)
8 Southern Thailand - Andaman Coast Beach Hotels and Resorts Market Size & Growth Forecasts (Value) 2022- 2032
- 8.1 By Accommodation Type
- 8.2 By Booking Channel
- 8.3 By Property Type
- 8.4 By Tourism Type
9 Southern Thailand - Gulf Coast Beach Hotels and Resorts Market Size & Growth Forecasts (Value) 2022- 2032
- 9.1 By Accommodation Type
- 9.2 By Booking Channel
- 9.3 By Property Type
- 9.4 By Tourism Type
10 Eastern Thailand Beach Hotels and Resorts Market Size & Growth Forecasts (Value) 2022- 2032
- 10.1 By Accommodation Type
- 10.2 By Booking Channel
- 10.3 By Property Type
- 10.4 By Tourism Type
11 Other Coastal Destinations Beach Hotels and Resorts Market Size & Growth Forecasts (Value) 2022- 2032
- 11.1 By Accommodation Type
- 11.2 By Booking Channel
- 11.3 By Property Type
- 11.4 By Tourism Type
12 Competitive Landscape
- 12.1 Market Concentration
- 12.2 Strategic Moves
- 12.3 Market Share Analysis
- 12.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 12.4.1 Minor Hotels
- 12.4.2 Centara Hotels & Resorts
- 12.4.3 ONYX Hospitality Group
- 12.4.4 Dusit Hotels and Resorts
- 12.4.5 Banyan Group
- 12.4.6 Marriott International
- 12.4.7 Hilton
- 12.4.8 Hyatt Hotels Corporation
- 12.4.9 Accor
- 12.4.10 InterContinental Hotels Group (IHG)
- 12.4.11 Kata Group Resorts
- 12.4.12 S Hotels and Resorts
- 12.4.13 Asset World Corporation
- 12.4.14 Cape & Kantary Hotels
- 12.4.15 Ravindra Beach Resort & Spa
- 12.4.16 Aleenta Resorts
- 12.4.17 Four Seasons Hotels and Resorts
- 12.4.18 Outrigger Hospitality Group
- 12.4.19 Aman Group
13 Market Opportunities & Future Outlook
- 13.1 Market Opportunities
- 13.1.1 Development of Sustainable and Nature-Based Beach Resorts
- 13.1.2 Expansion of Premium Resort Offerings Beyond Established Destinations:
- 13.2 Future Outlook
14 Research Methodology

