PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2186106

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2186106
Smoked Cheese - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
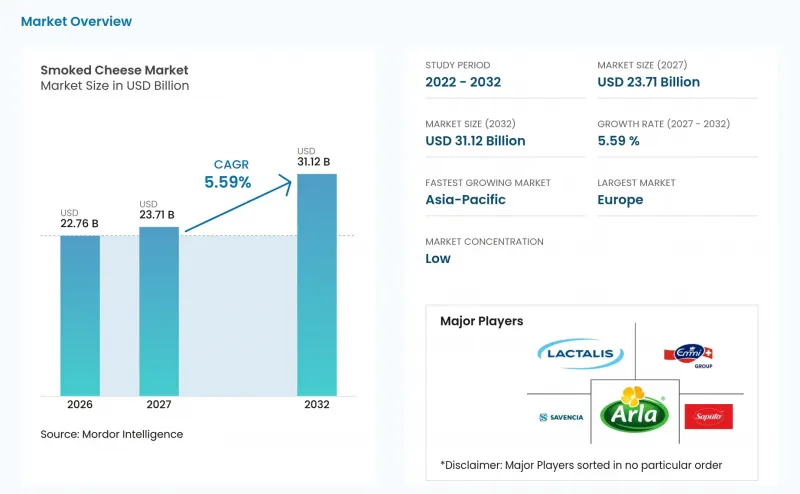
According to Mordor Intelligence, the smoked cheese market size is expected to grow from USD 22.76 billion in 2026 to USD 23.71 billion in 2027 and is forecast to reach USD 31.12 billion by 2032 at a 5.59% CAGR over 2027-2032.
Global Smoked Cheese Market Trends and Insights
Growing Consumption of Cheese and Demand for Specialty Varieties
Growing cheese consumption and evolving preferences for diverse flavors create opportunities for smoked cheese by encouraging interest in differentiated dairy products. According to the United States Department of Agriculture's Foreign Agricultural Service, total cheese consumption across the markets covered in its December 2024 report reached 21.172 million metric tons in 2024. This substantial consumption base provides opportunities for specialty varieties to attract consumers seeking alternatives to conventional cheese offerings. Smoked cheese can capitalize on this demand by offering a distinctive flavor profile and versatility across cooking, snacking, sandwiches, and foodservice applications. Its characteristic smoky taste also provides manufacturers and foodservice operators with opportunities to differentiate products and menu offerings.
Expansion of Gourmet Foodservice and Restaurant Applications
The expansion of gourmet foodservice and restaurant applications is creating opportunities for smoked cheese as operators seek distinctive ingredients to enhance menu appeal and differentiate their offerings. According to the National Restaurant Association, United States restaurant and foodservice sales are projected to reach USD 1.55 trillion by the end of 2026, with inflation-adjusted sales expected to grow by 1.3%. This projected expansion provides a favorable backdrop for specialty ingredients used in premium dining and innovative menu development. Smoked cheese can benefit from its incorporation into gourmet pizzas, burgers, sandwiches, sauces, and other restaurant dishes, where its distinctive smoky flavor complements diverse ingredients and elevates familiar menu items. As foodservice operators continue to develop differentiated dining experiences, smoked cheese offers opportunities to introduce more distinctive flavor profiles across gourmet menus.
Food Safety Risks and Contaminant Control in Smoked Cheese
Food safety risks and contaminant control present challenges for smoked cheese manufacturers, as smoking processes must be carefully managed to maintain product safety and quality. Exposure to smoke can introduce undesirable compounds, including polycyclic aromatic hydrocarbons, depending on the smoking method, fuel source, temperature, and duration of exposure. Inadequate control of processing conditions may also affect product consistency and increase the risk of contamination during manufacturing and handling. Producers must therefore maintain appropriate smoking parameters, hygienic processing environments, and routine quality checks to ensure compliance with applicable food safety requirements. These controls can increase production complexity and operating costs, particularly for manufacturers seeking to balance distinctive smoky flavors with consistent product quality and safety.
Other drivers and restraints analyzed in the detailed report include:
- Growing Demand for Natural, Protein-Rich Cheese Products
- Innovation in Smoking Techniques and Smoked Cheese Product Development
- High Production Costs and Refrigeration Requirements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Smoked cheddar leads the cheese type segment with a 26.43% share in 2026, supported by its established consumer familiarity and ability to retain a distinctive flavor through smoking. Its versatility across retail and foodservice applications supports its use in snacks, sandwiches, burgers, and prepared dishes. Smoked mozzarella benefits from demand for cheese-based meals, particularly pizza, while smoked parmesan maintains a premium position in applications emphasizing distinctive flavor. Other varieties, including gouda, havarti, and provolone, provide opportunities for product differentiation through varied flavor profiles and smoking methods. This combination of familiarity and culinary versatility reinforces smoked cheddar's leading position within the segment.
Smoked cream cheese is the fastest-growing cheese type, projected to expand at a 7.12% compound annual growth rate (CAGR) from 2027 to 2032, driven by its adaptability across retail and foodservice applications. Its smooth texture and spreadability support use in dips, sauces, bagel spreads, and bakery fillings, while its distinctive smoky flavor creates opportunities for differentiated snack and meal offerings. Foodservice adoption can complement retail demand by extending usage across restaurant menus and prepared foods. Product innovation in flavored cream cheese and convenient formats further supports its potential across varied eating occasions. Together, these applications position smoked cream cheese for growth as consumers and foodservice operators seek versatile products with distinctive flavor profiles.
Naturally smoked cheese leads the smoking type segment with a 64.13% share in 2026, supported by consumer interest in traditional smoking methods and authentic smoky flavor profiles. Direct exposure to smoke allows manufacturers to develop distinctive sensory characteristics, including variations in aroma, flavor intensity, and appearance. Consumer perceptions of traditional smoking methods also support the positioning of naturally smoked varieties within specialty cheese offerings. These products can cater to consumers seeking distinctive flavors and established cheese-making techniques across retail and foodservice applications. Continued emphasis on flavor consistency and controlled smoking processes further supports the segment's leading position.
Processed smoked cheese is the fastest-growing smoking type, projected to expand at a 6.54% compound annual growth rate (CAGR) from 2027 to 2032, driven by demand for consistent flavor, product uniformity, and manufacturing efficiency. Processing techniques allow producers to incorporate smoky flavor into cheese products while maintaining greater control over formulation and product characteristics. These attributes support applications in prepared foods, sandwiches, sauces, and other products requiring consistent performance. Processed varieties can also provide manufacturers with flexibility in developing different formats and flavor intensities to meet varied application requirements. Ongoing improvements in processing technology and formulation are expected to support further product development across the segment.
Complete Report Scope:
- By Cheese Type
- Smoked Cheddar
- Smoked Mozzarella
- Smoked Parmesan
- Smoked Cream Cheese
- Other Smoked Cheese Types
- By Smoking Type
- Naturally Smoked Cheese
- Processed Smoked Cheese
- By Milk Source
- Cow Milk
- Goat Milk
- Sheep Milk
- Other Milk Sources
- By Format
- Blocks/Wheels
- Slices
- Cubes
- Spreads
- Other Formats
- By Distribution Channel
- On-trade
- Foodservice outlets/restaurants
- Hotels/catering establishments
- Other on-trade outlets
- Off-trade
- Supermarkets/Hypermarkets
- Specialty Stores
- Convenience Stores
- Online Retail
- Wholesalers/Other Channels
- On-trade
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Netherlands
- Poland
- Belgium
- Sweden
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Indonesia
- South Korea
- Thailand
- Singapore
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Chile
- Peru
- Rest of South America
- Middle East and Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
- Nigeria
- Egypt
- Morocco
- Turkey
- Rest of Middle East and Africa
- North America
Geography Analysis
Europe holds the largest share of the smoked cheese market at 34.16% in 2026, supported by established cheese production infrastructure and the longstanding presence of specialty cheese varieties. Germany, France, the Netherlands, and Poland contribute to the region's cheese production base, while traditional varieties such as Rauchkase reflect the integration of smoked cheese into regional food cultures. Established retail and foodservice channels provide opportunities for smoked cheese across household consumption, restaurant menus, and specialty food applications. Product innovation and interest in distinctive flavors further support the category's presence across European markets. Food safety requirements and evolving regulations on smoke flavourings also encourage producers to maintain controlled processing methods and appropriate product documentation.
Asia-Pacific is the fastest-growing region, projected to expand at a compound annual growth rate (CAGR) of 6.93% from 2027 to 2032, supported by expanding cheese consumption and growing use of cheese in foodservice and prepared foods. China's developing cheese market provides opportunities for smoked varieties in quick-service restaurants, bakery products, and other prepared applications. In Thailand, demand for imported cheese and specialty products creates opportunities for differentiated varieties, including smoked cheese, in urban retail and foodservice settings. South Korea's established cheese import market also provides a foundation for broader product adoption. Growing familiarity with cheese-based meals and demand for varied flavors are creating opportunities for smoked cheese producers across the region.
North America represents another important market, supported by demand for specialty cheese and its established use in restaurant menus and prepared foods. The United States provides opportunities for smoked cheese across retail and foodservice applications, including burgers, sandwiches, pizzas, and specialty dishes, while Mexico's expanding pizza market creates potential for smoked mozzarella in foodservice. Canada also offers opportunities for specialty smoked cheese varieties through established cheese distribution channels. In South America, Brazil, Argentina, Colombia, and Chile present opportunities as smoked cheese gains exposure through urban foodservice and specialty food applications. Meanwhile, the Middle East and Africa market is supported by premium hospitality and quick-service restaurant demand in countries such as the United Arab Emirates, Saudi Arabia, and South Africa, with further opportunities for gradual adoption in other regional markets.
- Groupe Lactalis SA
- Saputo Inc.
- Arla Foods amba
- Bel Group
- Tillamook County Creamery Association
- FrieslandCampina NV
- Fonterra Co-operative Group Limited
- Savencia
- Emmi Group
- Hochland SE
- Belton Farm
- Ornua Co-operative Limited
- Cabot Creamery Cooperative
- Sargento Foods Incorporated
- Hilmar Cheese Company, Inc.
- Leprino Foods Company
- Carr Valley Cheese Company
- Dewlay Cheesemakers
- Joseph Heler Ltd.
- Beehive Cheese Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing consumption of cheese and demand for specialty varieties
- 4.2.2 Expansion of gourmet foodservice and restaurant applications
- 4.2.3 Growing demand for natural, protein-rich cheese products
- 4.2.4 Innovation in smoking techniques and smoked cheese product development
- 4.2.5 Demand for convenient, ready-to-serve cheese formats
- 4.2.6 Growing importance of cheese provenance and traditional production methods
- 4.3 Market Restraints
- 4.3.1 Food safety risks and contaminant control in smoked cheese
- 4.3.2 High production costs and refrigeration requirements
- 4.3.3 Regulatory compliance for smoke flavourings and smoking methods
- 4.3.4 Maintaining consistent smoking processes and product quality
- 4.4 Consumer Behaviour Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Bargaining Power of Buyers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE AND VOLUME)
- 5.1 By Cheese Type
- 5.1.1 Smoked Cheddar
- 5.1.2 Smoked Mozzarella
- 5.1.3 Smoked Parmesan
- 5.1.4 Smoked Cream Cheese
- 5.1.5 Other Smoked Cheese Types
- 5.2 By Smoking Type
- 5.2.1 Naturally Smoked Cheese
- 5.2.2 Processed Smoked Cheese
- 5.3 By Milk Source
- 5.3.1 Cow Milk
- 5.3.2 Goat Milk
- 5.3.3 Sheep Milk
- 5.3.4 Other Milk Sources
- 5.4 By Format
- 5.4.1 Blocks/Wheels
- 5.4.2 Slices
- 5.4.3 Cubes
- 5.4.4 Spreads
- 5.4.5 Other Formats
- 5.5 By Distribution Channel
- 5.5.1 On-trade
- 5.5.1.1 Foodservice outlets/restaurants
- 5.5.1.2 Hotels/catering establishments
- 5.5.1.3 Other on-trade outlets
- 5.5.2 Off-trade
- 5.5.2.1 Supermarkets/Hypermarkets
- 5.5.2.2 Specialty Stores
- 5.5.2.3 Convenience Stores
- 5.5.2.4 Online Retail
- 5.5.2.5 Wholesalers/Other Channels
- 5.5.1 On-trade
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.1.4 Rest of North America
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 Italy
- 5.6.2.4 France
- 5.6.2.5 Spain
- 5.6.2.6 Netherlands
- 5.6.2.7 Poland
- 5.6.2.8 Belgium
- 5.6.2.9 Sweden
- 5.6.2.10 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 Australia
- 5.6.3.5 Indonesia
- 5.6.3.6 South Korea
- 5.6.3.7 Thailand
- 5.6.3.8 Singapore
- 5.6.3.9 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Argentina
- 5.6.4.3 Colombia
- 5.6.4.4 Chile
- 5.6.4.5 Peru
- 5.6.4.6 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 South Africa
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 United Arab Emirates
- 5.6.5.4 Nigeria
- 5.6.5.5 Egypt
- 5.6.5.6 Morocco
- 5.6.5.7 Turkey
- 5.6.5.8 Rest of Middle East and Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Company Highlights, Core Segments, Financials (if available), Strategic Information, Market Share Analysis for key companies, Products, and Recent Developments)
- 6.4.1 Groupe Lactalis SA
- 6.4.2 Saputo Inc.
- 6.4.3 Arla Foods amba
- 6.4.4 Bel Group
- 6.4.5 Tillamook County Creamery Association
- 6.4.6 FrieslandCampina NV
- 6.4.7 Fonterra Co-operative Group Limited
- 6.4.8 Savencia
- 6.4.9 Emmi Group
- 6.4.10 Hochland SE
- 6.4.11 Belton Farm
- 6.4.12 Ornua Co-operative Limited
- 6.4.13 Cabot Creamery Cooperative
- 6.4.14 Sargento Foods Incorporated
- 6.4.15 Hilmar Cheese Company, Inc.
- 6.4.16 Leprino Foods Company
- 6.4.17 Carr Valley Cheese Company
- 6.4.18 Dewlay Cheesemakers
- 6.4.19 Joseph Heler Ltd.
- 6.4.20 Beehive Cheese Company
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK

