PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187340

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187340
India Metal Fabrication - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the India metal fabrication market size is expected to increase from USD 8.51 billion in 2026 to USD 9.05 billion in 2027 and reach USD 12.54 billion by 2032, growing at a CAGR of 6.74% over 2027-2032.
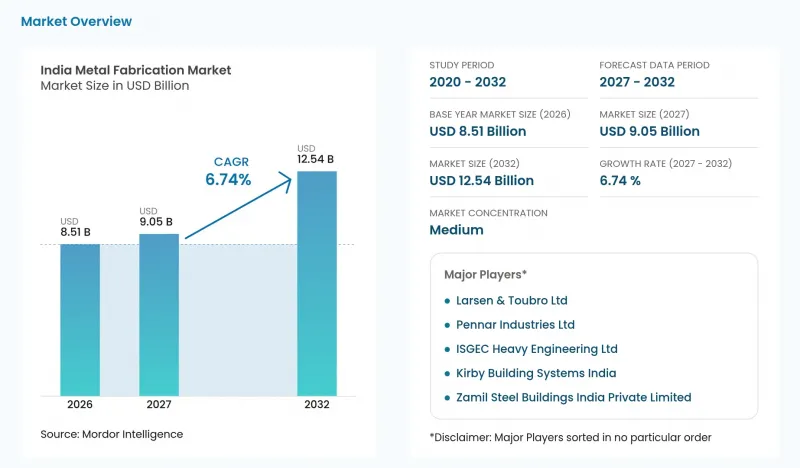
This report is segmented by Service Type (Machining, Welding, and more), Material (Carbon Steel, Stainless & Alloy Steel, and more), End-User Industry (Construction & Infrastructure, Automotive & Auto Components, and more), and Geography (Western India, Southern India, and more). The market forecasts are provided in terms of value (USD), based on availability.
India Metal Fabrication Market Trends and Insights
Infrastructure super-cycle (Gati Shakti, NIP) unleashing structural-steel demand
Infrastructure expansion increases fabrication demand when sanctioned transport projects become orders for identifiable structures. Indian Railways sanctioned 100 projects under PM Gati Shakti in FY 2025-26, compared with 64 in FY 2024-25, and expected them to stimulate steel and cement demand. In February 2025, National High Speed Rail Corporation Limited launched a 100-meter, 1,432-metric-ton steel bridge fabricated at a Bhuj workshop for the Mumbai-Ahmedabad Bullet Train Project. This was the sixth of 17 steel bridges planned in Gujarat. The approvals establish a prospective pipeline, while the completed bridge shows how infrastructure construction translates into a discrete workshop-produced assembly. For bridge fabricators, the larger approvals pipeline creates potential orders, but workshop revenue depends on which sanctioned projects release structural work.
Renewable-energy OEM localization (wind towers, solar MMS)
Local component eligibility gives wind-tower fabricators a route into turbine procurement that additional production capacity alone cannot secure. The July 2025 amendment from the Ministry of New and Renewable Energy (MNRE) required listed wind turbines to use listed towers and other major components, subject to specified project and new-model exemptions. The amendment excluded already-bid projects and captive, open-access, commercial and industrial, or third-party-sale projects commissioned within 18 months of issuance. New manufacturers or models received an exemption covering 800 MW for two years to promote innovative technologies and performance efficiencies unavailable indigenously. These transition provisions stagger the commercial opening, so qualified tower suppliers must distinguish covered projects from exempt wind activity. The resulting advantage belongs to fabricators able to enter the approved component channel, rather than every workshop capable of producing steel structures.
Imported coking-coal cost volatility
Imported coal volatility creates an upstream pricing risk for steel-intensive fabrication contracts. India's Ministry of Steel identifies limited domestic low-ash coking-coal supply relative to demand and a major steelmaking cost burden for integrated producers. Its Australian FOB benchmark moved from around USD 175 per metric ton in March 2025 to around USD 246 in February 2026, then USD 239 in May 2026. This movement makes the timing of steel supply commitments commercially consequential when input repricing reaches downstream suppliers. A fabricator holding a fixed selling price would have less room to absorb an increase in its material bill. Fixed-price structural-steel commitments made near the March 2025 benchmark low would face margin pressure from any later steel-cost pass-through, even where project demand held.
Other drivers and restraints analyzed in the detailed report include:
- Defense offsets accelerating precision fabrication
- Data-center boom driving heavy modular fabrication
- MSME power-supply bottlenecks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Machining accounted for a 34.22% share of the India metal fabrication market size in 2026. Aequs reported annual Aerospace-segment machining capacity of 1.83 million hours for FY 2026, annualized from year-to-date performance through Q3 FY 2026. That compared with 1.72 million hours in FY 2025, an increase of about 6% in annualized capacity. Aequs also reported 206 computer numerical control (CNC) machines as of December 2025. For suppliers pursuing comparably scaled aerospace work, the combination of added annual hours and a large CNC fleet makes equipment commitment a central competitive requirement.
Welding is forecast to be the fastest-growing segment, with a 7.72% CAGR over 2027-2032. In July 2025, RIJ Engineering India contracted with Fives Cinetic for an additional CO2 laser-welding machine at Pune for automotive and agricultural transmission gears. The announcement scheduled commissioning for fall 2025 and expected a 25% increase in RIJ's overall production capacity. The order followed 3 earlier Fives Cinetic laser-welding machines at RIJ, making it a repeat investment in the process. For those component manufacturers, welding investment can expand a complete gear-production line as demand for transmission gears increases.
Complete Report Scope:
- By Service Type
- Cutting
- Forming / Bending
- Welding
- Machining
- Punching / Stamping
- Finishing / Surface Treatment
- Others (Assembling, etc.)
- By Material
- Carbon Steel
- Stainless & Alloy Steel
- Aluminum
- Others (Copper, Brass, Specialty Alloys, Sheet Metal (CRCA, GI, HR))
- By End-User Industry
- Construction & Infrastructure
- Automotive & Auto Components
- Railways & Metro
- Power & Utilities
- Aerospace & Defense
- Oil, Gas & Refinery
- Marine and Shipbuilding
- Manufacturing - Heavy Machinery & Consumer Durables
- Others (Job shops, Agricultural Equipment, Electricals, Consumer Durables, etc)
- By Geography
- Western India (Maharashtra, Gujarat, Goa)
- Southern India (Tamil Nadu, Karnataka, Telangana, Andhra Pradesh, Kerala)
- Northern India (Delhi NCR, Haryana, Punjab, Uttar Pradesh, Uttarakhand, Himachal Pradesh, Rajasthan)
- Eastern India (West Bengal, Jharkhand, Odisha, Bihar, Chhattisgarh)
- Central India (Madhya Pradesh, parts of Chhattisgarh)
List of Companies Covered in this Report:
- Larsen & Toubro Ltd
- Kirby Building Systems India
- Zamil Steel Buildings India Private Limited
- ISGEC Heavy Engineering Ltd
- Pennar Industries Ltd
- Salasar Techno Engineering Ltd
- JSW Severfield Structures Ltd
- Godrej Process Equipment
- Diamond Engineering (India) Pvt Ltd
- TEMA India Ltd
- Novatech Projects (India) Pvt Ltd
- Karamtara Engineering Ltd
- Bharat Heavy Electricals Ltd (Fabrication Div.)
- Tata Projects Ltd
- Welspun Corp Ltd
- Hindustan Dorr-Oliver Ltd
- Jindal Stainless - Fabrication Unit
- Bharat Forge Ltd (Fabrication Business)
- Essar Heavy Engineering Services
- Technofab Engineering Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Infrastructure super-cycle (Gati Shakti, NIP) unleashing structural-steel demand
- 4.2.2 Renewable-energy OEM localization (wind towers, solar MMS)
- 4.2.3 Defense offsets accelerating precision fabrication
- 4.2.4 Data-center boom driving heavy modular fabrication
- 4.2.5 EV & battery-pack light-weighting creating aluminum sub-assembly demand
- 4.2.6 Proposed green-steel procurement mandates (public tenders)
- 4.3 Market Restraints
- 4.3.1 Imported coking-coal cost volatility
- 4.3.2 MSME power-supply bottlenecks
- 4.3.3 Fragmented quality-assurance ecosystem limits export readiness
- 4.3.4 CBAM-linked carbon-compliance cost for aluminum/steel exports
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact of Recent Global Disruptions on the India Metal Fabrication Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Cutting
- 5.1.2 Forming / Bending
- 5.1.3 Welding
- 5.1.4 Machining
- 5.1.5 Punching / Stamping
- 5.1.6 Finishing / Surface Treatment
- 5.1.7 Others (Assembling, etc.)
- 5.2 By Material
- 5.2.1 Carbon Steel
- 5.2.2 Stainless & Alloy Steel
- 5.2.3 Aluminum
- 5.2.4 Others (Copper, Brass, Specialty Alloys, Sheet Metal (CRCA, GI, HR))
- 5.3 By End-User Industry
- 5.3.1 Construction & Infrastructure
- 5.3.2 Automotive & Auto Components
- 5.3.3 Railways & Metro
- 5.3.4 Power & Utilities
- 5.3.5 Aerospace & Defense
- 5.3.6 Oil, Gas & Refinery
- 5.3.7 Marine and Shipbuilding
- 5.3.8 Manufacturing - Heavy Machinery & Consumer Durables
- 5.3.9 Others (Job shops, Agricultural Equipment, Electricals, Consumer Durables, etc)
- 5.4 By Geography
- 5.4.1 Western India (Maharashtra, Gujarat, Goa)
- 5.4.2 Southern India (Tamil Nadu, Karnataka, Telangana, Andhra Pradesh, Kerala)
- 5.4.3 Northern India (Delhi NCR, Haryana, Punjab, Uttar Pradesh, Uttarakhand, Himachal Pradesh, Rajasthan)
- 5.4.4 Eastern India (West Bengal, Jharkhand, Odisha, Bihar, Chhattisgarh)
- 5.4.5 Central India (Madhya Pradesh, parts of Chhattisgarh)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Larsen & Toubro Ltd
- 6.4.2 Kirby Building Systems India
- 6.4.3 Zamil Steel Buildings India Private Limited
- 6.4.4 ISGEC Heavy Engineering Ltd
- 6.4.5 Pennar Industries Ltd
- 6.4.6 Salasar Techno Engineering Ltd
- 6.4.7 JSW Severfield Structures Ltd
- 6.4.8 Godrej Process Equipment
- 6.4.9 Diamond Engineering (India) Pvt Ltd
- 6.4.10 TEMA India Ltd
- 6.4.11 Novatech Projects (India) Pvt Ltd
- 6.4.12 Karamtara Engineering Ltd
- 6.4.13 Bharat Heavy Electricals Ltd (Fabrication Div.)
- 6.4.14 Tata Projects Ltd
- 6.4.15 Welspun Corp Ltd
- 6.4.16 Hindustan Dorr-Oliver Ltd
- 6.4.17 Jindal Stainless - Fabrication Unit
- 6.4.18 Bharat Forge Ltd (Fabrication Business)
- 6.4.19 Essar Heavy Engineering Services
- 6.4.20 Technofab Engineering Ltd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

