PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187401

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187401
India Refrigerator - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the India refrigerator market size is expected to increase from USD 5.9 billion in 2026 to USD 6.46 billion in 2027 and reach USD 9.99 billion by 2032, growing at a CAGR of 9.12% over 2027-2032.
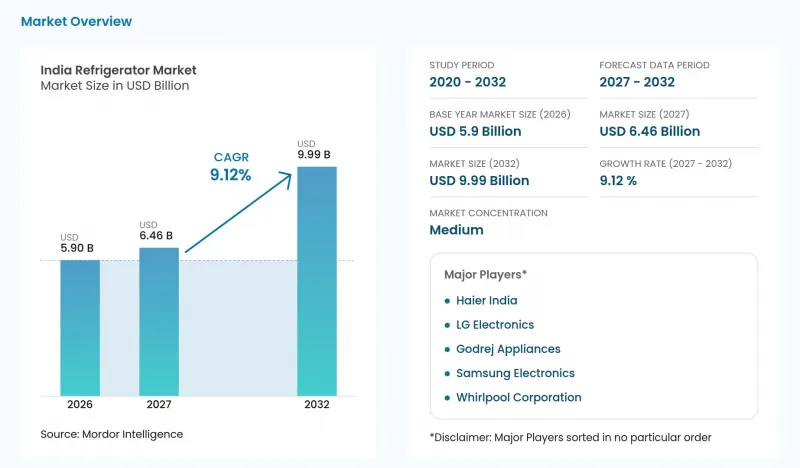
This report is segmented by Product (Double-Door Refrigerator and more), Capacity (200-500 Liters, Less Than 15 cu. Feet, and more), Technology (Conventional and more), Distribution Channel (Multi-brand Stores and more), and Geography (North India and more). The market forecasts are provided in terms of value (USD), based on availability.
India Refrigerator Market Trends and Insights
Rising Disposable Incomes and Enhanced Electrification in Tier-2/3 Towns
First-time refrigerator demand depends on combining the ability to acquire an appliance with enough electricity to use it regularly. The Ministry of Statistics and Programme Implementation's provisional estimates put growth in India's per-capita gross national disposable income at current prices at 8.1% in FY2025-26. That nominal income measure provides a national demand-side premise for suppliers considering a broader refrigerator customer base. The Ministry of Power reported average daily electricity supply of 23.4 hours in urban India in FY2024-25. For smaller-town suppliers, an affordable refrigerator offering and dependable operation are complementary parts of the expansion case. An electrical connection alone cannot deliver the intended cooling benefit, so the commercial value of electrification depends on usable supply after the appliance enters the home.
Support From PLI Schemes and 'Make in India' for Compressor Manufacturing
Local compressor manufacture can support refrigerator demand by widening the production options available to domestic appliance assemblers. Nidec Global Appliance reported that its Embraco compressor factory in Chhatrapati Sambhaji Nagar had completed its main building structure and was moving into mechanical, electrical and plumbing work. Its 2026 construction update expected production in Q4 2026 and sales in early 2027. That committed construction provides a route to additional refrigeration-component supply, linking domestic manufacturing development to the ability to offer finished appliances. With production expected in Q4 2026 and sales in early 2027, the plant would add Indian refrigeration-compressor supply from 2027, which is when any effect on appliance availability can begin.
Power-Voltage Instability Continues to Affect Semi-Urban Grids
Unstable voltage can weaken the case for a refrigerator when households cannot depend on consistent appliance operation. In May 2026, Ghazipur consumers across urban and rural areas reported low voltage and tripping that left coolers and other electrical appliances working poorly as heat increased network load. This operating burden matters to refrigeration because the value of purchasing additional cooling capability depends on being able to use it. Larger storage capacity does not resolve an interruption in the electricity supplied to a home, leaving the operating environment separate from the appliance's specifications. The resulting uncertainty about usable refrigeration can delay an upgrade even where a household wants additional storage.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of Inverter Technology and AI-Enabled Compressors
- Increased Demand for Premium Multi-Door and Designer Appliances
- Rural Regions Experience Significant After-Sales Service Deficiencies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Double-door refrigerators accounted for a 39.68% share of the India refrigerator market size in 2026. LG Electronics India reported by May 22, 2026, that it had begun production of a 674-liter double-door refrigerator at its Pune plant in Maharashtra. A locally produced model of that capacity can serve buyers seeking additional storage while using a double-door configuration. For manufacturers, this supports a way to develop higher-capacity offerings inside the largest segment, making refrigerator storage capacity a separate design choice from the number of doors.
Side-by-side refrigerators are the fastest-growing segment, with a forecast CAGR of 11.16% over 2027-2032. By May 22, 2026, LG Electronics India said it had begun Pune production of a 790-liter side-by-side refrigerator, a size no other producer was then making in India. For buyers seeking that size from an Indian producer, LG's reported position concentrated the domestic sourcing choice in its Pune line. Rivals seeking the same domestic manufacturing proposition would need to add that specific size, rather than merely offer another side-by-side model.
Refrigerators with capacities of 200-500 liters held the largest segment share at 72.33% in 2026. For a household considering this range, the decision is how much capacity to assign to its normal refrigerated and frozen food needs. A supplier can address that decision through different internal allocations within the same capacity band, rather than treating a larger cabinet as the only route to a more useful appliance. This makes compartment design a way to compete for the largest segment's buyers without requiring them to move above 500 liters.
Refrigerators above 500 liters are the fastest-growing segment, with a forecast CAGR of 12.2% over 2027-2032. On June 18, 2026, LG Electronics India launched a French Door refrigerator range in India with capacities from 574 liters to 610 liters. The range illustrates how a supplier can offer different storage volumes within this band, giving households a choice of capacity within one refrigerator family. For manufacturers, that approach makes the spacing between model sizes a portfolio decision, with additional volume offered in steps rather than through a single oversized specification.
Complete Report Scope:
- By Product
- Single-Door Refrigerator
- Double-Door Refrigerator
- Top Freezer
- Bottom Freezer
- Side-By-Side Door Refrigerator
- French-Door Refrigerator
- Other Refrigerators
- By Capacity
- Less than 200 Liters
- 200-500 Liters
- Greater than 500 Liters
- By Capacity
- Less Than 15 cu. Feet
- More Than 15 cu. Feet
- By Technology
- Conventional
- Smart/IoT-Enabled
- By Distribution Channel
- Multi-brand Stores
- Exclusive Brand Outlets
- Online
- Other Distribution Channels
- By Geography
- North India
- South India
- West India
- East India
List of Companies Covered in this Report:
- Samsung Electronics
- LG Electronics
- Whirlpool Corporation
- Godrej Appliances
- Haier India
- Panasonic Corporation
- Voltas Beko
- Arcelik Hitachi Home Appliances
- Videocon Industries
- BSH Hausgerate GmbH
- Blue Star
- IFB Appliances
- Hisense
- Kelvinator India
- Onida (Onida Electronics)
- Lloyd (Havells)
- Carrier-Midea
- Croma (Infiniti Retail)
- MarQ (Flipkart Private Label)
- Voltas Beko Home Appliances Pvt. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Disposable Incomes and Enhanced Electrification in Tier-2/3 Towns
- 4.2.2 Support From PLI Schemes and 'Make in India' for Compressor Manufacturing
- 4.2.3 Adoption of Inverter Technology and AI-Enabled Compressors
- 4.2.4 Increased Demand for Premium Multi-Door and Designer Appliances
- 4.2.5 Focus on Energy-Efficient and BEE-Certified Products
- 4.2.6 Expansion of Organized Retail and E-Commerce Networks
- 4.3 Market Restraints
- 4.3.1 Power-Voltage Instability Continues to Affect Semi-Urban Grids
- 4.3.2 Rural Regions Experience Significant After-Sales Service Deficiencies
- 4.3.3 Smart Metering Infrastructure Adoption Remains Incomplete
- 4.3.4 Seasonal Agricultural Loads Drive High Dependency in Certain Areas
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Insights Into The Latest Trends And Innovations In The Market
- 4.9 Insights On Recent Developments (New Product Launches, Strategic Initiatives, Investments, Partnerships, JVs, Expansion, M&As, Etc.)
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product
- 5.1.1 Single-Door Refrigerator
- 5.1.2 Double-Door Refrigerator
- 5.1.2.1 Top Freezer
- 5.1.2.2 Bottom Freezer
- 5.1.3 Side-By-Side Door Refrigerator
- 5.1.4 French-Door Refrigerator
- 5.1.5 Other Refrigerators
- 5.2 By Capacity
- 5.2.1 Less than 200 Liters
- 5.2.2 200-500 Liters
- 5.2.3 Greater than 500 Liters
- 5.3 By Capacity
- 5.3.1 Less Than 15 cu. Feet
- 5.3.2 More Than 15 cu. Feet
- 5.4 By Technology
- 5.4.1 Conventional
- 5.4.2 Smart/IoT-Enabled
- 5.5 By Distribution Channel
- 5.5.1 Multi-brand Stores
- 5.5.2 Exclusive Brand Outlets
- 5.5.3 Online
- 5.5.4 Other Distribution Channels
- 5.6 By Geography
- 5.6.1 North India
- 5.6.2 South India
- 5.6.3 West India
- 5.6.4 East India
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Samsung Electronics
- 6.4.2 LG Electronics
- 6.4.3 Whirlpool Corporation
- 6.4.4 Godrej Appliances
- 6.4.5 Haier India
- 6.4.6 Panasonic Corporation
- 6.4.7 Voltas Beko
- 6.4.8 Arcelik Hitachi Home Appliances
- 6.4.9 Videocon Industries
- 6.4.10 BSH Hausgerate GmbH
- 6.4.11 Blue Star
- 6.4.12 IFB Appliances
- 6.4.13 Hisense
- 6.4.14 Kelvinator India
- 6.4.15 Onida (Onida Electronics)
- 6.4.16 Lloyd (Havells)
- 6.4.17 Carrier-Midea
- 6.4.18 Croma (Infiniti Retail)
- 6.4.19 MarQ (Flipkart Private Label)
- 6.4.20 Voltas Beko Home Appliances Pvt. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

