PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187725

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187725
India Warehouse - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
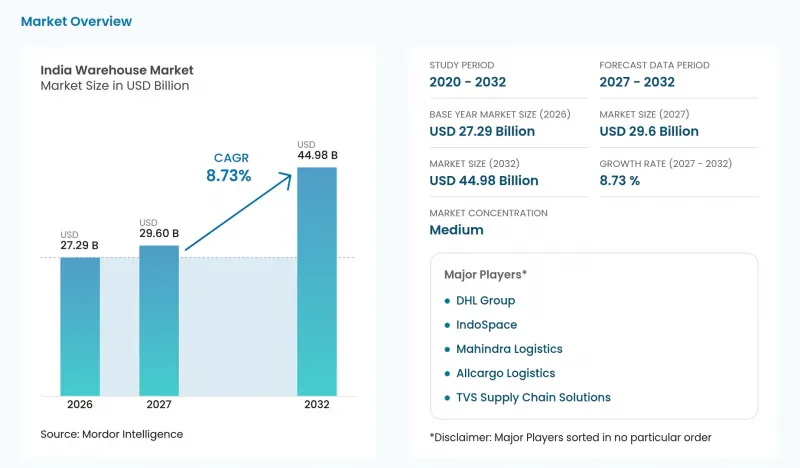
According to Mordor Intelligence, the India warehouse market size is expected to increase from USD 27.29 billion in 2026 to USD 29.6 billion in 2027 and reach USD 44.98 billion by 2032, growing at a CAGR of 8.73% over 2027-2032.
This report is segmented by Segmentation by Warehouse Type (General Warehousing and Storage and more), Segmentation by Grade (Grade-B and more), Segmentation by End-User Industry (E-commerce and Retail and more), and Geography (West India and more). The market forecasts are provided in terms of value (USD), based on availability.
India Warehouse Market Trends and Insights
Implementation of National Logistics Policy (NLP-2022)
Common warehouse standards can increase the usefulness of rented space by making facilities easier to compare across a distribution network. In March 2025, India's Asian Development Bank-funded Strengthening Multimodal and Integrated Logistics Ecosystem program included planned standardization of warehousing and other logistics assets to support National Logistics Policy implementation. The program intended that standardization to strengthen supply chains and encourage private investment. For occupiers considering several locations, more comparable specifications could reduce the need to evaluate each building as an entirely separate operating proposition. Its demand contribution therefore depends on translating the policy framework into facilities that tenants can substitute within their networks.
Commissioning of Dedicated Freight Corridors and Development of Multi-Modal Logistics Parks
Freight infrastructure can concentrate storage demand where goods transfer between long-distance movement and local distribution, giving warehouse location greater commercial significance. In March 2026, India's Dedicated Freight Corridors had around 2,800 kilometers completed and about 480 freight trains operating daily. On April 1, 2026, 6 of the country's 15 prioritized multimodal logistics park locations were under implementation. Operating corridors provide a freight base for nearby storage, while the park pipeline could create additional places to consolidate goods before their next journey. The opportunity for warehouse operators is to secure occupancy linked to those transfer points, with lease timing matched to each park's actual readiness for customers.
Lengthy Environmental-Impact & Fire-Safety Clearance Timelines
Forest-land encroachment can make remediation a prerequisite to securing access approval for a proposed warehouse. On May 8, 2026, the Advisory Committee of India's Ministry of Environment, Forest and Climate Change recommended in-principle (Stage-I) approval to divert 0.0058 hectares of forest land for access to Freight Systems India Pvt. Ltd.'s proposed non-agro produce warehouse in Jatauli, Haryana. The minutes recorded 0.018 hectares encroached by the company against the 0.0058 hectares sought for diversion. Haryana had to ensure the excess area was freed from encroachment and submit supporting documents with Stage-I compliance. The conditions required environmental and legal compliance and verification of compensatory afforestation before final clearance. For this project, access depended on curing the land-use violation, leaving compliance work between the recommendation and final clearance.
Other drivers and restraints analyzed in the detailed report include:
- Production-Linked Incentive (PLI) Schemes Boosting Domestic Manufacturing Inventory Needs
- Omni-Channel Retail's Push for Decentralized Micro-Fulfillment Centers
- Intermittent Grid Power Jeopardizing Automation Uptime, Raising Backup CAPEX
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
General warehousing and storage accounted for a 58.4% share of the India warehouse market size in 2026, making it the largest segment. On February 1, 2026, Food Corporation of India (FCI) had 47.07 million metric tons of covered Central Pool foodgrain capacity, including 32.35 million hired and 14.72 million owned. State agencies had a further 38.19 million metric tons of covered capacity for Central Pool foodgrain stock on the same date. A March 2026 government reply described FCI hiring storage from Central and State Warehousing Corporations, state agencies and private parties under the Private Warehousing Scheme. Private providers can therefore compete for a defined institutional foodgrain-storage requirement alongside agency-owned capacity.
Refrigerated warehousing and storage is forecast to be the fastest-growing segment, with a CAGR of 13.12% over 2027-2032. On May 13, 2025, DP World launched a 110,000-square-foot Grade-A cold-chain warehouse in Taloja, Navi Mumbai, with 11,000 pallet positions and multiple temperature zones. India's cold-storage capacity totaled 40.22 million metric tons across 8,815 facilities by June 2025, with about three-quarters used for potatoes. The contrast between that crop-heavy capacity base and a multi-temperature commercial facility points to an opening for storage configured for varied temperature-sensitive cargo. Operators can consequently compete on the combination of usable temperature zones and pallet capacity, giving customers a more specific service than refrigerated floor area alone.
Complete Report Scope:
- By Segmentation by Warehouse Type (Value)
- General Warehousing and Storage
- Refrigerated Warehousing and Storage
- By Segmentation by Grade (Value)
- Grade-A
- Grade-B
- Grade-C & Unorganized
- By Segmentation by End-User Industry (Value)
- E-commerce and Retail
- Food and Beverage
- Pharma and Healthcare
- Automotive
- Manufacturing and Engineering Goods
- Others
- By Geography
- North India
- Delhi-NCR
- Punjab
- Haryana
- Others
- South India
- Karnataka
- Tamil Nadu
- Telangana
- West India
- Maharashtra
- Gujarat
- East India
- West Bengal
- Odisha
- Central India
- Madhya Pradesh
- Chhattisgarh
- North India
List of Companies Covered in this Report:
- Mahindra Logistics
- Snowman Logistics
- IndoSpace
- DHL Group
- VRL Logistics Limited
- TVS Supply Chain Solutions
- Allcargo Logistics
- TCI Supply Chain Solutions
- Delhivery
- Safexpress
- LO-GOI Group
- Godamwale Logistic
- Warehouzez
- Ascendas Firstspace
- StarAgri Warehousing
- Blue Dart Express
- ColdEx Logistics
- Kintetsu World Express (India) Pvt. Ltd.
- XpressBees
- Apollo LogiSolutions
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Implementation of National Logistics Policy (NLP-2022)
- 4.2.2 Commissioning of Dedicated Freight Corridors and Development of Multi-Modal Logistics Parks
- 4.2.3 Production-Linked Incentive (PLI) Schemes Boosting Domestic Manufacturing Inventory Needs
- 4.2.4 Omni-Channel Retail's Push for Decentralized Micro-Fulfillment Centers
- 4.2.5 Surge in ESG-Compliant 'Green Warehouse' Certifications Attracting Premium Tenants
- 4.2.6 Reverse-Logistics & Returns-Processing Space Demand from Rising E-Commerce Returns
- 4.3 Market Restraints
- 4.3.1 Lengthy Environmental-Impact & Fire-Safety Clearance Timelines
- 4.3.2 Intermittent Grid Power Jeopardizing Automation Uptime, Raising Backup CAPEX
- 4.3.3 Shortage of Skilled Warehouse Automation Technicians
- 4.3.4 Insurance Premiums Escalating Due to Warehouse Fire-Load & Climate Risk
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Segmentation by Warehouse Type (Value)
- 5.1.1 General Warehousing and Storage
- 5.1.2 Refrigerated Warehousing and Storage
- 5.2 By Segmentation by Grade (Value)
- 5.2.1 Grade-A
- 5.2.2 Grade-B
- 5.2.3 Grade-C & Unorganized
- 5.3 By Segmentation by End-User Industry (Value)
- 5.3.1 E-commerce and Retail
- 5.3.2 Food and Beverage
- 5.3.3 Pharma and Healthcare
- 5.3.4 Automotive
- 5.3.5 Manufacturing and Engineering Goods
- 5.3.6 Others
- 5.4 By Geography
- 5.4.1 North India
- 5.4.1.1 Delhi-NCR
- 5.4.1.2 Punjab
- 5.4.1.3 Haryana
- 5.4.1.4 Others
- 5.4.2 South India
- 5.4.2.1 Karnataka
- 5.4.2.2 Tamil Nadu
- 5.4.2.3 Telangana
- 5.4.3 West India
- 5.4.3.1 Maharashtra
- 5.4.3.2 Gujarat
- 5.4.4 East India
- 5.4.4.1 West Bengal
- 5.4.4.2 Odisha
- 5.4.5 Central India
- 5.4.5.1 Madhya Pradesh
- 5.4.5.2 Chhattisgarh
- 5.4.1 North India
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Mahindra Logistics
- 6.4.2 Snowman Logistics
- 6.4.3 IndoSpace
- 6.4.4 DHL Group
- 6.4.5 VRL Logistics Limited
- 6.4.6 TVS Supply Chain Solutions
- 6.4.7 Allcargo Logistics
- 6.4.8 TCI Supply Chain Solutions
- 6.4.9 Delhivery
- 6.4.10 Safexpress
- 6.4.11 LO-GOI Group
- 6.4.12 Godamwale Logistic
- 6.4.13 Warehouzez
- 6.4.14 Ascendas Firstspace
- 6.4.15 StarAgri Warehousing
- 6.4.16 Blue Dart Express
- 6.4.17 ColdEx Logistics
- 6.4.18 Kintetsu World Express (India) Pvt. Ltd.
- 6.4.19 XpressBees
- 6.4.20 Apollo LogiSolutions
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

