PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187791

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187791
India Semiconductor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the India semiconductor market size is expected to increase from USD 12.41 billion in 2026 to USD 13.28 billion in 2027 and reach USD 18.99 billion by 2032, growing at a CAGR of 7.41% over 2027-2032.
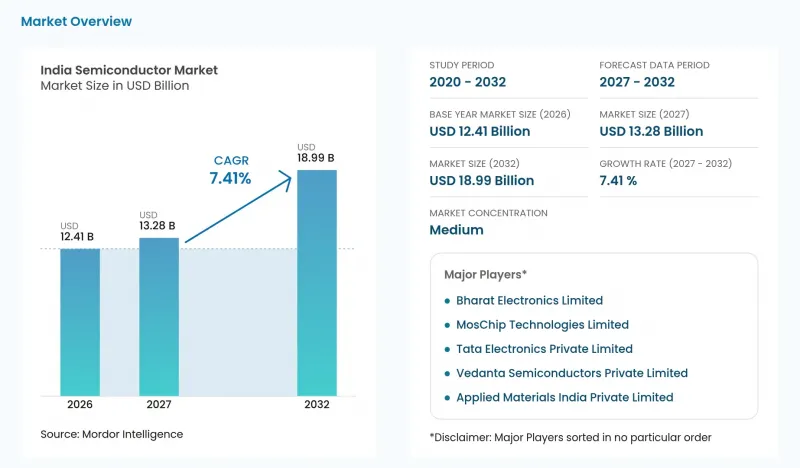
This report is segmented by Device Type (Integrated Circuits, Discrete Semiconductors, Optoelectronics, and Sensors and MEMS) and End-User Industry (Communication, Consumer Electronics, Automotive, Industrial, Computing and Data Storage, Data Center, Government, and Artificial Intelligence). The market forecasts are provided in terms of value (USD), based on availability.
India Semiconductor Market Trends and Insights
Government Incentive Schemes (PLI, DLI)
Government design support broadens the potential supplier base by backing semiconductor projects across several distinct domestic applications. By March 2026, the Design Linked Incentive Scheme had approved 24 chip and system-on-chip design projects for uses including surveillance, energy metering, satellite communications, and broadband. By August 2026, supported companies had achieved more than 30 chip design tape-outs across foundries. Application breadth makes the commercial opportunity wider than a single device program. Because tape-outs are design milestones, the incentive's effect on fabrication and packaging demand depends on how many supported designs reach volume manufacturing.
Rapid Electrification of Transport
Transport electrification extends semiconductor demand beyond vehicles into the charging equipment needed to support them. India sold 2.5 million electric vehicles in FY 2025-26, providing a substantial downstream base for this demand mechanism. In November 2025, Zenergize commissioned 9 silicon-carbide-based DC fast chargers rated at 60 kW each with charge-point operator Power Pod in Bengaluru. The equipment included Zenergize's own locally developed power modules, connecting charging infrastructure expansion with a specific power-electronics application. Charger makers that design their own power modules, as Zenergize does, create demand for silicon carbide power devices at the equipment level, separate from the chips inside vehicles.
Skill Shortage in Advanced-node Engineering
Specialized staffing can constrain the conversion of new fabrication facilities into dependable semiconductor supply. In August 2026, IEEE senior member Santhosh Sivasubramani identified trained personnel as a potential hurdle for India's advanced-node transition and new advanced facilities. NITI Aayog's May 2026 roadmap also identified shortages across fabrication, advanced packaging, and testing skills. Together, these constraints mean equipment investment must be matched by operating expertise before suppliers can expand production reliably. In July 2026, the government reported that India Semiconductor Mission had partnered with Lam Research on nanofabrication and process-engineering training. Developing the required operating expertise adds staffing costs and lead time to fabrication expansion.
Other drivers and restraints analyzed in the detailed report include:
- 5G Roll-out and BharatNet Fiber Expansion
- Data-Center and AI Workloads
- Limited Ultrapure Water and Power Infrastructure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Integrated circuits accounted for a 57.15% share of the India semiconductor market size in 2026 and are forecast to be the fastest-growing segment, with a CAGR of 7.7% over 2027-2032. On February 28, 2026, Micron presented Dell Technologies with its first shipment of made-in-India memory modules for laptops manufactured and sold in India. Because the first shipment went to a laptop maker assembling for the Indian market, Micron's Sanand memory-module output is tied to domestic PC production programs.
Process-node ambition alone does not define an integrated-circuit supplier's commercial reach. Analog, micro, logic, and memory create separate product choices, while technology nodes add another dimension to the manufacturing scope. Under the market definition, analog, micro, logic, and memory devices count once at the supplier's first sale into India, whether made locally or imported. A domestic fab or packaging line therefore adds to this segment's sales when its devices are sold to Indian buyers, while processing customer-owned material generates excluded service fees.
Complete Report Scope:
- By Device Type
- Discrete Semiconductors
- Diodes
- Transistors
- Power Transistors
- Rectifiers and Thyristors
- Other Discrete Devices
- Optoelectronics
- Light-Emitting Diodes (LEDs)
- Laser Diodes
- Image Sensors
- Optocouplers
- Other Optoelectronic Devices
- Sensors and MEMS
- Pressure Sensors
- Magnetic Field Sensors
- Actuators
- Acceleration and Yaw Rate Sensors
- Temperature and Other Sensors
- Integrated Circuits
- By Integrated Circuit Type
- Analog
- Micro
- Microprocessors (MPU)
- Microcontrollers (MCU)
- Digital Signal Processors
- Logic
- Memory
- By Technology Node (For Integrated Circuits)
- Less Than or Equal to 3nm
- 5 nm
- 7 nm
- 16 nm
- 28 nm
- Greater Than 28nm
- By Integrated Circuit Type
- Discrete Semiconductors
- By End-User Industry
- Automotive
- Communication (Wired and Wireless)
- Consumer Electronics
- Industrial
- Computing and Data Storage
- Data Center
- Artificial Intelligence
- Government (Aerospace and Defense)
List of Companies Covered in this Report:
- Tata Electronics Private Limited
- Vedanta Semiconductors Private Limited
- Bharat Electronics Limited
- MosChip Technologies Limited
- Applied Materials India Private Limited
- ASM Technologies Limited
- Suchi Semicon Private Limited
- NXP Semiconductors N.V.
- HCL Technologies Limited
- Infineon Technologies AG
- Renesas Electronics Corporation
- STMicroelectronics N.V.
- Powerchip Semiconductor Manufacturing Corporation
- Intel Corporation
- Samsung Electronics Co., Ltd.
- Qualcomm Incorporated
- Micron Technology, Inc.
- Texas Instruments Incorporated
- MediaTek Inc.
- Taiwan Semiconductor Manufacturing Company Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government Incentive Schemes (PLI, DLI)
- 4.2.2 Rapid Electrification of Transport
- 4.2.3 5G Roll-out and BharatNet Fiber Expansion
- 4.2.4 Data-Center and AI Workloads
- 4.2.5 Indigenous GaN/SiC Fabs
- 4.2.6 Trusted Defense-grade Fab Accreditation
- 4.3 Market Restraints
- 4.3.1 Skill Shortage in Advanced-node Engineering
- 4.3.2 Limited Ultrapure Water and Power Infrastructure
- 4.3.3 Fragmented OSAT Capacity
- 4.3.4 Land and Environmental Clearance Delays
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 SWOT Analysis (India IC Design D Fab D ATP)
- 4.9 Investment Analysis (CapEx Trends and Funding Flows)
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Device Type
- 5.1.1 Discrete Semiconductors
- 5.1.1.1 Diodes
- 5.1.1.2 Transistors
- 5.1.1.3 Power Transistors
- 5.1.1.4 Rectifiers and Thyristors
- 5.1.1.5 Other Discrete Devices
- 5.1.2 Optoelectronics
- 5.1.2.1 Light-Emitting Diodes (LEDs)
- 5.1.2.2 Laser Diodes
- 5.1.2.3 Image Sensors
- 5.1.2.4 Optocouplers
- 5.1.2.5 Other Optoelectronic Devices
- 5.1.3 Sensors and MEMS
- 5.1.3.1 Pressure Sensors
- 5.1.3.2 Magnetic Field Sensors
- 5.1.3.3 Actuators
- 5.1.3.4 Acceleration and Yaw Rate Sensors
- 5.1.3.5 Temperature and Other Sensors
- 5.1.4 Integrated Circuits
- 5.1.4.1 By Integrated Circuit Type
- 5.1.4.1.1 Analog
- 5.1.4.1.2 Micro
- 5.1.4.1.2.1 Microprocessors (MPU)
- 5.1.4.1.2.2 Microcontrollers (MCU)
- 5.1.4.1.2.3 Digital Signal Processors
- 5.1.4.1.3 Logic
- 5.1.4.1.4 Memory
- 5.1.4.2 By Technology Node (For Integrated Circuits)
- 5.1.4.2.1 Less Than or Equal to 3nm
- 5.1.4.2.2 5 nm
- 5.1.4.2.3 7 nm
- 5.1.4.2.4 16 nm
- 5.1.4.2.5 28 nm
- 5.1.4.2.6 Greater Than 28nm
- 5.1.4.1 By Integrated Circuit Type
- 5.1.1 Discrete Semiconductors
- 5.2 By End-User Industry
- 5.2.1 Automotive
- 5.2.2 Communication (Wired and Wireless)
- 5.2.3 Consumer Electronics
- 5.2.4 Industrial
- 5.2.5 Computing and Data Storage
- 5.2.6 Data Center
- 5.2.7 Artificial Intelligence
- 5.2.8 Government (Aerospace and Defense)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Tata Electronics Private Limited
- 6.4.2 Vedanta Semiconductors Private Limited
- 6.4.3 Bharat Electronics Limited
- 6.4.4 MosChip Technologies Limited
- 6.4.5 Applied Materials India Private Limited
- 6.4.6 ASM Technologies Limited
- 6.4.7 Suchi Semicon Private Limited
- 6.4.8 NXP Semiconductors N.V.
- 6.4.9 HCL Technologies Limited
- 6.4.10 Infineon Technologies AG
- 6.4.11 Renesas Electronics Corporation
- 6.4.12 STMicroelectronics N.V.
- 6.4.13 Powerchip Semiconductor Manufacturing Corporation
- 6.4.14 Intel Corporation
- 6.4.15 Samsung Electronics Co., Ltd.
- 6.4.16 Qualcomm Incorporated
- 6.4.17 Micron Technology, Inc.
- 6.4.18 Texas Instruments Incorporated
- 6.4.19 MediaTek Inc.
- 6.4.20 Taiwan Semiconductor Manufacturing Company Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

