PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124368

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124368
Geomarketing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, geomarketing market size in 2026 is estimated at USD 29.38 billion, growing from 2025 value of USD 23.72 billion with 2031 projections showing USD 85.83 billion, growing at 23.9% CAGR over 2026-2031.
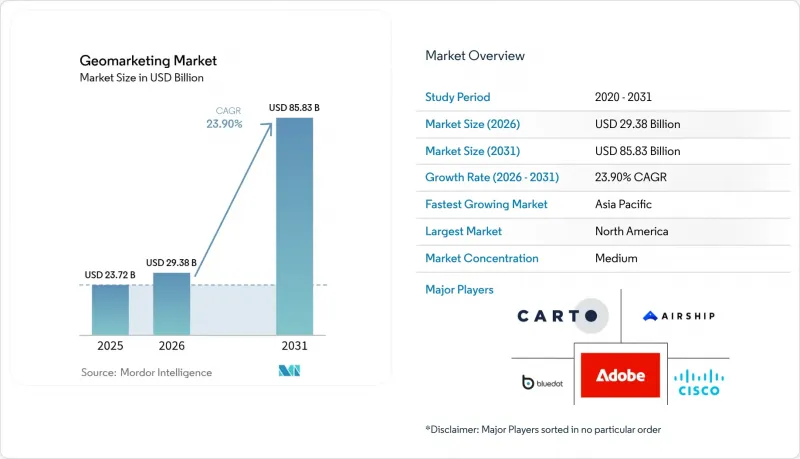
This report is Segmented by Component (Software and Services), Deployment (Cloud and On-Premise), Location (Indoor and Outdoor), End-User Industry (BFSI, IT and Telecommunications, and More), Organization Size (Large Enterprises and Small and Medium Enterprises), Technology (GPS/Cellular, BLE Beacons, and More), Solution Type (Mapping and Geocoding, Location Analytics and Visualization, and More), and Geography.
Global Geomarketing Market Trends and Insights
AI-Driven Hyper-Personalization of Location Ads
Real-time machine-learning models now adapt creatives to an individual's movement patterns, dwell time, and venue preferences, enabling retailers to improve ad-spend efficiency by up to 40% compared with traditional geo-targeting methods. Arrival-time predictions shrink fulfillment gaps, while computer vision links foot traffic to demographic insights, as seen when Aura Vision boosted conversion at Flannels and returned a 4.5 X ROI. These capabilities elevate personalized engagement from optional to indispensable and keep the geomarketing market on an aggressive growth trajectory.
Growing 5G Roll-Outs Expand Indoor Accuracy
Carrier-phase measurements introduced in 3GPP Release 18 deliver sub-meter precision, allowing geomarketing in airports, malls, and factories where GPS once failed. Enterprises have documented 15-20% productivity gains via automated asset tracking, though mmWave infrastructure requires dense cells and capital investment. Hybrid stacks blending 5G with BLE and Wi-Fi are emerging as a pragmatic route to comprehensive coverage, reinforcing near-term demand for indoor location solutions.
Stringent Opt-In Consent Under GDPR/CCPA
Regulators now require explicit, affirmative location-data consent, raising compliance costs that range from USD 500,000 to USD 2 million for enterprise platforms. With 21 US states enacting similar laws, fines can touch USD 10,000 per incident. Geo-contextual consent banners aid regional compliance but add operational overhead, keeping privacy at the center of vendor roadmaps.
Other drivers and restraints analyzed in the detailed report include:
- Retail Digital Twins Link Foot-Traffic and Spend
- Mainstream Adoption of Beacons in Quick-Service Restaurants
- Depreciation of Mobile Ad-IDs Lowers Match Rates
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software platforms accounted for 65.55% revenue in 2025, underscoring the geomarketing market preference for cloud-native, feature-rich stacks that can ingest varied data sources and comply with changing privacy rules. Continuous updates funnel AI segmentation, compliance dashboards, and API connectors into user hands without on-premise friction. Services, led by integration and managed analytics, accelerate at 26.69% CAGR as enterprises seek guidance on stitching geomarketing insights into sprawling MarTech architectures.The geomarketing market size tied to services climbs quickly because tailored onboarding, custom algorithm design, and regulatory audits remain outside most in-house skill sets. Oracle's 2025 cloud revenue growth to USD 11.7 billion illustrates how bundled software-plus-services agreements satisfy enterprise appetite for turnkey location intelligence.
Cloud held 70.42% share of the geomarketing market in 2025 and posts the highest 25.46% CAGR as brands favor elastic compute and rapid scaling for high-volume campaigns. Microsoft Azure's 31% revenue jump reflects surging demand for GPU-accelerated analytics and serverless geospatial pipelines.On-premise persists in sectors with strict data sovereignty, yet faces cost headwinds; enterprises cutting hardware and maintenance achieve 40-60% savings in total cost of ownership. Network egress fees and latency constraints keep certain low-latency applications hybrid, but incremental cloud security advances continue drawing workloads into multitenant environments, expanding the geomarketing market footprint.
Outdoor services preserved 59.62% revenue in 2025 thanks to ubiquitous GPS, while indoor positioning's 26.74% CAGR showcases demand for asset tracking and immersive retail. China Mobile's 5G system reached 3-5 meter accuracy across 90% of covered space, setting functional benchmarks for venues worldwide.As enterprises embed hybrid BLE-Wi-Fi-5G arrays, the geomarketing market size for indoor services swells, enabling queue management, real-time navigation, and proximity offers. Deployment complexity and cost remain hurdles, but declining beacon prices and managed-service bundles reduce entry barriers for mid-tier retailers and hospitals.
Complete Report Scope:
- By Component
- Software
- Services
- By Deployment
- Cloud
- On-Premise
- By Location
- Indoor
- Outdoor
- By End-User Industry
- BFSI
- IT and Telecommunications
- Retail and E-commerce
- Media and Entertainment
- Travel and Hospitality
- Other End-user Industries
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By Technology
- GPS/Cellular
- BLE Beacons
- Wi-Fi/WLAN
- NFC/RFID
- By Solution Type
- Mapping and Geocoding
- Location Analytics and Visualization
- Geo-Fencing and Proximity Marketing
- Real-Time Tracking
- Campaign Planning and Management
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Singapore
- Malaysia
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America maintained 37.25% of global revenue in 2025, underpinned by mature ad-tech ecosystems, broad 5G penetration, and balanced privacy statutes. Google Cloud logged 30% revenue growth as enterprises layered spatial intelligence on existing data lakes. Federal and state data-privacy frameworks mandate explicit consent yet still permit innovation, ensuring continued investment in precision targeting and omni-channel attribution.Asia-Pacific posts the sharpest 26.31% CAGR, fuelled by population-scale mobile adoption, government 5G incentives, and a mobile-first retail ethos. The GSMA estimates mobile contributed USD 880 billion to regional GDP in 2023, while policies in China, Japan, and Malaysia finance AI and indoor-location pilots. Dual-network 5G frameworks and satellite backhaul projects promise to extend high-accuracy coverage into rural areas, widening the geomarketing market opportunity.Europe advances steadily despite GDPR compliance costs. Enterprises adopt edge processing, federated learning, and differential privacy to reconcile localization with regulatory stringency. Middle East and Africa and Latin America remain emergent yet promising: smart-city investments in the Gulf and rising smartphone penetration in Brazil and Mexico catalyze pilot deployments. Infrastructure gaps and legal uncertainty temper immediate scale, but urbanization and digital payments create fertile ground for localized growth in the next planning cycle.
- Adobe Inc.
- Airship Group Inc.
- Bluedot Industries Pty Ltd.
- CartoDB Inc.
- Cisco Systems Inc.
- Cuebiq Inc.
- ESRI Inc.
- Ericsson AB
- Foursquare Labs Inc.
- Galigeo SAS
- Google LLC
- GroundTruth Inc.
- HERE Technologies
- IBM Corporation
- InMarket Media LLC
- Localytics (Upland Software Inc.)
- Mapbox Inc.
- Microsoft Corporation
- Near Intelligence Holdings Inc.
- Oracle Corporation
- PlaceIQ Inc.
- Plot Projects BV
- Precisely (MapInfo)
- Qualcomm Technologies Inc.
- Radar Labs Inc.
- Reveal Mobile Inc.
- Software AG
- TomTom NV
- UberMedia LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 AI-driven hyper-personalization of location ads
- 4.2.2 Growing 5G roll-outs expand indoor accuracy
- 4.2.3 Retail digital twins link foot-traffic and spend
- 4.2.4 Mainstream adoption of beacons in quick-service restaurants
- 4.2.5 Rideshare and micromobility data monetization
- 4.2.6 MarTech stacks embedding real-time geofencing
- 4.3 Market Restraints
- 4.3.1 Stringent opt-in consent under GDPR/CCPA
- 4.3.2 Depreciation of mobile ad-IDs lowers match rates
- 4.3.3 Indoor triangulation accuracy gaps in large venues
- 4.3.4 High TCO for multi-source data normalization
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Industry Attractiveness - Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Deployment
- 5.2.1 Cloud
- 5.2.2 On-Premise
- 5.3 By Location
- 5.3.1 Indoor
- 5.3.2 Outdoor
- 5.4 By End-User Industry
- 5.4.1 BFSI
- 5.4.2 IT and Telecommunications
- 5.4.3 Retail and E-commerce
- 5.4.4 Media and Entertainment
- 5.4.5 Travel and Hospitality
- 5.4.6 Other End-user Industries
- 5.5 By Organization Size
- 5.5.1 Large Enterprises
- 5.5.2 Small and Medium Enterprises (SMEs)
- 5.6 By Technology
- 5.6.1 GPS/Cellular
- 5.6.2 BLE Beacons
- 5.6.3 Wi-Fi/WLAN
- 5.6.4 NFC/RFID
- 5.7 By Solution Type
- 5.7.1 Mapping and Geocoding
- 5.7.2 Location Analytics and Visualization
- 5.7.3 Geo-Fencing and Proximity Marketing
- 5.7.4 Real-Time Tracking
- 5.7.5 Campaign Planning and Management
- 5.8 By Geography
- 5.8.1 North America
- 5.8.1.1 United States
- 5.8.1.2 Canada
- 5.8.1.3 Mexico
- 5.8.2 South America
- 5.8.2.1 Brazil
- 5.8.2.2 Argentina
- 5.8.2.3 Chile
- 5.8.2.4 Rest of South America
- 5.8.3 Europe
- 5.8.3.1 Germany
- 5.8.3.2 United Kingdom
- 5.8.3.3 France
- 5.8.3.4 Italy
- 5.8.3.5 Spain
- 5.8.3.6 Russia
- 5.8.3.7 Rest of Europe
- 5.8.4 Asia-Pacific
- 5.8.4.1 China
- 5.8.4.2 India
- 5.8.4.3 Japan
- 5.8.4.4 South Korea
- 5.8.4.5 Singapore
- 5.8.4.6 Malaysia
- 5.8.4.7 Australia
- 5.8.4.8 Rest of Asia-Pacific
- 5.8.5 Middle East and Africa
- 5.8.5.1 Middle East
- 5.8.5.1.1 United Arab Emirates
- 5.8.5.1.2 Saudi Arabia
- 5.8.5.1.3 Turkey
- 5.8.5.1.4 Rest of Middle East
- 5.8.5.2 Africa
- 5.8.5.2.1 South Africa
- 5.8.5.2.2 Nigeria
- 5.8.5.2.3 Rest of Africa
- 5.8.5.1 Middle East
- 5.8.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Adobe Inc.
- 6.4.2 Airship Group Inc.
- 6.4.3 Bluedot Industries Pty Ltd.
- 6.4.4 CartoDB Inc.
- 6.4.5 Cisco Systems Inc.
- 6.4.6 Cuebiq Inc.
- 6.4.7 ESRI Inc.
- 6.4.8 Ericsson AB
- 6.4.9 Foursquare Labs Inc.
- 6.4.10 Galigeo SAS
- 6.4.11 Google LLC
- 6.4.12 GroundTruth Inc.
- 6.4.13 HERE Technologies
- 6.4.14 IBM Corporation
- 6.4.15 InMarket Media LLC
- 6.4.16 Localytics (Upland Software Inc.)
- 6.4.17 Mapbox Inc.
- 6.4.18 Microsoft Corporation
- 6.4.19 Near Intelligence Holdings Inc.
- 6.4.20 Oracle Corporation
- 6.4.21 PlaceIQ Inc.
- 6.4.22 Plot Projects BV
- 6.4.23 Precisely (MapInfo)
- 6.4.24 Qualcomm Technologies Inc.
- 6.4.25 Radar Labs Inc.
- 6.4.26 Reveal Mobile Inc.
- 6.4.27 Software AG
- 6.4.28 TomTom NV
- 6.4.29 UberMedia LLC
7 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 7.1 White-Space and Unmet-Need Assessment

