PUBLISHER: Roots Analysis | PRODUCT CODE: 2106266
PUBLISHER: Roots Analysis | PRODUCT CODE: 2106266
Pulsed Field Ablation Market by Therapeutic Area, Product Components, Application Area, Source of Ablation, Key Geographical Regions, and Sales Forecast of Leading Players - Trends and Forecast till 2035
PULSED FIELD ABLATION MARKET: OVERVIEW
As per Roots Analysis, the global pulsed field ablation market is estimated to grow from USD 3.2 billion in the current year to USD 14.6 billion by 2035, reflecting a compound annual growth rate (CAGR) of approximately 18.4% during the forecast period.
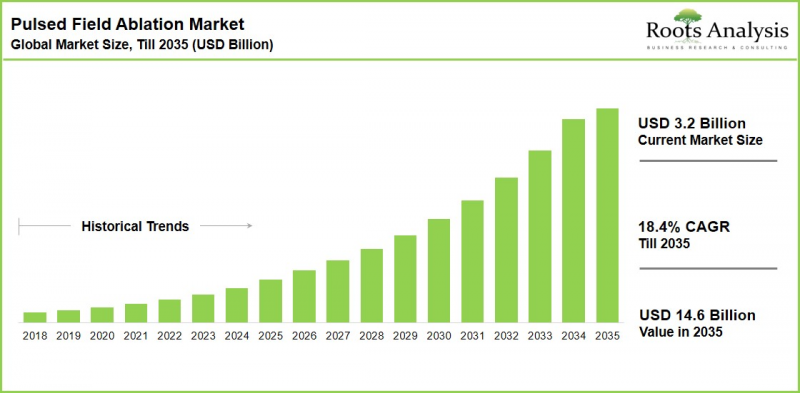
Pulsed Field Ablation Market: Growth and Trends
Pulsed field ablation (PFA) is a non-thermal cardiac ablation modality that uses short, high-voltage electrical pulses to induce irreversible electroporation in target tissue. Unlike radiofrequency and cryoablation, which rely on heat or cold energy and carry a risk of collateral injury to structures such as the esophagus and phrenic nerve, PFA selectively targets myocardial cells while sparing surrounding tissue. This safety differentiation has made PFA one of the fastest-adopted technologies in electrophysiology over the past few years.
Clinical evidence supporting PFA continues to expand across multiple platforms and procedural workflows. For instance, Boston Scientific's FARAPULSE system has demonstrated strong symptomatic relief rates in treated atrial fibrillation patients. Moreover, several other systems from Medtronic, Biosense Webster, and emerging players have secured regulatory clearances in the US, Europe, and Asian countries. This growing base of approvals is accelerating clinical adoption and encouraging hospitals to invest in dedicated PFA-capable electrophysiology labs.
Further, the convergence of PFA with artificial intelligence-enabled electrophysiology workflows is an emerging area of interest. AI tools are increasingly being applied to improve patient selection, guide lesion delivery beyond standard pulmonary vein isolation, and streamline procedural planning. The integration of AI tools helps operators achieve more consistent outcomes while managing procedure time.
At the same time, evolving tariff and trade policies affecting medical device imports are prompting several manufacturers to localize or near-shore production of PFA generators, catheters, and related components within the US and Europe. This will help to reduce exposure to cross-border duties and supply chain disruption.
Growth Drivers: Factors Fueling Market Expansion
Growth in the pulsed field ablation market is driven by the rising global burden of atrial fibrillation. According to a Heart Rhythm Society article, atrial fibrillation affects around 40 million people worldwide, and the number of cases is likely to increase by 60% in 2050. As detection improves through wearable and remote monitoring technologies, the diagnosed patient pool requiring rhythm-control therapy continues to expand, creating sustained procedural demand.
Notably, PFA's tissue selectivity and non-thermal mechanism are core differentiators supporting its adoption over conventional thermal ablation techniques as it reduces complications and shortens procedure times. Beyond cardiology, device developers are adapting PFA platforms for tissue-selective tumour ablation near sensitive anatomical structures, such as liver, pancreas, prostate, kidney, and lung.
Expanding electrophysiology lab infrastructure and growing adoption of electroporation-based therapy and improving reimbursement frameworks are further reinforcing the long-term growth outlook of the market.
Market Challenges: Critical Barriers Hindering Progress
Despite strong growth momentum, the pulsed field ablation market faces several adoption barriers. PFA consoles and single-use catheters require a significantly higher upfront and per-procedure cost compared with established radiofrequency and cryoablation systems. High treatment expenses create affordability challenges for smaller hospitals, ambulatory surgical centres, and cost-constrained health systems.
Many public and smaller private hospitals also lack the capital budgets, dedicated electrophysiology labs, and procedural volumes needed to justify a new PFA platform. Therefore, the lack of dedicated labs is slowing broader rollout outside high-volume tertiary centres. Continued competition from well-established thermal ablation technologies, along with the need for further procedural standardization across newer PFA platforms, adds additional friction to near-term market expansion.
Pulsed Field Ablation Market: Key Insights
The report delves into the current state of the pulsed field ablation market and identifies potential growth opportunities within the industry, particularly from a distributor and channel-partner perspective. Some key findings include:
- Device manufacturers rely predominantly on direct sales forces and dedicated clinical specialist teams to commercialize pulsed field ablation systems in mature markets such as the US and Western Europe, which limits the near-term role of third-party distributors in these geographies.
- In Asia-Pacific, and Latin America manufacturers lacking established commercial infrastructure are increasingly relying on regional and national distribution partners to navigate local regulatory pathways and build hospital relationships, creating a distinct entry point for specialty medical device distributors.
- The extension of pulsed field technology into interventional oncology is creating new distribution entry points beyond electrophysiology, opening the door to distributors with existing interventional radiology and oncology channel relationships.
- Region-specific device registration requirements, including China's NMPA and Japan's PMDA pathways, extend onboarding timelines for new distribution partners even after a device secures its first regulatory approval in the US or Europe.
- Manufacturers are increasingly near-shoring or localizing production of generators and catheters in the US and Europe in response to evolving tariff and trade policy, a shift that is reshaping distributor sourcing strategies and inventory planning.
- Post-market evidence generation requirements, including registry participation and outcomes tracking, are pushing manufacturers to favour distribution partners capable of supporting structured data collection, particularly in newer expansion markets.
- Consolidation among large, established electrophysiology equipment distributors is raising the bar for entry, though niche regional distributors with condition-specific or catheter lab-specific expertise continue to find opportunities in underserved geographies.
Pulsed Field Ablation Market Segments
The market sizing and opportunity analysis has been segmented across the following parameters:
By Therapeutic Area
- Cardiovascular Disorders
- Dermatological Disorders
- Oncological Disorders
- Respiratory Disorders
By Product Components
- Catheters
- Generators
By Application Area
- Ablation
- Ablation and Mapping
By Source of Ablation
- Pulsed Field Energy
- Pulsed Field and Cryoablation Energy
- Pulsed Field and Radiofrequency Energy
By Geographical Regions
- North America
- US
- Canada
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- Australia
Pulsed Field Ablation Market: Key Segments
Cardiovascular Disorders Leads the Target Indication Segment
Based on our market assessment, the cardiovascular disorders segment currently accounts for the majority of the pulsed field ablation market and is expected to retain its leadership position throughout the forecast period. This dominance stems from the fact that PFA devices have achieved their highest level of clinical validation, regulatory approval, and commercial adoption in the treatment of atrial fibrillation and related arrhythmias. Growing procedural volumes, expanding electrophysiology infrastructure, and the availability of multiple commercially approved platforms continue to reinforce cardiovascular applications as the primary revenue-generating segment.
In contrast, the oncological disorders segment is expected to register the highest CAGR during the forecast period. This highest growth is supported by the transition of pulsed field technology from a predominantly cardiac tool towards a broader tissue-selective treatment platform. As irreversible electroporation continues to demonstrate promising outcomes in liver, pancreatic, prostate, kidney, and lung tumours, device manufacturers, research institutions, and healthcare providers are directing increasing investment toward this emerging application.
Catheter Dominates the Product Component Segment
Based on the product components, the catheter sub-segment is expected to continue capturing the majority of pulsed field ablation market revenue. This is primarily attributed to the single-use, consumable nature of PFA catheters, which follow a recurring, per-procedure revenue model in contrast to generators.
As the market matures, next-generation catheters that integrate mapping and ablation functionality into a single platform are expected to command higher average selling prices, which further accelerate this segment growth.
Ablation Remains the Leading Application, While Ablation and Mapping Gains Momentum
By application area, ablation-only configurations currently hold the largest share of the market. This highest share reflects the early focus on pulmonary vein isolation procedures where speed, reproducibility, and reduced fluoroscopy time are prioritized over integrated mapping. The shift toward treating more complex and persistent arrhythmia substrates will likely accelerate growth in the ablation and mapping segment. This growth is further fueled by hospital investments in integrated, single-platform electrophysiology ecosystems.
Pulsed Field Energy Dominates the Source of Ablation Segment
Based on the source of ablation, pure pulsed field energy platforms currently capture the majority of market share. This dominance is driven by the fundamental safety advantage pulsed field energy offers over thermal modalities. Notably, the standardization benefits of single-platform ecosystems that integrate catheter design, waveform optimization, and mapping compatibility, reduce training complexity for operators, making it a preferable choice in clinical settings.
North America Leads, While Asia-Pacific Emerges as the Fastest-Growing Region
According to our market projections, North America is expected to maintain its leadership in the pulsed field ablation market through 2035. This dominance is supported by early commercialization advantage, a dense concentration of electrophysiology-capable hospitals, rapid FDA-driven regulatory clearances, and a well-structured reimbursement framework for atrial fibrillation ablation procedures.
Asia-Pacific, on the other hand, is projected to register the highest CAGR during the forecast period. This growth is driven by rapidly improving healthcare infrastructure, growing investment in cardiac catheterization laboratories, expanding electrophysiology training programs, and a large, aging population base with a significant untreated atrial fibrillation burden across markets such as China, India, and South Korea.
Example Players in Pulsed Field Ablation Market
- AccuPulse Medical
- Acutus Medical
- Adagio Medical
- AngioDynamics
- Arga Medtech
- AtriAN Medical
- Biosense Webster (Johnson & Johnson MedTech)
- Boston Scientific
- CardioFocus
- CathRx
- CRC EP
- Galvanize Therapeutics
- Gradient Medical
- Hangzhou Dinova EP Technology
- Kardium
- Medtronic
- Mirai Medical
- Pulse Biosciences
Expert Interview and Industry Insights
The opinions and insights presented in this study were shaped by discussions conducted with multiple stakeholders across the pulsed field ablation ecosystem. The research report features detailed transcripts of interviews held with the following industry stakeholders:
- Co-Founder and Chief Executive Officer, Small Company, Switzerland
- Chief Medical Officer, Very Large Company, US
- Chief of Cardiac Surgery and Co-Director, Very Large Company, US
- Senior Vice President and President, Cardiac Rhythm Management and Diagnostics, Very Large Company, US
- President, and Vice President of Preclinical and Clinical Research and Medical Affairs, Very Large Company, New Zealand
- Managing Director, Large Company, US
- Managing Director, Very Large Company, US
- Director, Ventricular Tachycardia Program, Very Large Company, US
- Co-Director, Translational Research and Research Fellowship, Very Large Company, US
- Cardiologist, Very Large Company, US
PULSED FIELD ABLATION MARKET: RESEARCH COVERAGE
- Market Sizing and Opportunity Analysis: The report features an in-depth analysis of the pulsed field ablation market, focusing on key market segments, including therapeutic area, product components, application area, source of ablation, and geographical regions.
- Pulsed Field Ablation Devices Landscape: A detailed assessment of the overall device landscape, featuring information on parameters such as type of product component, application area, source of ablation, and regulatory approval status. Additionally, it features analysis of device developers based on year of establishment, company size, and location of headquarters.
- Company Profiles: In-depth profiles of prominent players engaged in offering pulsed field ablation systems, featuring information on year of establishment, location of headquarters, company size, management team, product portfolio, and key initiatives.
- Recent Developments: A detailed analysis of recent developments in this industry, including partnerships and collaborations, funding and investments, regulatory approvals, and product launches.
- Patent Analysis: An analysis of patents filed and granted related to pulsed field ablation devices, based on parameters such as type of patent, application and publication year, jurisdiction, CPC symbols, type of applicant, and patent valuation.
- Global Events Analysis: An in-depth assessment of global pulsed field ablation events, covering event trends by year, type, platform, and geography, along with analyses of key organizers, participating companies, speaker profiles, and emerging discussion themes to identify evolving industry priorities and networking opportunities.
- Strategic Partner Analysis: A comprehensive assessment of potential partnership opportunities for pulsed field ablation device developers, featuring a likelihood-based evaluation of cardiac mapping and navigation device companies based on predefined assumptions, key parameters, and proprietary partner selection methodology.
- Market Impact Analysis: The report also covers analyses of drivers, restraints, opportunities, and challenges affecting market growth.
Key Questions Answered in this Report
- Which are the leading companies in the pulsed field ablation market?
- Which region dominates the pulsed field ablation market, and which region is growing the fastest?
- What are the key trends observed in the pulsed field ablation market?
- What factors are likely to influence the evolution of this market?
- What are the primary challenges faced by pulsed field ablation device developers and distributors?
- What is the current and future market size?
- What is the CAGR of this market?
- How is the current and future market opportunity likely to be distributed across key market segments?
- What distribution models are manufacturers using across mature and emerging markets?
Reasons to Buy this Report
This report has been specifically developed to support distributors, channel partners, and business development teams evaluating entry into the pulsed field ablation market.
- Comprehensive Secondary Research: Extensive analysis of company disclosures, regulatory databases, clinical trial registries, investor presentations, scientific literature, and industry publications to evaluate market trends, competitive landscape, and commercialization strategies.
- Primary Research Validation: Insights validated through interviews with senior executives, electrophysiologists, cardiac surgeons, and industry experts to strengthen market assumptions and forecast accuracy.
- Market and Commercial Analysis: Evaluation of product segmentation, revenue models (capital equipment and consumables), distribution channels, and regional commercialization strategies across key markets.
- Regulatory and Regional Assessment: Analysis of country-specific regulatory pathways, reimbursement environment, and market-entry considerations across North America, Europe, and Asia-Pacific.
- Forecasting Framework: Market forecasts developed using historical trends, demand analysis, primary validation, and scenario-based (conservative, base, and optimistic) forecasting, incorporating recent clinical evidence and regulatory developments.
Additional Benefits
- Complementary Insights Pack
- Complementary Excel Data Packs for all Analytical Modules in the Report
- 15% Free Content Customization
- Detailed Report Walkthrough Session with Research Team
- Free Updated report if the report is 6-12 months old or older
TABLE OF CONTENTS
1. PREFACE
- 1.1. Introduction
- 1.2. Market Share Insights
- 1.3. Key Market Insights
- 1.4. Report Coverage
- 1.5. Key Questions Answered
- 1.6. Chapter Outlines
2. RESEARCH METHODOLOGY
- 2.1. Chapter Overview
- 2.2. Research Assumptions
- 2.2.1. Market Landscape and Market Trends
- 2.2.2. Market Forecast and Opportunity Analysis
- 2.2.3. Comparative Analysis
- 2.3. Database Building
- 2.3.1. Data Collection
- 2.3.2. Data Validation
- 2.3.3. Data Analysis
- 2.4. Project Methodology
- 2.4.1. Secondary Research
- 2.4.1.1. Annual Reports
- 2.4.1.2. Academic Research Papers
- 2.4.1.3. Company Websites
- 2.4.1.4. Investor Presentations
- 2.4.1.5. Regulatory Filings
- 2.4.1.6. White Papers
- 2.4.1.7. Industry Publications
- 2.4.1.8. Conferences and Seminars
- 2.4.1.9. Government Portals
- 2.4.1.10. Media and Press Releases
- 2.4.1.11. Newsletters
- 2.4.1.12. Industry Databases
- 2.4.1.13. Roots Proprietary Databases
- 2.4.1.14. Paid Databases and Sources
- 2.4.1.15. Social Media Portals
- 2.4.1.16. Other Secondary Sources
- 2.4.2. Primary Research
- 2.4.2.1. Types of Primary Research
- 2.4.2.1.1. Qualitative Research
- 2.4.2.1.2. Quantitative Research
- 2.4.2.1.3. Hybrid Approach
- 2.4.2.2. Advantages of Primary Research
- 2.4.2.3. Techniques for Primary Research
- 2.4.2.3.1. Interviews
- 2.4.2.3.2. Surveys
- 2.4.2.3.3. Focus Groups
- 2.4.2.3.4. Observational Research
- 2.4.2.3.5. Social Media Interactions
- 2.4.2.4. Key Opinion Leaders Considered in Primary Research
- 2.4.2.4.1. Company Executives (CXOs)
- 2.4.2.4.2. Board of Directors
- 2.4.2.4.3. Company Presidents and Vice Presidents
- 2.4.2.4.4. Research and Development Heads
- 2.4.2.4.5. Technical Experts
- 2.4.2.4.6. Subject Matter Experts
- 2.4.2.4.7. Scientists
- 2.4.2.4.8. Doctors and Other Healthcare Providers
- 2.4.2.5. Ethics and Integrity
- 2.4.2.5.1. Research Ethics
- 2.4.2.5.2. Data Integrity
- 2.4.2.1. Types of Primary Research
- 2.4.3. Analytical Tools and Databases
- 2.4.1. Secondary Research
- 2.5. Robust Quality Control
3. MARKET DYNAMICS
- 3.1. Chapter Overview
- 3.2. Forecast Methodology
- 3.2.1. Top-down Approach
- 3.2.2. Bottom-up Approach
- 3.2.3. Hybrid Approach
- 3.3. Market Assessment Framework
- 3.3.1. Total Addressable Market (TAM)
- 3.3.2. Serviceable Addressable Market (SAM)
- 3.3.3. Serviceable Obtainable Market (SOM)
- 3.3.4. Currently Acquired Market (CAM)
- 3.4. Forecasting Tools and Techniques
- 3.4.1. Qualitative Forecasting
- 3.4.2. Correlation
- 3.4.3. Regression
- 3.4.4. Extrapolation
- 3.4.5. Convergence
- 3.4.6. Sensitivity Analysis
- 3.4.7. Scenario Planning
- 3.4.8. Data Visualization
- 3.4.9. Time Series Analysis
- 3.4.10. Forecast Error Analysis
- 3.5. Key Considerations
- 3.5.1. Demographics
- 3.5.2. Government Regulations
- 3.5.3. Reimbursement Scenarios
- 3.5.4. Market Access
- 3.5.5. Supply Chain
- 3.5.6. Industry Consolidation
- 3.5.7. Pandemic / Unforeseen Disruptions Impact
- 3.6. Limitations
4. MACRO-ECONOMIC INDICATORS
- 4.1. Chapter Overview
- 4.2. Market Dynamics
- 4.2.1. Time Period
- 4.2.1.1. Historical Trends
- 4.2.1.2. Current and Forecasted Estimates
- 4.2.2. Currency Coverage
- 4.2.2.1. Major Currencies Affecting the Market
- 4.2.2.2. Factors Affecting Currency Fluctuations in the Industry
- 4.2.2.3. Impact of Currency Fluctuations on the Industry
- 4.2.3. Foreign Currency Exchange Rate
- 4.2.3.1. Impact of Foreign Exchange Rate Volatility on the Market
- 4.2.3.2. Strategies for Mitigating Foreign Exchange Risk
- 4.2.4. Recession
- 4.2.4.1. Assessment of Current Economic Conditions and Potential Impact on the Market
- 4.2.4.2. Historical Analysis of Past Recessions and Lessons Learnt
- 4.2.5. Inflation
- 4.2.5.1. Measurement and Analysis of Inflationary Pressures in the Economy
- 4.2.5.2. Potential Impact of Inflation on the Market Evolution
- 4.2.6. Interest Rates
- 4.2.6.1. Interest Rates and Their Impact on the Market
- 4.2.6.2. Strategies for Managing Interest Rate Risk
- 4.2.7. Commodity Flow Analysis
- 4.2.7.1. Type of Commodity
- 4.2.7.2. Origins and Destinations
- 4.2.7.3. Values and Weights
- 4.2.7.4. Modes of Transportation
- 4.2.8. Global Trade Dynamics
- 4.2.8.1. Import Scenario
- 4.2.8.2. Export Scenario
- 4.2.8.3. Trade Policies
- 4.2.8.4. Strategies for Mitigating the Risks Associated with Trade Barriers
- 4.2.8.5. Impact of Trade Barriers on the Market
- 4.2.9. War Impact Analysis
- 4.2.9.1. Russia-Ukraine War
- 4.2.9.2. Israel-Hamas War
- 4.2.10. COVID Impact / Related Factors
- 4.2.10.1. Global Economic Impact
- 4.2.10.2. Industry-specific Impact
- 4.2.10.3. Government Response and Stimulus Measures
- 4.2.10.4. Future Outlook and Adaptation Strategies
- 4.2.11. Other Indicators
- 4.2.11.1. Fiscal Policy
- 4.2.11.2. Consumer Spending
- 4.2.11.3. Gross Domestic Product
- 4.2.11.4. Employment
- 4.2.11.5. Taxes
- 4.2.11.6. Stock Market Performance
- 4.2.11.7. Cross Border Dynamics
- 4.2.1. Time Period
- 4.3. Conclusion
5. EXECUTIVE SUMMARY
6. INTRODUCTION
- 6.1. Chapter Overview
- 6.2. mRNA Vaccines
- 6.2.1. Advantages of mRNA Vaccines
- 6.2.2. Key Applications of mRNA Vaccines
- 6.3. mRNA Vaccines
- 6.3.1. Advantages of mRNA Vaccines
- 6.3.2. Key Applications of mRNA Vaccines
- 6.4. mRNA Delivery Routes
- 6.5. mRNA Delivery Strategies
- 6.6. Key Challenges Associated with mRNA Vaccines
- 6.7. Future Perspectives
7. MARKET LANDSCAPE
- 7.1. Chapter Overview
- 7.2. mRNA Vaccines: Overall Market Landscape
- 7.2.1. Analysis by Status of Development
- 7.2.2. Analysis by Type of Drug Candidate
- 7.2.3. Analysis by Type of Program
- 7.2.4. Analysis by Type of Delivery System
- 7.2.5. Analysis by Type of Molecule Encoded
- 7.2.6. Analysis by Route of Administration
- 7.2.7. Analysis by Therapeutic Area
- 7.3. mRNA Vaccines: Developer Landscape
- 7.3.1. Analysis by Year of Establishment
- 7.3.2. Analysis by Company Size
- 7.3.3. Analysis by Location of Headquarters
- 7.3.4. Most Active Developers: Analysis by Number of Drugs Developed
8. PRODUCT COMPETITIVENESS ANALYSIS
- 8.1. Chapter Overview
- 8.2. Assumptions and Key Parameters
- 8.3. Methodology
- 8.4. mRNA Vaccines: Product Competitiveness Analysis
- 8.4.1. mRNA Vaccines Developed by Players based in North America
- 8.4.2. mRNA Vaccines Developed by Players based in Europe
- 8.4.3. mRNA Vaccines Developed by Players based in Asia-Pacific and Rest of the World
9. COMPANY PROFILES: mRNA VACCINE DEVELOPERS BASED IN NORTH AMERICA
- 9.1. Chapter Overview
- 9.2. Leading Developers in mRNA Vaccines Market based in North America
- 9.2.1. Arcturus Therapeutics
- 9.2.1.1. Company Overview
- 9.2.1.2. Financial Information
- 9.2.1.3. mRNA Vaccines Portfolio
- 9.2.1.4. Recent Developments and Future Outlook
- 9.2.2. Immorna
- 9.2.2.1. Company Overview
- 9.2.2.2. mRNA Vaccines Portfolio
- 9.2.2.3. Recent Developments and Future Outlook
- 9.2.3. Moderna
- 9.2.3.1. Company Overview
- 9.2.3.2. Financial Information
- 9.2.3.3. mRNA Vaccines Portfolio
- 9.2.3.4. Recent Developments and Future Outlook
- 9.2.4. Providence Therapeutics
- 9.2.4.1. Company Overview
- 9.2.4.2. Financial Information
- 9.2.4.3. mRNA Vaccines Portfolio
- 9.2.4.4. Recent Developments and Future Outlook
- 9.2.5. Innovac Therapeutics
- 9.2.5.1. Company Overview
- 9.2.5.2. mRNA Vaccines Portfolio
- 9.2.5.3. Recent Developments and Future Outlook
- 9.2.6. Kernal Biologics
- 9.2.6.1. Company Overview
- 9.2.6.2. Financial Information
- 9.2.6.3. mRNA Vaccines Portfolio
- 9.2.6.4. Recent Developments and Future Outlook
- 9.2.7. Recode Therapeutics
- 9.2.7.1. Company Overview
- 9.2.7.2. Financial Information
- 9.2.7.3. mRNA Vaccines Portfolio
- 9.2.7.4. Recent Developments and Future Outlook
- 9.2.8. Rejuvenation Technologies
- 9.2.8.1. Company Overview
- 9.2.8.2. Financial Information
- 9.2.8.3. mRNA Vaccines Portfolio
- 9.2.8.4. Recent Developments and Future Outlook
- 9.2.9. RNAimmune
- 9.2.9.1. Company Overview
- 9.2.9.2. Financial Information
- 9.2.9.3. mRNA Vaccines Portfolio
- 9.2.9.4. Recent Developments and Future Outlook
- 9.2.10. Turn Biotechnologies
- 9.2.10.1. Company Overview
- 9.2.10.2. Financial Information
- 9.2.10.3. mRNA Vaccines Portfolio
- 9.2.10.4. Recent Developments and Future Outlook
- 9.2.11. Strand Therapeutics
- 9.2.11.1. Company Overview
- 9.2.11.2. Financial Information
- 9.2.11.3. mRNA Vaccines Portfolio
- 9.2.11.4. Recent Developments and Future Outlook
- 9.2.1. Arcturus Therapeutics
10. COMPANY PROFILES: mRNA VACCINE DEVELOPERS BASED IN EUROPE
- 10.1. Chapter Overview
- 10.2. Leading Developers in mRNA Vaccines Market based in North America
- 10.2.1. BioNTech
- 10.2.1.1. Company Overview
- 10.2.1.2. Financial Information
- 10.2.1.3. mRNA Vaccines Portfolio
- 10.2.1.4. Recent Developments and Future Outlook
- 10.2.2. CureVac
- 10.2.2.1. Company Overview
- 10.2.2.2. Financial Information
- 10.2.2.3. mRNA Vaccines Portfolio
- 10.2.2.4. Recent Developments and Future Outlook
- 10.2.3. Ethris
- 10.2.3.1. Company Overview
- 10.2.3.2. mRNA Vaccines Portfolio
- 10.2.3.3. Recent Developments and Future Outlook
- 10.2.1. BioNTech
11. COMPANY PROFILES: mRNA VACCINE DEVELOPERS BASED IN ASIA-PACIFIC
- 11.1. Chapter Overview
- 11.2. Leading Developers in mRNA Vaccines Market based in North America
- 11.2.1. Suzhou Abogen Biosciences
- 11.2.1.1. Company Overview
- 11.2.1.2. mRNA Vaccines Portfolio
- 11.2.1.3. Recent Developments and Future Outlook
- 11.2.2. Gennova Biopharmaceuticals
- 11.2.2.1. Company Overview
- 11.2.2.2. Financial Information
- 11.2.2.3. mRNA Vaccines Portfolio
- 11.2.2.4. Recent Developments and Future Outlook
- 11.2.3. RNACure
- 11.2.3.1. Company Overview
- 11.2.3.2. mRNA Vaccines Portfolio
- 11.2.3.3. Recent Developments and Future Outlook
- 11.2.4. Walvax
- 11.2.4.1. Company Overview
- 11.2.4.2. Financial Information
- 11.2.4.3. mRNA Vaccines Portfolio
- 11.2.4.4. Recent Developments and Future Outlook
- 11.2.1. Suzhou Abogen Biosciences
12. BIG PHARMA INITIATIVES
- 12.1. Chapter Overview
- 12.2. Scope and Methodology
- 12.3. mRNA Vaccines Market: Big Player Initiatives
- 12.3.1. Analysis by Year of Initiative
- 12.3.2. Analysis by Type of Initiative
- 12.3.3. Analysis by Year and Type of Initiative
- 12.3.4. Analysis by Type of Partnership
- 12.3.5. Analysis by Type of Expansion
- 12.3.6. Analysis by Year of Initiative and Company
- 12.3.7. Big Pharma Players: Analysis by Number of Initiatives
- 12.4. Benchmarking Analysis: Big Pharma Players
- 12.4.1. Spider Web Analysis: Bayer
- 12.4.2. Spider Web Analysis: Pfizer
- 12.4.3. Spider Web Analysis: Sanofi
- 12.5. Concluding Remarks
13. START-UP HEALTH INDEXING
- 13.1. Chapter Overview
- 13.2. Start-ups focused on mRNA Vaccines
- 13.3. Benchmarking of Start-ups
- 13.4. Startup-Health Indexing
- 13.4.1. Analysis by Location of Headquarters
- 13.4.2. Analysis by Company Strength
- 13.4.3. Analysis by Pipeline Maturity
- 13.4.4. Analysis by Pipeline Strength
- 13.4.5. Analysis by Financial Support
- 13.4.6. Analysis by Investor Strength
- 13.4.7. Analysis by Partnership Activity
- 13.4.8. Start-ups Health Indexing: Roots Analysis Perspective
14. CLINICAL TRIAL ANALYSIS
- 14.1. Chapter Overview
- 14.2. Scope and Methodology
- 14.3. mRNA Vaccines: Clinical Trial Analysis
- 14.3.1. Analysis by Trial Registration Year
- 14.3.2. Analysis of Number of Patients Enrolled by Trial Registration Year
- 14.3.3. Analysis by Trial Phase
- 14.3.4. Analysis of Number of Patients Enrolled by Trial Phase
- 14.3.5. Analysis by Trial Status
- 14.3.6. Analysis by Trial Registration Year and Trial Status
- 14.3.7. Analysis by Patient Gender
- 14.3.8. Analysis by Study Design
- 14.3.8.1. Analysis by Type of Allocation
- 14.3.8.2. Analysis by Type of Intervention Model
- 14.3.8.3. Analysis by Type of Masking
- 14.3.8.4. Analysis by Trial Purpose
- 14.3.9. Analysis by Type of Sponsor / Collaborator
- 14.3.10. Analysis by Geography
- 14.3.10.1. Analysis of Clinical Trials by Geography
- 14.3.10.2. Analysis of Clinical Trials by Geography and Trial Status
- 14.3.10.3. Analysis of Patients Enrolled by Geography and Trial Status
15. PARTNERSHIPS AND COLLABORATIONS
- 15.1. Chapter Overview
- 15.2. Partnership Models
- 15.3. mRNA Vaccines Market: Partnerships and Collaborations
- 15.3.1. Analysis by Year of Partnership
- 15.3.2. Analysis by Type of Partnership
- 15.3.3. Analysis by Year and Type of Partnership
- 15.3.4. Analysis by Therapeutic Area
- 15.3.5. Most Active Players: Analysis by Number of Partnerships
- 15.3.6. Analysis by Geography
- 15.3.6.1. Intercontinental and Intracontinental Agreements
- 15.3.6.2. Local and International Agreements
16. FUNDING AND INVESTMENTS
- 16.1. Chapter Overview
- 16.2. Funding Models
- 16.3. mRNA Vaccines Market: Funding and Investment Analysis
- 16.3.1. Analysis by Year of Funding
- 16.3.1.1. Cumulative Year-wise Trend of Funding Instances
- 16.3.1.2. Cumulative Year-wise Trend of Amount Invested
- 16.3.2. Analysis by Type of Funding
- 16.3.2.1. Analysis of Funding Instances
- 16.3.2.2. Analysis of Amount Invested
- 16.3.3. Analysis by Year and Type of Funding
- 16.3.4. Analysis by Amount Raised by Year and Type of Funding
- 16.3.5. Analysis by Therapeutic Area
- 16.3.6. Most Active Players: Analysis by Number of Funding Instances
- 16.3.7. Most Active Players: Analysis by Amount Raised
- 16.3.8. Analysis by Geography
- 16.3.9. Most Active Players: Analysis by Number of Funding Instances
- 16.3.10. Most Active Players: Analysis by Amount Invested
- 16.3.1. Analysis by Year of Funding
- 16.4. Summary of Funding and Investments
17. PATENT ANALYSIS
- 17.1. Chapter Overview
- 17.2. Scope and Methodology
- 17.3. mRNA Vaccines: Patent Analysis
- 17.3.1. Analysis by Type of Patent
- 17.3.2. Analysis by Patent Publication Year
- 17.3.3. Analysis by Type of Patent and Publication Year
- 17.3.4. Analysis by Patent Application Year
- 17.3.5. Analysis by Patent Jurisdiction
- 17.3.6. Analysis by CPC Symbols
- 17.3.7. Analysis by Type of Applicant
- 17.3.8. Leading Industry Players: Analysis by Number of Patents
- 17.3.9. Leading Non-Industry Players: Analysis by Number of Patents
- 17.3.10. Leading Inventors: Analysis by Number of Patents
- 17.4. Patent Benchmarking Analysis
- 17.4.1. Analysis of Patent Characteristics
- 17.5. Patent Valuation
- 17.6. Leading Patents by Number of Citations
18. FDA APPROVAL STRATEGIES
- 18.1. Chapter Overview
- 18.2. Methodology
- 18.3. Key Parameters
- 18.4. General Reasons for Failure of Trials Focused on mRNA Vaccines
- 18.5. Benchmarking Analysis: Distribution of Key Strategies by mRNA Vaccines
19 OUTSOURCING: GO / NO-GO FRAMEWORK
- 19.1. Chapter Overview
- 19.2. Outsourcing: Go / No-Go Framework
- 19.3. mRNA Vaccines Outsourcing: Go / No-Go Framework
- 19.3.1. Key Parameters and Assumptions
- 19.3.2. Methodology
- 19.3.3. Results and Interpretations
- 19.3.3.1. Outsourcing: Go / No-Go Framework for Small Companies
- 19.3.3.2. Outsourcing: Go / No-Go Framework for Mid-Sized Companies
- 19.3.3.3. Outsourcing: Go / No-Go Framework for Large Companies
20. MARKET IMPACT ANALYSIS
- 20.1. Chapter Overview
- 20.2. Market Drivers
- 20.3. Market Restraints
- 20.4. Market Opportunities
- 20.5. Market Challenges
- 20.6. Conclusion
21. GLOBAL mRNA VACCINES MARKET
- 21.1. Chapter Overview
- 21.2. Assumptions and Methodology
- 21.3. Global mRNA Vaccines Market, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 21.3.1. Scenario Analysis
- 21.3.1.1. Conservative Scenario
- 21.3.1.2. Optimistic Scenario
- 21.3.1. Scenario Analysis
- 21.4. Key Market Segmentations
22. mRNA VACCINES MARKET, BY TARGET INDICATION
- 22.1. Chapter Overview
- 22.2. Key Assumptions and Methodology
- 22.3. mRNA Vaccines Market: Distribution by Target Indication
- 22.3.1. mRNA Vaccines Market for RSV Infection, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 22.3.2. mRNA Vaccines Market for Metastatic / R/ R Head and Neck Cancer, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 22.3.3. mRNA Vaccines Market for Influenza, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 22.3.4. mRNA Vaccines Market for Norovirus Acute Gastroenteritis, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 22.3.5. mRNA Vaccines Market for Mononucleosis, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 22.4. Data Triangulation and Validation
23. mRNA VACCINES MARKET, BY GEOGRAPHICAL REGIONS
- 23.1. Chapter Overview
- 23.2. Key Assumptions and Methodology
- 23.3. mRNA Vaccines Market: Distribution by Geographical Regions
- 23.3.1. mRNA Vaccines Market in North America, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 23.3.1.1. mRNA Vaccines Market in the US, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 23.3.1.2. mRNA Vaccines Market in Canada, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 23.3.2. mRNA Vaccines Market in Europe, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 23.3.2.1. mRNA Vaccines Market in Germany, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 23.3.2.2. mRNA Vaccines Market in the France, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 23.3.2.3. mRNA Vaccines Market in Italy, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 23.3.2.4. mRNA Vaccines Market in UK, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 23.3.2.5. mRNA Vaccines Market in Spain, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 23.3.2.6. mRNA Vaccines Market in Rest of Europe, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 23.3.3. mRNA Vaccines Market in Asia-Pacific, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 23.3.3.1. mRNA Vaccines Market in China, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 23.3.3.2. mRNA Vaccines Market in Japan, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 23.3.3.3. mRNA Vaccines Market in Australia, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 23.3.3.4. mRNA Vaccines Market in South Korea, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 23.3.4. Penetration Growth (P-G) Matrix
- 23.3.5. Market Movement Analysis
- 23.3.1. mRNA Vaccines Market in North America, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 23.4. Data Triangulation and Validation
24. MARKET OPPORTUNITY ANALYSIS: NORTH AMERICA
- 24.1. mRNA Vaccines Market in North America: Distribution by Target Indication
- 24.1.1. mRNA Vaccines Market in North America for RSV Infection, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 24.1.2. mRNA Vaccines Market in North America for Metastatic / R/ R Head and Neck Cancer, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 24.1.3. mRNA Vaccines Market in North America for Influenza, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 24.1.4. mRNA Vaccines Market in North America for Norovirus Acute Gastroenteritis, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 24.1.5. mRNA Vaccines Market in North America for Mononucleosis, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
25. MARKET OPPORTUNITY ANALYSIS: EUROPE
- 25.1. mRNA Vaccines Market in Europe: Distribution by Target Indication
- 25.1.1. mRNA Vaccines Market in Europe for RSV Infection, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 25.1.2. mRNA Vaccines Market in Europe for Metastatic / R/ R Head and Neck Cancer, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 25.1.3. mRNA Vaccines Market in Europe for Influenza, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 25.1.4. mRNA Vaccines Market in Europe for Norovirus Acute Gastroenteritis, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 25.1.5. mRNA Vaccines Market in Europe for Mononucleosis, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
26. MARKET OPPORTUNITY ANALYSIS: ASIA-PACIFIC
- 26.1. mRNA Vaccines Market in Asia-Pacific: Distribution by Target Indication
- 26.1.1. mRNA Vaccines Market in Asia-Pacific for RSV Infection, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 26.1.2. mRNA Vaccines Market in Asia-Pacific for Metastatic / R/ R Head and Neck Cancer, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 26.1.3. mRNA Vaccines Market in Asia-Pacific for Influenza, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 26.1.4. mRNA Vaccines Market in Asia-Pacific for Norovirus Acute Gastroenteritis, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- 26.1.5. mRNA Vaccines Market in Asia-Pacific for Mononucleosis, Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
27. CONCLUDING REMARKS
28. EXECUTIVE INSIGHTS
- 28.1. Chapter Overview
- 28.2. Company A
- 28.2.1. Company Snapshot
- 28.2.2. Interview Transcript: Business Development Manager
- 28.3. Company B
- 28.3.1. Company Snapshot
- 28.3.2. Interview Transcript: Senior Director, Business Development
- 28.4. Company C
- 28.4.1. Company Snapshot
- 28.4.2. Interview Transcript: Team Leader
- 28.5. Company D
- 28.5.1. Company Snapshot
- 28.5.2. Interview Transcript: Director of Advanced Drug Delivery
- 28.6. Company E
- 28.6.1. Company Snapshot
- 28.6.2. Interview Transcript: Deputy Director
- 28.7. Company F
- 28.7.1. Company Snapshot
- 28.7.2. Interview Transcript: Co-founder and Chief Executive Officer
- 28.8. Company G
- 28.8.1. Company Snapshot
- 28.8.2. Interview Transcript: Co-founder
- 28.9. Company H
- 28.9.1. Company Snapshot
- 28.9.2. Interview Transcript: Chief Executive Officer
- 28.10. Company I
- 28.10.1. Company Snapshot
- 28.10.2. Interview Transcript: Chief Executive Officer
- 28.11. Company J
- 28.11.1. Company Snapshot
- 28.11.2. Interview Transcript: Chief Executive Officer
- 28.12. Company K
- 28.12.1. Company Snapshot
- 28.12.2. Interview Transcript: Chief Executive Officer
- 28.13. Company L
- 28.13.1. Company Snapshot
- 28.13.2. Interview Transcript: President
- 28.14. Company M
- 28.14.1. Company Snapshot
- 28.14.2. Interview Transcript: Medical Professional
29. APPENDIX 1: TABULATED DATA
30. APPENDIX 2: LIST OF COMPANIES AND ORGANIZATIONS
List of Tables
- Table 6.1 Differences Between Catheter Ablation and Surgical Ablation
- Table 6.2 Types Of Catheter Ablation Techniques: Information on Mechanism Of Action, Advantages And Disadvantages
- Table 7.1 List Of Pulsed Field Ablation Devices
- Table 7.2 Pulsed Field Ablation Devices: Information On Shape Of Catheter, Configuration Of Catheter And Type Of Catheter (By Irrigation)
- Table 7.3 Pulsed Field Ablation Devices: Information On Catheter Shaft Diameter, Number Of Electrodes And Electrical Polarity
- Table 7.4 Pulsed Field Ablation Devices: Information On Source Of Ablation, Status Of Development, Phase Of Development Of Investigational Devices And Application
- Table 7.5 Pulsed Field Ablation Devices: Information On Nct Number And Location Of Clinical Trial
- Table 7.6 Pulsed Field Ablation Devices: Information On Target Indication And Target Therapeutic Area
- Table 7.7 List Of Pulsed Field Ablation Device Developers
- Table 9.1 Leading Developers Of Pulsed Field Ablation Systems
- Table 9.2 Boston Scientific: Company Snapshot
- Table 9.3 Boston Scientific: Pulsed Field Ablation Portfolio
- Table 9.4 Boston Scientific: Recent Developments And Future Outlook
- Table 9.5 Medtronic: Company Snapshot
- Table 9.6 Medtronic: Pulsed Field Ablation Portfolio
- Table 9.7 Medtronic: Recent Developments And Future Outlook
- Table 9.8 Galvanize Therapeutics: Company Snapshot
- Table 9.9 Galvanize Therapeutics: Pulsed Field Ablation Portfolio
- Table 9.10 Galvanize Therapeutics: Recent Developments And Future Outlook
- Table 9.11 Pulse Biosciences: Company Snapshot
- Table 9.12 Pulse Biosciences: Pulsed Field Ablation Portfolio
- Table 9.13 Pulse Biosciences: Recent Developments And Future Outlook
- Table 9.14 Angiodynamics: Company Snapshot
- Table 9.15 Angiodynamics: Pulsed Field Ablation Portfolio
- Table 9.16 Angiodynamics: Recent Developments And Future Outlook
- Table 9.17 Biosense Webster: Company Snapshot
- Table 9.18 Biosense Webster: Pulsed Field Ablation Portfolio
- Table 9.19 Biosense Webster: Recent Developments And Future Outlook
- Table 9.20 Acutus Medical: Company Snapshot
- Table 9.21 Acutus Medical: Pulsed Field Ablation Portfolio
- Table 9.22 Acutus Medical: Recent Developments And Future Outlook
- Table 9.23 Kardium: Company Snapshot
- Table 9.24 Kardium: Pulsed Field Ablation Portfolio
- Table 9.25 Kardium: Recent Developments And Future Outlook
- Table 10.1 Abbott: Company Snapshot And Product Portfolio
- Table 10.2 Accupulse Medical: Company Snapshot And Product Portfolio
- Table 10.3 Arga Medtech: Company Snapshot And Product Portfolio
- Table 10.4 Atrian Medical: Company Snapshot And Product Portfolio
- Table 10.5 Aurigen Medical: Company Snapshot And Product Portfolio
- Table 10.6 Cathrx: Company Snapshot And Product Portfolio
- Table 10.7 Electrophysiology Frontiers: Company Snapshot And Product Portfolio
- Table 10.8 Enchannel Medical: Company Snapshot And Product Portfolio
- Table 10.9 Hangzhou Dinova Ep Technology: Company Snapshot And Product Portfolio
- Table 10.10 Mirai Medical: Company Snapshot And Product Portfolio
- Table 10.11 Tianjin Intelligent Health Medical: Company Snapshot And Product Portfolio
- Table 11.1 Pulsed Field Ablation: List Of Partnerships And Collaborations
- Table 11.2 Pulsed Field Ablation: List Of Funding And Investments
- Table 12.1 Patent Analysis: Top Cpc Sections
- Table 12.2 Patent Analysis: Top Cpc Symbols
- Table 12.3 Patent Analysis: Top Cpc Codes
- Table 12.4 Patent Analysis: Summary Of Benchmarking Analysis
- Table 12.5 Patent Analysis: Categorization Based On Weighted Valuation Scores
- Table 12.6 Patent Analysis: List Of Leading Patents (By Number Of Citations)
- Table 13.1 Pulsed Field Ablation: List Of Global Events
- Table 14.1 List Of Cardiac Mapping And Navigation Device Developers
- Table 14.2 Likely Partner Analysis: Cardiac Mapping And Navigation Device Developers
- Table 33.1 Pulsed Field Ablation Devices: Distribution By Product Components
- Table 33.2 Pulsed Field Ablation Devices: Distribution By Shape Of Catheter
- Table 33.3 Pulsed Field Ablation Devices: Distribution By Configuration Of Catheter
- Table 33.4 Pulsed Field Ablation Devices: Distribution By Type Of Catheter (By Irrigation)
- Table 33.5 Pulsed Field Ablation Devices: Distribution By Catheter Shaft Diameter (In Fr)
- Table 33.6 Pulsed Field Ablation Devices: Distribution By Number Of Electrodes
- Table 33.7 Pulsed Field Ablation Devices: Distribution By Electrical Polarity
- Table 33.8 Pulsed Field Ablation Devices: Distribution By Source Of Ablation
- Table 33.9 Pulsed Field Ablation Devices: Distribution By Status Of Development
- Table 33.10 Pulsed Field Ablation Devices: Distribution By Status Of Development And Location Of Clinical Trial
- Table 33.11 Pulsed Field Ablation Devices: Distribution By Application Area
- Table 33.12 Pulsed Field Ablation Devices: Distribution By Target Therapeutic Area And Target Indication
- Table 33.13 Pulsed Field Ablation Devices: Distribution By Status Of Development And Target Therapeutic Area
- Table 33.14 Pulsed Field Ablation Devices: Distribution By Location Of Clinical Trial And Target Therapeutic Area
- Table 33.15 Pulsed Field Ablation Devices: Distribution By Source Of Ablation, Application Area And Target Therapeutic Area
- Table 33.16 Pulsed Field Ablation Device Developers: Distribution By Year Of Establishment
- Table 33.17 Pulsed Field Ablation Device Developers: Distribution By Company Size
- Table 33.18 Pulsed Field Ablation Device Developers: Distribution By Location Of Headquarters (Region)
- Table 33.19 Pulsed Field Ablation Device Developers: Distribution By Location Of Headquarters (Country)
- Table 33.20 Pulsed Field Ablation Device Developers: Distribution By Company Size And Location Of Headquarters (Region)
- Table 33.21 Pulsed Field Ablation Device Developers: Distribution By Type Of Developer
- Table 33.22 Pulsed Field Ablation Device Developers: Distribution By Company Ownership
- Table 33.23 Pulsed Field Ablation Device Developers: Distribution By Company Ownership And Location Of Headquarters (Region)
- Table 33.24 Most Active Players: Distribution By Number Of Products
- Table 33.25 Product Competitiveness Analysis: Pulsed Field Ablation Devices Offered By Players Based In North America
- Table 33.26 Product Competitiveness Analysis: Pulsed Field Ablation Devices Offered By Players Based In Europe
- Table 33.27 Product Competitiveness Analysis: Pulsed Field Ablation Devices Offered By Players Based In Asia-Pacific
- Table 33.28 Product Competitiveness Analysis Of Pulsed Field Ablation Devices: Competitiveness Score Of Top Products
- Table 33.29 Boston Scientific: Financial Information
- Table 33.30 Medtronic: Financial Information
- Table 33.31 Angiodynamics: Financial Information
- Table 33.32 Acutus Medical: Financial Information
- Table 33.33 Partnerships And Collaborations: Cumulative Year-Wise Trend, Since 2022
- Table 33.34 Partnerships And Collaborations: Distribution By Type Of Partnership
- Table 33.35 Partnerships And Collaborations: Distribution By Year And Type Of Partnership
- Table 33.36 Partnerships And Collaborations: Distribution By Type Of Product
- Table 33.37 Partnerships And Collaborations: Distribution By Type Of Partnership And Type Of Product
- Table 33.38 Partnerships And Collaborations: Distribution By Therapeutic Area
- Table 33.39 Partnerships And Collaborations: Distribution By Type Of Partnership And Therapeutic Area
- Table 33.40 Most Active Players: Distribution By Number Of Partnerships
- Table 33.41 Partnerships And Collaborations: Intercontinental And Intracontinental Agreements
- Table 33.42 Partnerships And Collaborations: Local And International Agreements
- Table 33.43 Funding And Investments: Cumulative Year-Wise Trend Of Funding Instances, Since 2022
- Table 33.44 Funding And Investments: Cumulative Year-Wise Trend Of Amount Invested, Since 2022
- Table 33.45 Funding And Investments: Distribution Of Funding Instances By Type Of Funding
- Table 33.46 Funding And Investments: Distribution Of Amount Invested By Type Of Funding (USD Million)
- Table 33.47 Funding And Investments: Distribution Of Funding Instances By Year And Type Of Funding
- Table 33.48 Funding And Investments: Distribution Of Amount Invested By Year And Type Of Funding (USD Million)
- Table 33.49 Funding And Investments: Distribution Of Funding Instances And Amount Invested By Therapeutic Area
- Table 33.50 Most Active Players: Distribution By Funding Instances
- Table 33.51 Most Active Players: Distribution By Amount Raised
- Table 33.52 Leading Investors: Distribution By Funding Instances
- Table 33.53 Funding And Investments: Distribution Of Funding Instances And Amount Invested By Geography
- Table 33.54 Patent Analysis: Distribution By Type Of Patent
- Table 33.55 Patent Analysis: Cumulative Year-Wise Trend By Patent Application Year, Since 2022
- Table 33.56 Patent Analysis: Cumulative Year-Wise Trend By Patent Publication Year, Since 2022
- Table 33.57 Patent Analysis: Distribution By Type Of Patent And Patent Publication Year
- Table 33.58 Patent Analysis: Distribution By Publication Time
- Table 33.59 Patent Analysis: Distribution By Patent Jurisdiction
- Table 33.60 Patent Analysis: Distribution By Type Of Applicant
- Table 33.61 Patent Analysis: Distribution By Patent Age
- Table 33.62 Leading Players: Distribution By Number Of Patents
- Table 33.63 Leading Patent Assignees: Distribution By Number Of Patents
- Table 33.64 Patent Benchmarking Analysis: Distribution Of Leading Industry Players By Patent Characteristics (Cpc Codes)
- Table 33.65 Patent Benchmarking Analysis: Distribution Of Publication Time By Patent Characteristics (Cpc Codes)
- Table 33.66 Pulsed Field Ablation: Patent Valuation
- Table 33.67 Global Events Analysis: Cumulative Year-Wise Trend, Since 2018
- Table 33.68 Global Events Analysis: Distribution By Type Of Event
- Table 33.69 Global Events Analysis: Distribution By Year And Type Of Event
- Table 33.70 Global Events Analysis: Distribution By Event Platform
- Table 33.71 Global Events Analysis: Distribution By Location Of Event (Region)
- Table 33.72 Global Events Analysis: Distribution By Location Of Event (Country)
- Table 33.73 Word Cloud Analysis: Evolutionary Trends In Event Agenda / Key Focus Areas
- Table 33.74 Most Active Event Organizers: Distribution By Number Of Events
- Table 33.75 Most Active Participants: Distribution By Number Of Events
- Table 33.76 Most Active Speakers: Distribution By Number Of Events
- Table 33.77 Distribution By Designations Of Speakers
- Table 33.78 Cardiac Mapping And Navigation Device Developers: Distribution By Year Of Establishment
- Table 33.79 Cardiac Mapping And Navigation Device Developers: Distribution By Company Size
- Table 33.80 Cardiac Mapping And Navigation Device Developers: Distribution By Location Of Headquarters (Region)
- Table 33.81 Cardiac Mapping And Navigation Device Developers: Distribution By Location Of Headquarters (Country)
- Table 33.82 Cardiac Mapping And Navigation Device Developers: Likely Partners Of Cardiac Pulsed Field Ablation Device Developers
- Table 33.83 Global Pulsed Field Ablation Market, Historical Trends (Since 2018) And Future Estimates (Till 2035) (USD Million)
- Table 33.84 Global Pulsed Field Ablation Market, Forecasted Estimates (Till 2035), Scenario I (USD Million)
- Table 33.85 Global Pulsed Field Ablation Market, Forecasted Estimates (Till 2035), Scenario II (USD Million)
- Table 33.86 Global Pulsed Field Ablation Market, Forecasted Estimates (Till 2035), Scenario III (USD Million)
- Table 33.87 Pulsed Field Ablation Market: Distribution By Geography
- Table 33.88 Pulsed Field Ablation Market In North America, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.89 Pulsed Field Ablation Market In Europe, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.90 Pulsed Field Ablation Market In Asia-Pacific, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.91 Pulsed Field Ablation Market: Distribution By Therapeutic Area
- Table 33.92 Pulsed Field Ablation Market For Cardiovascular Disorders, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.93 Pulsed Field Ablation Market For Oncological Disorders, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.94 Pulsed Field Ablation Market For Respiratory Disorders, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.95 Pulsed Field Ablation Market For Dermatological Disorders, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.96 Pulsed Field Ablation Market: Distribution By Product Components
- Table 33.97 Pulsed Field Ablation Market For Catheters, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.98 Pulsed Field Ablation Market For Generators, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.99 Pulsed Field Ablation Market For Cardiovascular Disorders: Distribution By Product Components
- Table 33.100 Pulsed Field Ablation Market For Cardiovascular Disorders Using Catheters, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.101 Pulsed Field Ablation Market For Cardiovascular Disorders Using Generators, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.102 Pulsed Field Ablation Market For Cardiovascular Disorders: Distribution By Application Area
- Table 33.103 Pulsed Field Ablation Market For Cardiovascular Disorders Using Ablation Devices, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035)
- Table 33.104 Pulsed Field Ablation Market For Cardiovascular Disorders Using Ablation And Mapping Devices, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.105 Pulsed Field Ablation Market For Cardiovascular Disorders: Distribution By Source Of Ablation
- Table 33.106 Pulsed Field Ablation Market For Cardiovascular Disorders Using Pf Energy-Based Devices, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.107 Pulsed Field Ablation Market For Cardiovascular Disorders Using Pf And Rf Energy-Based Devices, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.108 Pulsed Field Ablation Market For Cardiovascular Disorders Using Pf And Cryo Energy-Based Devices, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.109 Pulsed Field Ablation Market For Cardiovascular Disorders: Distribution By Geography
- Table 33.110 Pulsed Field Ablation Market For Cardiovascular Disorders In North America, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.111 Pulsed Field Ablation Market For Cardiovascular Disorders In Us, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.112 Pulsed Field Ablation Market For Cardiovascular Disorders In Us: Distribution By Product Components, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.113 Pulsed Field Ablation Market For Cardiovascular Disorders In Us: Distribution By Application Area, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.114 Pulsed Field Ablation Market For Cardiovascular Disorders In Us: Distribution By Source Of Ablation, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.115 Pulsed Field Ablation Market For Cardiovascular Disorders In Canada, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.116 Pulsed Field Ablation Market For Cardiovascular Disorders In Canada: Distribution By Product Components, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.117 Pulsed Field Ablation Market For Cardiovascular Disorders In Canada: Distribution By Application Area, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.118 Pulsed Field Ablation Market For Cardiovascular Disorders In Canada: Distribution By Source Of Ablation, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.119 Pulsed Field Ablation Market For Cardiovascular Disorders In Europe, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.120 Pulsed Field Ablation Market For Cardiovascular Disorders In Europe: Distribution By Product Components, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.121 Pulsed Field Ablation Market For Cardiovascular Disorders In Europe: Distribution By Application Area, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.122 Pulsed Field Ablation Market For Cardiovascular Disorders In Europe: Distribution By Source Of Ablation, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.123 Pulsed Field Ablation Market For Cardiovascular Disorders In Asia-Pacific, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.124 Pulsed Field Ablation Market For Cardiovascular Disorders In China, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.125 Pulsed Field Ablation Market For Cardiovascular Disorders In China: Distribution By Product Components, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.126 Pulsed Field Ablation Market For Cardiovascular Disorders In China: Distribution By Application Area, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.127 Pulsed Field Ablation Market For Cardiovascular Disorders In China: Distribution By Source Of Ablation, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.128 Pulsed Field Ablation Market For Cardiovascular Disorders In Japan, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.129 Pulsed Field Ablation Market For Cardiovascular Disorders In Japan: Distribution By Product Components, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.130 Pulsed Field Ablation Market For Cardiovascular Disorders In Japan: Distribution By Application Area, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.131 Pulsed Field Ablation Market For Cardiovascular Disorders In Japan: Distribution By Source Of Ablation, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.132 Pulsed Field Ablation Market For Oncological Disorders: Distribution By Geography
- Table 33.133 Pulsed Field Ablation Market For Oncological Disorders In North America, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.134 Pulsed Field Ablation Market For Oncological Disorders In Europe, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.135 Pulsed Field Ablation Market For Oncological Disorders In Asia-Pacific, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.136 Pulsed Field Ablation Market For Oncological Disorders: Distribution By Product Components
- Table 33.137 Pulsed Field Ablation Market For Oncological Disorders Using Catheters, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.138 Pulsed Field Ablation Market For Oncological Disorders Using Generators, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.139 Pulsed Field Ablation Market For Oncological Disorders: Distribution By Type Of Cancer
- Table 33.140 Pulsed Field Ablation Market For Soft-Tissue Ablative Cancers, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.141 Pulsed Field Ablation Market For Pancreatic Cancer, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.142 Pulsed Field Ablation Market For Prostate Cancer, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.143 Pulsed Field Ablation Market For Non-Small Cell Lung Cancer, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.144 Pulsed Field Ablation Market For Esophageal Cancer, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.145 Pulsed Field Ablation Market For Respiratory Disorders: Distribution By Geography
- Table 33.146 Pulsed Field Ablation Market For Respiratory Disorders In North America, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.147 Pulsed Field Ablation Market For Respiratory Disorders In Europe, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.148 Pulsed Field Ablation Market For Respiratory Disorders In Asia-Pacific, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.149 Pulsed Field Ablation Market For Respiratory Disorders: Distribution By Product Components
- Table 33.150 Pulsed Field Ablation Market For Respiratory Disorders Using Catheters, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.151 Pulsed Field Ablation Market For Respiratory Disorders Using Generators, Historical Trends (Since 2018) And Forecasted Estimates (Till 2035) (USD Million)
- Table 33.152 Boston Scientific: Pulsed Field Ablation Sales Forecast (Till 2035) (USD Million)
- Table 33.153 Medtronic: Pulsed Field Ablation Sales Forecast (Till 2035) (USD Million)
- Table 33.154 Galvanize Therapeutics: Pulsed Field Ablation Sales Forecast (Till 2035) (USD Million)
- Table 33.155 Angiodynamics: Pulsed Field Ablation Sales Forecast (Till 2035) (USD Million)
List of Figures
- Figure 2.1 Research Methodology: Project Methodology
- Figure 2.2 Research Methodology: Data Sources for Secondary Research
- Figure 2.3 Research Methodology: Robust Quality Control
- Figure 3.1 Market Dynamics: Forecast Methodology
- Figure 3.2 Market Dynamics: Market Assessment Framework
- Figure 4.1 Lessons Learnt from Past Recessions
- Figure 5.1 Executive Summary: Market Landscape
- Figure 5.2 Executive Summary: Recent Developments and Initiatives
- Figure 5.3 Executive Summary: Patent Analysis
- Figure 5.4 Executive Summary: Global Events Analysis
- Figure 5.5 Executive Summary: Market Forecast and Opportunity Analysis
- Figure 6.1 Types of Ablation Techniques
- Figure 6.2 Steps Involved in Pulsed Field Ablation
- Figure 6.3 Various Parameters related to Ablative Energy Delivery
- Figure 6.4 Historical Evolution of Pulsed Field Ablation Therapy
- Figure 6.5 Mechanism of Action: Steps of Irreversible Electroporation
- Figure 6.6 Advantages of Pulsed Field Ablation
- Figure 7.1 Pulsed Field Ablation Devices: Distribution by Product Components
- Figure 7.2 Pulsed Field Ablation Devices: Distribution by Shape of Catheter
- Figure 7.3 Pulsed Field Ablation Devices: Distribution by Configuration of Catheter
- Figure 7.4 Pulsed Field Ablation Devices: Distribution by Type of Catheter (by Irrigation)
- Figure 7.5 Pulsed Field Ablation Devices: Distribution by Catheter Shaft Diameter (in Fr)
- Figure 7.6 Pulsed Field Ablation Devices: Distribution by Number of Electrodes
- Figure 7.7 Pulsed Field Ablation Devices: Distribution by Electrical Polarity
- Figure 7.8 Pulsed Field Ablation Devices: Distribution by Source of Ablation
- Figure 7.9 Pulsed Field Ablation Devices: Distribution by Status of Development
- Figure 7.10 Pulsed Field Ablation Devices: Distribution by Status of Development and Location of Clinical Trial
- Figure 7.11 Pulsed Field Ablation Devices: Distribution by Application Area
- Figure 7.12 Pulsed Field Ablation Devices: Distribution by Target Therapeutic Area and Target Indication
- Figure 7.13 Pulsed Field Ablation Devices: Distribution by Status of Development and Target Therapeutic Area
- Figure 7.14 Pulsed Field Ablation Devices: Distribution by Location of Clinical Trial and Target Therapeutic Area
- Figure 7.15 Pulsed Field Ablation Devices: Distribution by Source of Ablation, Application Area and Target Therapeutic Area
- Figure 7.16 Pulsed Field Ablation Device Developers: Distribution by Year of Establishment
- Figure 7.17 Pulsed Field Ablation Device Developers: Distribution by Company Size
- Figure 7.18 Pulsed Field Ablation Device Developers: Distribution by Location of Headquarters (Region)
- Figure 7.19 Pulsed Field Ablation Device Developers: Distribution by Location of Headquarters (Country)
- Figure 7.20 Pulsed Field Ablation Device Developers: Distribution by Company Size and Location of Headquarters (Region)
- Figure 7.21 Pulsed Field Ablation Device Developers: Distribution by Type of Developer
- Figure 7.22 Pulsed Field Ablation Device Developers: Distribution by Company Ownership
- Figure 7.23 Pulsed Field Ablation Device Developers: Distribution by Company Ownership and Location of Headquarters (Region)
- Figure 7.24 Most Active Players: Distribution by Number of Products
- Figure 8.1 Product Competitiveness Analysis: Pulsed Field Ablation Devices Offered by Players based in North America
- Figure 8.2 Product Competitiveness Analysis: Pulsed Field Ablation Devices Offered by Players based in Europe
- Figure 8.3 Product Competitiveness Analysis: Pulsed Field Ablation Devices Offered by Players based in Asia-Pacific
- Figure 8.4 Product Competitiveness Analysis of Pulsed Field Ablation Devices: Competitiveness Score of Top Products
- Figure 9.1 Boston Scientific: Financial Information
- Figure 9.2 Medtronic: Financial Information
- Figure 9.3 AngioDynamics: Financial Information
- Figure 9.4 Acutus Medical: Financial Information
- Figure 11.1 Partnerships and Collaborations: Cumulative Year-wise Trend, Since 2022
- Figure 11.2 Partnerships and Collaborations: Distribution by Type of Partnership
- Figure 11.3 Partnerships and Collaborations: Distribution by Year and Type of Partnership
- Figure 11.4 Partnerships and Collaborations: Distribution by Type of Product
- Figure 11.5 Partnerships and Collaborations: Distribution by Type of Partnership and Type of Product
- Figure 11.6 Partnerships and Collaborations: Distribution by Therapeutic Area
- Figure 11.7 Partnerships and Collaborations: Distribution by Type of Partnership and Therapeutic Area
- Figure 11.8 Most Active Players: Distribution by Number of Partnerships
- Figure 11.9 Partnerships and Collaborations: Intercontinental and Intracontinental Agreements
- Figure 11.10 Partnerships and Collaborations: Local and International Agreements
- Figure 11.11 Funding and Investments: Cumulative Year-wise Trend of Funding Instances, Since 2022
- Figure 11.12 Funding and Investments: Cumulative Year-wise Trend of Amount Invested, Since 2022
- Figure 11.13 Funding and Investments: Distribution of Funding Instances by Type of Funding
- Figure 11.14 Funding and Investments: Distribution of Amount Invested by Type of Funding (USD Million)
- Figure 11.15 Funding and Investments: Distribution of Funding Instances by Year and Type of Funding
- Figure 11.16 Funding and Investments: Distribution of Amount Invested by Year and Type of Funding (USD Million)
- Figure 11.17 Funding and Investments: Distribution of Funding Instances and Amount Invested by Therapeutic Area
- Figure 11.18 Most Active Players: Distribution by Funding Instances
- Figure 11.19 Most Active Players: Distribution by Amount Raised
- Figure 11.20 Leading Investors: Distribution by Funding Instances
- Figure 11.21 Funding and Investments: Distribution of Funding Instances and Amount Invested by Geography
- Figure 12.1 Patent Analysis: Distribution by Type of Patent
- Figure 12.2 Patent Analysis: Cumulative Year-wise Trend by Patent Application Year, Since 2022
- Figure 12.3 Patent Analysis: Cumulative Year-wise Trend by Patent Publication Year, Since 2022
- Figure 12.4 Patent Analysis: Distribution by Type of Patent and Patent Publication Year
- Figure 12.5 Patent Analysis: Distribution by Publication Time
- Figure 12.6 Patent Analysis: Distribution by Patent Jurisdiction
- Figure 12.7 Patent Analysis: Distribution by Type of Applicant
- Figure 12.8 Patent Analysis: Distribution by Patent Age
- Figure 12.9 Leading Players: Distribution by Number of Patents
- Figure 12.10 Leading Patent Assignees: Distribution by Number of Patents
- Figure 12.11 Patent Benchmarking Analysis: Distribution of Patent Characteristics (CPC Codes) Leading Industry Players
- Figure 12.12 Patent Benchmarking Analysis: Distribution of Patent Characteristics (CPC Codes) by Publication Time
- Figure 12.13 Pulsed Field Ablation Devices: Patent Valuation
- Figure 13.1 Global Events Analysis: Cumulative Year-wise Trend, Since 2022
- Figure 13.2 Global Events Analysis: Distribution by Type of Event
- Figure 13.3 Global Events Analysis: Distribution by Year and Type of Event
- Figure 13.4 Global Events Analysis: Distribution by Event Platform
- Figure 13.5 Global Events Analysis: Distribution by Location of Event (Region)
- Figure 13.6 Global Events Analysis: Distribution by Location of Event (Country)
- Figure 13.7 Word Cloud Analysis: Evolutionary Trends in Event Agenda / Key Focus Areas
- Figure 13.8 Most Active Event Organizers: Distribution by Number of Events
- Figure 13.9 Most Active Players: Distribution by Number of Events
- Figure 13.10 Most Active Speakers: Distribution by Number of Events
- Figure 13.11 Distribution by Designations of Speakers
- Figure 14.1 Cardiac Mapping and Navigation Device Developers: Distribution by Year of Establishment
- Figure 14.2 Cardiac Mapping and Navigation Device Developers: Distribution by Company Size
- Figure 14.3 Cardiac Mapping and Navigation Device Developers: Distribution by Location of Headquarters (Region)
- Figure 14.4 Cardiac Mapping and Navigation Device Developers: Distribution by Location of Headquarters (Country)
- Figure 14.5 Cardiac Mapping and Navigation Device Developers: Likely Partners of Cardiac Pulsed Field Ablation Device Developers
- Figure 16.1 Global Pulsed Field Ablation Market, Historical Trends (Since 2018) and Future Estimates (Till 2035) (USD Million)
- Figure 16.2 Global Pulsed Field Ablation Market, Forecasted Estimates (Till 2035), Scenario I (USD Million)
- Figure 16.3 Global Pulsed Field Ablation Market, Forecasted Estimates (Till 2035), Scenario II (USD Million)
- Figure 16.4 Global Pulsed Field Ablation Market, Forecasted Estimates (Till 2035), Scenario III (USD Million)
- Figure 16.5 Global Pulsed Field Ablation Market (Dynamic Dashboard Snippet)
- Figure 17.1 Pulsed Field Ablation Market: Distribution by Geography
- Figure 17.2 Pulsed Field Ablation Market in North America, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million
- Figure 17.3 Pulsed Field Ablation Market in Europe, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 17.4 Pulsed Field Ablation Market in Asia-Pacific, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 17.5 Pulsed Field Ablation Market: Distribution by Geography (Dynamic Dashboard Snippet)
- Figure 18.1 Pulsed Field Ablation Market: Distribution by Therapeutic Area
- Figure 18.2 Pulsed Field Ablation Market for Cardiovascular Disorders, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 18.3 Pulsed Field Ablation Market for Oncological Disorders, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 18.4 Pulsed Field Ablation Market for Respiratory Disorders, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 18.5 Pulsed Field Ablation Market for Dermatological Disorders, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 18.6 Pulsed Field Ablation Market: Distribution by Therapeutic Area (Dynamic Dashboard Snippet)
- Figure 19.1 Pulsed Field Ablation Market: Distribution by Product Components
- Figure 19.2 Pulsed Field Ablation Market for Catheters, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 19.3 Pulsed Field Ablation Market for Generators, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 19.4 Pulsed Field Ablation Market: Distribution by Product Components (Dynamic Dashboard Snippet)
- Figure 20.1 Pulsed Field Ablation Market for Cardiovascular Disorders: Distribution by Product Components
- Figure 20.2 Pulsed Field Ablation Market for Cardiovascular Disorders using Catheters, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 20.3 Pulsed Field Ablation Market for Cardiovascular Disorders using Generators, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 20.4 Pulsed Field Ablation Market for Cardiovascular Disorders: Distribution by Product Components (Dynamic Dashboard Snippet)
- Figure 21.1 Pulsed Field Ablation Market for Cardiovascular Disorders: Distribution by Application Area
- Figure 21.2 Pulsed Field Ablation Market for Cardiovascular Disorders using Ablation Devices, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 21.3 Pulsed Field Ablation Market for Cardiovascular Disorders using Ablation and Mapping Devices, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 21.4 Pulsed Field Ablation Market for Cardiovascular Disorders: Distribution by Application Area (Dynamic Dashboard Snippet)
- Figure 22.1 Pulsed Field Ablation Market for Cardiovascular Disorders: Distribution by Source of Ablation
- Figure 22.2 Pulsed Field Ablation Market for Cardiovascular Disorders using PF Energy-based Devices, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 22.3 Pulsed Field Ablation Market for Cardiovascular Disorders using PF and RF Energy-based Devices, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 22.4 Pulsed Field Ablation Market for Cardiovascular Disorders using PF and Cryo Energy-based Devices, Historical Trends (Since 2018) and Forecasted Estimates(Till 2035) (USD Million)
- Figure 22.5 Pulsed Field Ablation Market for Cardiovascular Disorders: Distribution by Source of Ablation (Dynamic Dashboard Snippet)
- Figure 23.1 Pulsed Field Ablation Market for Cardiovascular Disorders: Distribution by Geography
- Figure 23.2 Pulsed Field Ablation Market for Cardiovascular Disorders in North America, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.3 Pulsed Field Ablation Market for Cardiovascular Disorders in US, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.4 Pulsed Field Ablation Market for Cardiovascular Disorders in US: Distribution by Product Components, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.5 Pulsed Field Ablation Market for Cardiovascular Disorders in US: Distribution by Application Area, Historical Trends (Since 2018) and Forecasted Estimates(Till 2035) (USD Million)
- Figure 23.6 Pulsed Field Ablation Market for Cardiovascular Disorders in US: Distribution by Source of Ablation, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.7 Pulsed Field Ablation Market for Cardiovascular Disorders in Canada, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.8 Pulsed Field Ablation Market for Cardiovascular Disorders in Canada: Distribution by Product Components, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.9 Pulsed Field Ablation Market for Cardiovascular Disorders in Canada: Distribution by Application Area, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.10 Pulsed Field Ablation Market for Cardiovascular Disorders in Canada: Distribution by Source of Ablation, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.11 Pulsed Field Ablation Market for Cardiovascular Disorders in Europe, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.12 Pulsed Field Ablation Market for Cardiovascular Disorders in Europe: Distribution by Product Components, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.13 Pulsed Field Ablation Market for Cardiovascular Disorders in Europe: Distribution by Application Area, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.14 Pulsed Field Ablation Market for Cardiovascular Disorders in Europe: Distribution by Source of Ablation, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.15 Pulsed Field Ablation Market for Cardiovascular Disorders in Asia-Pacific, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.16 Pulsed Field Ablation Market for Cardiovascular Disorders in China, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.17 Pulsed Field Ablation Market for Cardiovascular Disorders in China: Distribution by Product Components, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.18 Pulsed Field Ablation Market for Cardiovascular Disorders in China: Distribution by Application Area, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.19 Pulsed Field Ablation Market for Cardiovascular Disorders in China: Distribution by Source of Ablation, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.20 Pulsed Field Ablation Market for Cardiovascular Disorders in Japan, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.21 Pulsed Field Ablation Market for Cardiovascular Disorders in Japan: Distribution by Product Components, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.22 Pulsed Field Ablation Market for Cardiovascular Disorders in Japan: Distribution by Application Area, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.23 Pulsed Field Ablation Market for Cardiovascular Disorders in Japan: Distribution by Source of Ablation, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 23.24 Pulsed Field Ablation Market for Cardiovascular Disorders: Distribution by Region (Dynamic Dashboard Snippet)
- Figure 24.1 Pulsed Field Ablation Market for Oncological Disorders: Distribution by Geography
- Figure 24.2 Pulsed Field Ablation Market for Oncological Disorders in North America, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 24.3 Pulsed Field Ablation Market for Oncological Disorders in Europe, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 24.4 Pulsed Field Ablation Market for Oncological Disorders in Asia-Pacific, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 24.5 Pulsed Field Ablation Market for Oncological Disorders: Distribution by Geography (Dynamic Dashboard Snippet)
- Figure 25.1 Pulsed Field Ablation Market for Oncological Disorders: Distribution by Product Components
- Figure 25.2 Pulsed Field Ablation Market for Oncological Disorders using Catheters, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 25.3 Pulsed Field Ablation Market for Oncological Disorders using Generators, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 25.4 Pulsed Field Ablation Market for Oncological Disorders: Distribution by Product Components (Dynamic Dashboard Snippet)
- Figure 26.1 Pulsed Field Ablation Market for Oncological Disorders: Distribution by Type of Cancer
- Figure 26.2 Pulsed Field Ablation Market for Soft-tissue Ablative Cancers, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 26.3 Pulsed Field Ablation Market for Pancreatic Cancer, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 26.4 Pulsed Field Ablation Market for Prostate Cancer, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 26.5 Pulsed Field Ablation Market for Non-Small Cell Lung Cancer, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 26.6 Pulsed Field Ablation Market for Esophageal Cancer, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 26.7 Pulsed Field Ablation Market for Oncological Disorders: Distribution by Type of Cancer (Dynamic Dashboard Snippet)
- Figure 27.1 Pulsed Field Ablation Market for Respiratory Disorders: Distribution by Geography
- Figure 27.2 Pulsed Field Ablation Market for Respiratory Disorders in North America, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 27.3 Pulsed Field Ablation Market for Respiratory Disorders in Europe, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 27.4 Pulsed Field Ablation Market for Respiratory Disorders in Asia-Pacific, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 27.5 Pulsed Field Ablation Market for Respiratory Disorders: Distribution by Geography (Dynamic Dashboard Snippet)
- Figure 28.1 Pulsed Field Ablation Market for Respiratory Disorders: Distribution by Product Components
- Figure 28.2 Pulsed Field Ablation Market for Respiratory Disorders using Catheters, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 28.3 Pulsed Field Ablation Market for Respiratory Disorders using Generators, Historical Trends (Since 2018) and Forecasted Estimates (Till 2035) (USD Million)
- Figure 28.4 Pulsed Field Ablation Market for Respiratory Disorders: Distribution by Product Components (Dynamic Dashboard Snippet)
- Figure 29.1 Boston Scientific: Pulsed Field Ablation Sales Forecast (Till 2035) (USD Million)
- Figure 29.2 Medtronic: Pulsed Field Ablation Sales Forecast (Till 2035) (USD Million)
- Figure 29.3 Galvanize Therapeutics: Pulsed Field Ablation Sales Forecast (Till 2035) (USD Million)
- Figure 29.4 AngioDynamics: Pulsed Field Ablation Sales Forecast (Till 2035) (USD Million)
- Figure 30.1 Concluding Remarks: Overall Market Landscape
- Figure 30.2 Concluding Remarks: Recent Developments
- Figure 30.3 Concluding Remarks: Patent Analysis
- Figure 30.4 Concluding Remarks: Global Events Analysis
- Figure 30.5 Concluding Remarks: Market Forecast and Opportunity Analysis

