PUBLISHER: Roots Analysis | PRODUCT CODE: 2106270
PUBLISHER: Roots Analysis | PRODUCT CODE: 2106270
GLP-1 Receptor Agonist Market: by Type of Molecule, Active Compound Used, Type of GLP-1 Agonist Drugs, GLP-1 Agonist, Route of Administration, Target Indication, Sales Forecast and Leading Drug Developers - Trends and Forecast Till 2035
GLP-1 RECEPTOR AGONIST MARKET: OVERVIEW
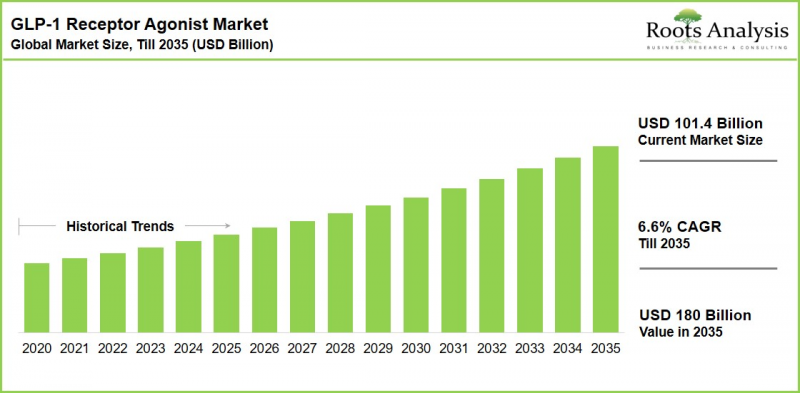
As per Roots Analysis, the global GLP-1 receptor agonist market is estimated to grow from USD 101.4 billion in the current year to USD 180 billion by 2035, at an impressive CAGR of 6.6%, during the forecast period, till 2035.
GLP-1 Receptor Agonist Market: Growth and Trends
GLP-1 receptor agonists are a class of incretin-based therapeutics originally developed to manage blood glucose levels in type 2 diabetes. Over the past decade, this drug class has moved well beyond glycemic control, with several molecules now demonstrating clinically meaningful weight loss and cardiovascular risk reduction. This expanded clinical footprint has repositioned GLP-1 therapies as one of the most commercially significant categories in pharmaceuticals today.
Nearly 42.4% of adults in the US are classified as obese. Therefore, the rising burden of obesity combined with rising social media visibility, celebrity endorsement, and direct-to-consumer advertising, has increased the demand for GLP-1 receptor agonists among patients for weight management and diabetes therapies. Pharmaceutical companies are responding with an expanding pipeline of next-generation molecules, including oral small-molecule GLP-1 agonists and multi-receptor agonists that combine GLP-1 activity with GIP or glucagon pathways for enhanced metabolic benefit.
Governments and regulatory authorities are refining approval frameworks for digital and connected healthcare solutions, improving market access while reinforcing compliance with quality and data protection standards. The FDA has approved oral semaglutide for cardiovascular risk reduction in type 2 diabetes, cleared the first generic version of liraglutide, and in 2026 approved Eli Lilly's oral orforglipron for weight management. Additional oral candidates, including AstraZeneca's elecoglipron and Structure Therapeutics' aleniglipron, are progressing through late-stage trials, signaling a structural shift toward oral administration that will reshape both prescribing patterns and distribution requirements over the coming decade.
The commercial ripple effects extend beyond pharmaceuticals. Government payers are also adapting: the US Medicare program launched an 18-month GLP-1 access pilot in 2026 offering obesity medications at a fraction of list price, a signal that reimbursement barriers are beginning to ease. Food and consumer goods companies, including Nestle, are developing companion products aimed at GLP-1 users, underscoring how deeply this drug class is influencing consumer behavior well outside clinical settings.
Growth Drivers: Factors Fueling Expansion of the Global GLP-1 Receptor Agonist Market
Market growth is being driven by the rising global burden of type 2 diabetes and obesity. Further, the expanding label indications for cardiovascular and hepatic conditions, and a deep late-stage pipeline of oral and multi-agonist candidates are driving its demand. regulatory decisions, growing payer willingness to cover metabolic therapies, and continued direct-to-consumer demand are reinforcing this trajectory. The anticipated shift toward oral formulations is expected to widen the addressable patient population by removing the administration barriers associated with injectable therapy.
Market Challenges: Critical Barriers Hindering Progress
Despite strong growth prospects, the market faces several challenges. Some of the notable challenges are patent expirations and the resulting entry of generics, beginning with liraglutide (Victoza) in 2024 and extending to semaglutide when its US exclusivity lapses in March 2026. Persistent supply shortages driven by off-label demand for weight management, high out-of-pocket costs in markets with limited reimbursement, and manufacturing capacity constraints continue to limit broader patient access.
Trends Reshaping the Competitive Landscape
The industry's focus is shifting from injectable biologics toward small-molecule and oral formats, as ease of administration, manufacturing efficiency, and broader patient accessibility becom key competitive differentiators. At the same time, the emergence of dual and tri-agonist mechanisms which are designed to engage more than one metabolic pathway at once is redefining what "best-in-class" efficacy looks like. This significant milestone is drawing a fresh cohort of specialty and platform biotech companies into a field that was, until recently, dominated by two originator companies.
A second notable trend is the crossover impact on adjacent industries. As GLP-1 adoption reshapes consumer eating patterns, food and consumer-packaged-goods companies are beginning to design "companion" product lines aimed at GLP-1 users, an early sign that this market's influence extends well past pharmaceutical channels and into broader consumer health strategy.
Deal and Funding Signals Worth Tracking
- Manufacturing Capital Deployment: Eli Lilly's disclosed USD 27 billion US manufacturing build-out (2025) is a direct proxy for originator confidence in sustained multi-year volume growth.
- Patent Cliff Timing: Semaglutide's core US exclusivity is set to expire in March 2026, with first-to-file generic rights already settled with Mylan and Natco Pharma a near-term catalyst for both risk and opportunity across the value chain.
- Policy Catalysts: The 2026 US Medicare "GLP-1 Bridge" pilot, offering select obesity therapies at roughly USD 50 per month for 18 months, is a live test case for how public payer participation could reshape addressable volume.
- Pipeline Milestones: Multiple oral and multi-agonist candidates advanced into or through Phase III during 2026 (including AstraZeneca's elecoglipron and Eli Lilly's orforglipron, approved as Foundayo), any of which could shift competitive share meaningfully before the end of the forecast period.
- Cross-Industry Spillover: Consumer packaged goods companies, including Nestle, are publicly new "companion product" strategies aimed at GLP-1 users which are an early indicator of investable second-order effects outside of pharma proper.
GLP-1 Receptor Agonist Market
The market sizing and opportunity analysis has been segmented across the following parameters:
By Type of Molecule
- Biologics
- Small Molecules
By Active Compound Used
- Dulaglutide
- Liraglutide
- Orforglipron
- Retatrutide
- Semaglutide
- Survodutide
- Tirzepatide
- Other Active Compounds
By Type of GLP-1 Agonist Drug
- Long-acting GLP-1 Agonist
- Short-acting GLP-1 Agonist
By GLP-1 Agonist
- Single-Agonist
- Dual-Agonist
- Tri-agonist
By Route of Administration
- Oral
- Parenteral
By Target Indication
- Alzheimer's Disease
- Non-alcoholic Steatohepatitis
- Obesity
- Sleep Apnea
- Type 2 Diabetes
By Geographical Regions
- North America
- US
- Canada
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- Australia
- Middle East and North Africa
- Saudi Arabia
- UAE
- Latin America
- Brazil
- Argentina
GLP-1 Receptor Agonist Market: Key Segment
Small Molecules Holds Highest Share
Based on our market assessment, small molecules currently occupy the highest share, accounting for nearly 55% of overall share. This leadership is driven by manufacturing economics, formulation flexibility, and compatibility with established pharmaceutical production infrastructure. These policies have encouraged sustained industry investment in small-molecule GLP-1 development.
Biologics, meanwhile, are expected to register meaningful growth over the forecast period. This is supported by strong clinical performance in glycemic control, weight management, and cardiovascular risk reduction. In addition, continued innovation in long-acting formulations and next-generation incretin platforms is likely to propel this segment growth in the future.
Semaglutide Leads the Market
Based on our market assessment, Semaglutide currently accounts for the largest share of the active-compound segment, a position built on its broad clinical footprint across type 2 diabetes and obesity and its availability in multiple formulations, including oral and injectable options. Retatrutide and survodutide are expected to be the fastest-growing active compounds through 2035. This highest CAGR is due to the rising industry interest in next-generation incretin therapies capable of delivering enhanced metabolic benefit beyond traditional glucose management.
Parenteral Administration Secures the Highest Share
Parenteral administration currently holds nearly 95% of overall market revenue share. This dominance is due to the long-established clinical use of injectable GLP-1 therapies and their ability to deliver peptide-based treatments directly into systemic circulation with consistent therapeutic activity.
The oral route is expected to register the highest growth rate over the forecast period. This lucrative growth is driven by patient preference for non-invasive treatment. In addition, advances in oral drug delivery technology, and a deepening late-stage pipeline of oral candidates from Eli Lilly, AstraZeneca, and Structure Therapeutics.
Type 2 Diabetes Dominates the Market
Based on our analysis, Type 2 diabetes remains the largest target indication, underpinned by extensive clinical evidence, physician familiarity, and the drug class's established role in glycemic control alongside weight and cardiovascular benefits.
Non-alcoholic steatohepatitis is expected to be the fastest-growing indication, anticipated to register a higher CAGR during the forecast period. This growth is due to the fact that GLP-1 receptor agonists demonstrate therapeutic potential in addressing both liver disease progression and the underlying metabolic dysfunction that drives this condition.
North America Holds the Highest Share and Asia-Pacific Grows at Higher CAGR
According to our projections, North America holds the highest share of the market and is likely to maintain its dominance during the forecast period. This dominance is due to the high disease prevalence, established reimbursement frameworks, and aggressive manufacturing investment from originator companies including multi-billion-dollar US capacity expansions announced in 2025.
Asia-Pacific, while starting from a smaller base, is expected to grow at the fastest CAGR during the forecast period. This unprecedented growth is due to the rising middle-class incomes, government-backed disease-management programs, and expanding telemedicine. Furthermore, the growing e-commerce access channels in China, India and South Korea combine to widen patient access to the GLP-1 receptor agonist.
Example Players in GLP-1 Receptor Agonist Market
- AstraZeneca
- Biolingus
- Boehringer Ingelheim
- D&D Pharmatech
- Eli Lilly
- Gmax Biopharm
- Hanmi Pharmaceutical
- Innogen
- Novo Nordisk
- PegBio
- Pfizer
- QL Biopharma
- Roche
- Sanofi
- Sciwind Biosciences
- Tonghua Dongbao Pharmaceutical
- Viking Therapeutics
- Vivani
- vTv Therapeutic
Expert Interview and Industry Insights
The opinions and insights presented in this study were influenced by discussions conducted with multiple stakeholders. The research report features detailed transcripts of interviews held with the following industry stakeholders:
- Chief Executive Officer, Large Organization, US
- Associate Professor, Large Organization, US
- Chief Scientific Officer, Large Organization, UK
- Chief Commercial Officer, Mid-Sized Organization, UK
- Senior Account Executive, Large Organization, US
- Chief Executive Officer, Large Organization, US
- Chief Executive Officer, Large Organization, Denmark
- Chief Scientific Adviser for Research, Large Organization, Denmark
- Chief Executive Officer, Mid-Sized Organization, India
- Chief Medical Officer, Mid-Sized Organization, US
GLP-1 RECEPTOR AGONIST MARKET: RESEARCH COVERAGE
- Market Sizing and Opportunity Analysis: An in-depth analysis of the GLP-1 receptor agonist market, focusing on key segments, including type of molecule, active compound used, type of GLP-1 agonist drug, GLP-1 agonist, route of administration, target indication, and geographical regions.
- Drug Developer Landscape: A detailed assessment of companies developing GLP-1 receptor agonists, based on parameters such as year of establishment, company size, location of headquarters, and stage of drug development.
- Company Profiles: In-depth profiles of prominent players engaged in the development and commercialization of GLP-1 receptor agonists, featuring information on year of establishment, headquarters, management team, product portfolio, and key initiatives.
- Partnerships and Collaborations Analysis: A comprehensive assessment of partnership activity among GLP-1 receptor agonist developers, evaluating collaborations by year, partnership type, focus area, and geography. The chapter also identifies the most active companies and analyzes regional deal patterns to highlight key collaboration strategies driving innovation and commercialization.
- Funding and Investment Analysis: A comprehensive assessment of funding and investment activity in the GLP-1 receptor agonist market, analyzing trends by year, funding type, investment value, purpose, and geography. The chapter also identifies the most active companies and leading investors based on funding activity and capital deployed, providing insights into investment trends and innovation priorities.
- Clinical Trial Analysis: An analysis of completed and ongoing clinical trials related to GLP-1 receptor agonists, based on several relevant parameters, including trial registration year, enrolled patient population, trial status, trial phase, type of sponsor/collaborator, study design, patient gender, leading industry and non-industry players (based on the number of registered trials), and geography.
- Patent Analysis: An in-depth analysis of patents related to GLP-1 receptor agonists, based on several relevant parameters, including patent publication year, application year, jurisdiction, CPC classification, and applicant type. The chapter also highlights leading industry and non-industry patent holders, along with patent benchmarking, valuation, and citation analyses to assess innovation trends and intellectual property strength.
- Demand Analysis: An assessment of the global annual demand for GLP-1 receptor agonists, based on key market assumptions and analytical methodology. The chapter analyzes demand across molecule type, active compound, drug class, GLP-1 agonist, route of administration, target indication, and geography to identify current and future demand trends.
- Market Impact Analysis: The report analyzes drivers, restraints, opportunities, and challenges affecting market growth, including the impact of upcoming patent expirations.
Key Questions Answered in this Report
- How large is the GLP-1 receptor agonist market today, and how large will it be by 2035?
- Which active compounds, delivery routes and agonist mechanisms are gaining or losing share?
- Which companies are best positioned across each segment, and what does their pipeline depth look like?
- What is the realistic impact of the semaglutide patent cliff on pricing and volume?
- Which indications beyond diabetes and obesity offer the strongest medium-term upside?
- Which geographies offer the best combination of near-term revenue and long-term growth rate?
Reasons to Buy this Report
Distributors evaluating the GLP-1 opportunity need more than headline market size figures. This report is built to support commercial decision-making, not just awareness, and differentiates itself on the following counts:
- Top-Down and Bottom-Up Triangulated Forecasting: revenue projections for each segment are cross-validated using both macro-level disease epidemiology and company-level sales data, reducing forecast risk for investors and channel partners.
- Primary Research with C-Suite and Scientific Leadership: insights are grounded in interviews with CEOs, chief scientific officers, and commercial leaders across large, mid-sized, and academic organizations, not desk research alone.
- Distribution and Channel-Specific Lens: unlike generic pharma market reports, this study maps how the shift from injectable to oral GLP-1 formulations will change cold-chain requirements, specialty pharmacy dependence, and retail pharmacy accessibility, insights directly relevant to distributors and 3PL providers.
- Patent-Cliff and Generics-Readiness Analysis: a dedicated view of upcoming exclusivity losses (liraglutide, semaglutide) helps distributors time inventory, contracting, and market-entry strategies around generic launch windows.
- Investor-Grade Financial Context: company profiles include revenue trends, recent capital deployment (such as Eli Lilly's USD 27 billion US manufacturing build-out), and funding activity, positioned for use in diligence and business case development.
Additional Benefits
- Complementary Excel Data Packs for all Analytical Modules in the Report
- 15% Free Content Customization
- Detailed Report Walkthrough Session with Research Team
- Free Updated report if the report is 6-12 months old or older
TABLE OF CONTENTS
1. PREFACE
- 1.1. Introduction
- 1.2. Market Share Insights
- 1.3. Key Market Insights
- 1.4. Report Coverage
- 1.5. Key Questions Answered
- 1.6. Chapter Outlines
2. RESEARCH METHODOLOGY
- 2.1. Chapter Overview
- 2.2. Research Assumptions
- 2.2.1. Market Landscape and Market Trends
- 2.2.2. Market Forecast and Opportunity Analysis
- 2.2.3. Comparative Analysis
- 2.3. Database Building
- 2.3.1. Data Collection
- 2.3.2. Data Validation
- 2.3.3. Data Analysis
- 2.4. Project Methodology
- 2.4.1. Secondary Research
- 2.4.1.1. Annual Reports
- 2.4.1.2. Academic Research Papers
- 2.4.1.3. Company Websites
- 2.4.1.4. Investor Presentations
- 2.4.1.5. Regulatory Filings
- 2.4.1.6. White Papers
- 2.4.1.7. Industry Publications
- 2.4.1.8. Conferences and Seminars
- 2.4.1.9. Government Portals
- 2.4.1.10. Media and Press Releases
- 2.4.1.11. Newsletters
- 2.4.1.12. Industry Databases
- 2.4.1.13. Roots Proprietary Databases
- 2.4.1.14. Paid Databases and Sources
- 2.4.1.15. Social Media Portals
- 2.4.1.16. Other Secondary Sources
- 2.4.2. Primary Research
- 2.4.2.1. Types of Primary Research
- 2.4.2.1.1. Qualitative Research
- 2.4.2.1.2. Quantitative Research
- 2.4.2.1.3. Hybrid Approach
- 2.4.2.2. Advantages of Primary Research
- 2.4.2.3. Techniques for Primary Research
- 2.4.2.3.1. Interviews
- 2.4.2.3.2. Surveys
- 2.4.2.3.3. Focus Groups
- 2.4.2.3.4. Observational Research
- 2.4.2.3.5. Social Media Interactions
- 2.4.2.4. Key Opinion Leaders Considered in Primary Research
- 2.4.2.4.1. Company Executives (CXOs)
- 2.4.2.4.2. Board of Directors
- 2.4.2.4.3. Company Presidents and Vice Presidents
- 2.4.2.4.4. Research and Development Heads
- 2.4.2.4.5. Technical Experts
- 2.4.2.4.6. Subject Matter Experts
- 2.4.2.4.7. Scientists
- 2.4.2.4.8. Doctors and Other Healthcare Providers
- 2.4.2.5. Ethics and Integrity
- 2.4.2.5.1. Research Ethics
- 2.4.2.5.2. Data Integrity
- 2.4.2.1. Types of Primary Research
- 2.4.3. Analytical Tools and Databases
- 2.4.1. Secondary Research
- 2.5. Robust Quality Control
3. MARKET DYNAMICS
- 3.1. Chapter Overview
- 3.2. Forecast Methodology
- 3.2.1. Top-down Approach
- 3.2.2. Bottom-up Approach
- 3.2.3. Hybrid Approach
- 3.3. Market Assessment Framework
- 3.3.1. Total Addressable Market (TAM)
- 3.3.2. Serviceable Addressable Market (SAM)
- 3.3.3. Serviceable Obtainable Market (SOM)
- 3.3.4. Currently Acquired Market (CAM)
- 3.4. Forecasting Tools and Techniques
- 3.4.1. Qualitative Forecasting
- 3.4.2. Correlation
- 3.4.3. Regression
- 3.4.4. Extrapolation
- 3.4.5. Convergence
- 3.4.6. Sensitivity Analysis
- 3.4.7. Scenario Planning
- 3.4.8. Data Visualization
- 3.4.9. Time Series Analysis
- 3.4.10. Forecast Error Analysis
- 3.5. Key Considerations
- 3.5.1. Demographics
- 3.5.2. Government Regulations
- 3.5.3. Reimbursement Scenarios
- 3.5.4. Market Access
- 3.5.5. Supply Chain
- 3.5.6. Industry Consolidation
- 3.5.7. Pandemic / Unforeseen Disruptions Impact
- 3.6. Limitations
4. MACRO-ECONOMIC INDICATORS
- 4.1. Chapter Overview
- 4.2. Market Dynamics
- 4.2.1. Time Period
- 4.2.1.1. Historical Trends
- 4.2.1.2. Current and Forecasted Estimates
- 4.2.2. Currency Coverage
- 4.2.2.1. Major Currencies Affecting the Market
- 4.2.2.2. Factors Affecting Currency Fluctuations
- 4.2.2.3. Impact of Currency Fluctuations on the Industry
- 4.2.3. Foreign Currency Exchange Rate
- 4.2.3.1. Impact of Foreign Exchange Rate Volatility on the Market
- 4.2.3.2. Strategies for Mitigating Foreign Exchange Risk
- 4.2.4. Recession
- 4.2.4.1. Assessment of Current Economic Conditions and Potential Impact on the Market
- 4.2.4.2. Historical Analysis of Past Recessions and Lessons Learnt
- 4.2.5. Inflation
- 4.2.5.1. Measurement and Analysis of Inflationary Pressures in the Economy
- 4.2.5.2. Potential Impact of Inflation on the Market Evolution
- 4.2.6. Interest Rates
- 4.2.6.1. Interest Rates and Their Impact on the Market
- 4.2.6.2. Strategies for Managing Interest Rate Risk
- 4.2.7. Commodity Flow Analysis
- 4.2.7.1. Type of Commodity
- 4.2.7.2. Origins and Destinations
- 4.2.7.3. Values and Weights
- 4.2.7.4. Modes of Transportation
- 4.2.8. Global Trade Dynamics
- 4.2.8.1. Import Scenario
- 4.2.8.2. Export Scenario
- 4.2.8.3. Trade Policies
- 4.2.8.4. Strategies for Mitigating the Risks Associated with Trade Barriers
- 4.2.8.5. Impact of Trade Barriers on the Market
- 4.2.9. War Impact Analysis
- 4.2.9.1. Russian-Ukraine War
- 4.2.9.2. Israel-Hamas War
- 4.2.10. COVID Impact / Related Factors
- 4.2.10.1. Global Economic Impact
- 4.2.10.2. Industry-specific Impact
- 4.2.10.3. Government Response and Stimulus Measures
- 4.2.10.4. Future Outlook and Adaptation Strategies
- 4.2.11. Other Indicators
- 4.2.11.1. Fiscal Policy
- 4.2.11.2. Consumer Spending
- 4.2.11.3. Gross Domestic Product
- 4.2.11.4. Employment
- 4.2.11.5. Taxes
- 4.2.11.6. Stock Market Performance
- 4.2.11.7. Cross Border Dynamics
- 4.2.1. Time Period
- 4.3. Conclusion
5. EXECUTIVE SUMMARY
- 5.1. Executive Summary: Market Landscape
- 5.2. Executive Summary: Market Trends
- 5.3. Executive Summary: Market Forecast and Opportunity Analysis
6. INTRODUCTION
- 6.1. Overview of the GLP-1 Receptor Agonist
- 6.2. Mechanism of Action of GLP-1 Receptor Agonist
- 6.3. Important Facts in GLP-1 Receptor Agonist Domain
- 6.4. Challenges Associated with GLP-1 Receptor Agonist
- 6.5. Future Perspectives
7. MARKET LANDSCAPE: GLP-1 RECEPTOR AGONIST
- 7.1. GLP-1 Receptor Agonist: Market Landscape
- 7.1.1. Analysis by Status of Development
- 7.1.2. Analysis by Type of Molecule
- 7.1.3. Analysis by Active Compound Used
- 7.1.4. Analysis by Type of Agonist
- 7.1.5. Analysis by Route of Administration
- 7.1.6. Analysis by Dosing Frequency
- 7.1.7. Analysis by Type of Therapy
- 7.1.8. Analysis by Target Indication
- 7.1.9. Analysis by Therapeutic Area
- 7.2. GLP-1 Receptor Agonist: Developer Landscape
- 7.2.1. Analysis by Year of Establishment
- 7.2.2. Analysis by Company Size
- 7.2.3. Analysis by Location of Headquarters
- 7.2.4. Analysis by Location of Headquarters (Country) and Status of Development
- 7.2.5. Most Active Developers: Analysis by Number of Therapies
8. COMPANY COMPETITIVENESS ANALYSIS
- 8.1. Chapter Overview
- 8.2. Methodology and Key Parameters
- 8.3. Scoring Criteria
- 8.4. Overview of Peer Groups
- 8.5. GLP-1 Receptor Agonist Developers: Company Competitiveness Analysis
- 8.5.1. GLP-1 Receptor Agonist Developers based in North America (Peer Group I)
- 8.5.2. GLP-1 Receptor Agonist Developers based in Europe (Peer Group II)
- 8.5.3. GLP-1 Receptor Agonist Developers in Asia-Pacific and Rest of the World (Peer Group III)
9. GLP-1 RECEPTOR AGONIST: DETAILED COMPANY PROFILES
- 9.1. Chapter Overview
- 9.1.1. AstraZeneca
- 9.1.1.1. Company Overview
- 9.1.1.2. Pipeline Portfolio
- 9.1.1.3. Financial Details
- 9.1.1.4. Recent Developments and Future Outlook
- 9.1.2. D&D Pharmatech
- 9.1.3. Eli Lilly
- 9.1.4. Novo Nordisk
- 9.1.5. Pfizer
- 9.1.6. Sanofi
- 9.1.7. Tonghua Dongbao Pharmaceutical
- 9.1.8. Vivani
- 9.1.1. AstraZeneca
10. GLP-1 RECEPTOR AGONIST: SHORT COMPANY PROFILES
- 10.1. Chapter Overview
- 10.1.1. Biolingus
- 10.1.1.1. Company Overview
- 10.1.1.2. Pipeline Portfolio
- 10.1.2. Boehringer Ingelheim
- 10.1.3. Gmax Biopharm
- 10.1.4. Hanmi Pharmaceutical
- 10.1.5. Innogen
- 10.1.6. PegBio
- 10.1.7. QL Biopharma
- 10.1.8. Roche
- 10.1.9. Sciwind Biosciences
- 10.1.10. Viking Therapeutics
- 10.1.11. vTv Therapeutics
- 10.1.1. Biolingus
11. PARTNERSHIPS AND COLLABORATIONS
- 11.1. Chapter Overview
- 11.2. Partnership Models
- 11.3. GLP-1 Receptor Agonist Developers: List of Partnerships and Collaborations
- 11.3.1. Analysis by Year of Partnership
- 11.3.2. Analysis by Type of Partnership
- 11.3.3. Analysis by Year and Type of Partnership
- 11.3.4. Analysis by Focus Area
- 11.3.5. Most Active Players: Analysis by Number of Partnerships
- 11.3.6. Analysis by Geography
- 11.3.6.1. Intercontinental and Intracontinental Deals
- 11.3.6.2. Local and International Deals
12. FUNDING AND INVESTMENTS
- 12.1. Chapter Overview
- 12.2. Funding Models
- 12.3. GLP-1 Receptor Agonist Developers: List of Funding and Investments
- 12.3.1. Analysis of Funding Instances by Year of Funding
- 12.3.2. Analysis of Amount Invested by Year of Funding
- 12.3.3. Analysis by Type of Funding
- 12.3.4. Analysis by Year and Type of Funding
- 12.3.5. Analysis by Amount Invested and Type of Funding
- 12.3.6. Analysis by Purpose of Funding
- 12.3.7. Analysis by Geography
- 12.3.8. Most Active Players: Analysis by Number of Instances
- 12.3.9. Most Active Players: Analysis by Amount Invested
- 12.3.10. Leading Investors: Analysis by Number of Instances
- 12.3.11. Funding and Investment Summary
13. CLINICAL TRIAL ANALYSIS
- 13.1. Chapter Overview
- 13.2. Scope and Methodology
- 13.3. GLP-1 Receptor Agonist: Clinical Trial Analysis
- 13.3.1. Analysis by Trial Registration Year
- 13.3.2. Analysis of Enrolled Patient Population by Trial Registration Year
- 13.3.3. Analysis by Trial Status
- 13.3.4. Analysis of Enrolled Patient Population by Trial Status
- 13.3.5. Analysis by Trial Registration Year and Trial Status
- 13.3.6. Analysis by Trial Phase
- 13.3.7. Analysis of Enrolled Patient Population by Trial Phase
- 13.3.8. Analysis by Type of Sponsor / Collaborator
- 13.3.9. Analysis by Study Design
- 13.3.10. Analysis by Gender
- 13.3.11. Leading Industry Players: Analysis by Number of Registered Trials
- 13.3.12. Leading Non-industry Players: Analysis by Number of Registered Trials
- 13.3.13. Analysis by Trial Status, Trial Phase and Geography
- 13.3.14. Analysis by Geography
- 13.3.15. Analysis by Trial Status and Geography
- 13.3.16. Analysis of Enrolled Patient Population by Trial Status and Geography
14. PATENT ANALYSIS
- 14.1. Chapter Overview
- 14.2. Scope and Methodology
- 14.3. GLP-1 Receptor Agonist: Patent Analysis
- 14.3.1. Analysis by Patent Publication Year
- 14.3.2. Analysis by Type of Patent and Publication Year
- 14.3.3. Analysis by Patent Application Year
- 14.3.4. Analysis by Patent Jurisdiction
- 14.3.5. Analysis by CPC Symbols
- 14.3.6. Analysis by Type of Applicant
- 14.3.7. Leading Industry Players: Analysis by Number of Patents
- 14.3.8. Leading Non-Industry Players: Analysis by Number of Patents
- 14.4. Patent Benchmarking Analysis
- 14.4.1. Analysis by Patent Characteristics
- 14.5. Patent Valuation
- 14.6. Leading Patents by Number of Citations
15. DEMAND ANALYSIS
- 15.1. Chapter Overview
- 15.2. Key Assumptions and Methodology
- 15.2.1. Global Annual Demand for GLP-1 Receptor Agonist
- 15.2.1.1. Analysis by Type of Molecule
- 15.2.1.2. Analysis by Type of Active Compound Used
- 15.2.1.3. Analysis by Type of GLP-1 Agonist Drugs
- 15.2.1.4. Analysis by GLP-1 Agonist
- 15.2.1.5. Analysis by Route of Administration
- 15.2.1.6. Analysis by Target Indication
- 15.2.1.7. Analysis by Geography
- 15.2.1. Global Annual Demand for GLP-1 Receptor Agonist
16. MARKET IMPACT ANALYSIS
- 16.1. Market Drivers
- 16.2. Market Restraints
- 16.3. Market Opportunities
- 16.4. Market Challenges
17. PRICING ANALYSIS
18. GLOBAL GLP-1 RECEPTOR AGONIST MARKET
- 18.1. Chapter Overview
- 18.2. Assumptions and Methodology
- 18.3. Global GLP-1 Receptor Agonist Market, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 18.3.1. Roots Analysis Perspective on Market Growth
- 18.3.2. Scenario Analysis
- 18.3.2.1. Conservative Scenario
- 18.3.2.2. Optimistic Scenario
- 18.4. Key Market Segmentations
19. GLP-1 RECEPTOR AGONIST MARKET, BY TYPE OF MOLECULE
- 19.1. Chapter Overview
- 19.2. Assumptions and Methodology
- 19.3. GLP-1 Receptor Agonist Market: Distribution by Type of Molecule
- 19.3.1. GLP-1 Receptor Agonist Market for Biologics, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.3.2. GLP-1 Receptor Agonist Market for Small Molecules, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.4. Data Triangulation and Validation
20. GLP-1 RECEPTOR AGONIST MARKET, BY ACTIVE COMPOUND USED
- 20.1. Chapter Overview
- 20.2. Assumptions and Methodology
- 20.3. GLP-1 Receptor Agonist Market: Distribution by Active Compound Used
- 20.3.1. GLP-1 Receptor Agonist Market for Dulaglutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.3.2. GLP-1 Receptor Agonist Market for Liraglutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.3.3. GLP-1 Receptor Agonist Market for Orforglipron, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.3.4. GLP-1 Receptor Agonist Market for Retatrutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.3.5. GLP-1 Receptor Agonist Market for Semaglutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.3.6. GLP-1 Receptor Agonist Market for Survodutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.3.7. GLP-1 Receptor Agonist Market for Tirzepatide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.3.8. GLP-1 Receptor Agonist Market for Other Active Compounds, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.4. Data Triangulation and Validation
21. GLP-1 RECEPTOR AGONIST MARKET, BY TYPE OF GLP-1 AGONIST DRUGS
- 21.1. Chapter Overview
- 21.2. Assumptions and Methodology
- 21.3. GLP-1 Receptor Agonist Market: Distribution by Type of GLP-1 Agonist Drugs
- 21.3.1. GLP-1 Receptor Agonist Market for Long-acting GLP-1 Agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 21.3.2. GLP-1 Receptor Agonist Market for Short-acting GLP-1 Agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 21.4. Data Triangulation and Validation
22. GLP-1 RECEPTOR AGONIST MARKET, BY GLP-1 AGONIST
- 22.1. Chapter Overview
- 22.2. Assumptions and Methodology
- 22.3. GLP-1 Receptor Agonist Market: Distribution by GLP-1 Agonist
- 22.3.1. GLP-1 Receptor Agonist Market for Single-agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.3.2. GLP-1 Receptor Agonist Market for Dual-agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.3.3. GLP-1 Receptor Agonist Market for Tri-agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.4. Data Triangulation and Validation
23. GLP-1 RECEPTOR AGONIST MARKET, BY ROUTE OF ADMINISTRATION
- 23.1. Chapter Overview
- 23.2. Assumptions and Methodology
- 23.3. GLP-1 Receptor Agonist Market: Distribution by Route of Administration
- 23.3.1. GLP-1 Receptor Agonist Market for Oral route, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 23.3.2. GLP-1 Receptor Agonist Market for Parental Route, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 23.4. Data Triangulation and Validation
24. GLP-1 RECEPTOR AGONIST MARKET, BY TARGET INDICATION
- 24.1. Chapter Overview
- 24.2. Assumptions and Methodology
- 24.3. GLP-1 Receptor Agonist Market: Distribution by Target Indication
- 24.3.1. GLP-1 Receptor Agonist Market for Alzheimer's Disease, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.3.2. GLP-1 Receptor Agonist Market for Non-Alcoholic Steatohepatitis, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.3.3. GLP-1 Receptor Agonist Market for Obesity, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.3.4. GLP-1 Receptor Agonist Market for Sleep Apnea, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.3.5. GLP-1 Receptor Agonist Market for Type 2 Diabetes, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.4. Data Triangulation and Validation
25. GLP-1 RECEPTOR AGONIST MARKET, BY GEOGRAPHICAL REGIONS
- 25.1. Chapter Overview
- 25.2. Assumptions and Methodology
- 25.3. GLP-1 Receptor Agonist Market: Distribution by Geographical Regions
- 25.3.1. GLP-1 Receptor Agonist Market in North America: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.1.1. GLP-1 Receptor Agonist Market in the US: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.1.2. GLP-1 Receptor Agonist Market in Canada: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.2. GLP-1 Receptor Agonist Market in Europe: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.2.1. GLP-1 Receptor Agonist Market in Germany: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.2.2. GLP-1 Receptor Agonist Market in France: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.2.3. GLP-1 Receptor Agonist Market in the UK: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.2.4. GLP-1 Receptor Agonist Market in Italy: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.2.5. GLP-1 Receptor Agonist Market in Spain: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.2.6. GLP-1 Receptor Agonist Market in Rest of Europe: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.3. GLP-1 Receptor Agonist Market in Asia-Pacific: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.3.1. GLP-1 Receptor Agonist Market in China: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.3.2. GLP-1 Receptor Agonist Market in Japan: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.3.3. GLP-1 Receptor Agonist Market in South Korea: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.3.4. GLP-1 Receptor Agonist Market in Australia: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.3.5. GLP-1 Receptor Agonist Market in Rest of Asia-Pacific: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.4. GLP-1 Receptor Agonist Market in Latin America: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.4.1. GLP-1 Receptor Agonist Market in Brazil: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.4.2. GLP-1 Receptor Agonist Market in Argentina: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.4.3. GLP-1 Receptor Agonist Market in Rest of Latin America: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.3.1. GLP-1 Receptor Agonist Market in North America: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 25.4. Data Triangulation and Validation
26. GLP-1 RECEPTOR AGONIST MARKET, SALES FORECAST OF GLP-1 DRUGS
- 26.1. Chapter Overview
- 26.1.1. Assumptions and Methodology
- 26.2. Approved GLP-1 Drugs: Sales Forecast
- 26.2.1. Feisumei (Benaglutide) Sales Forecast
- 26.2.2. Fu Laimei (Polyethylene Glycol Loxenatide) Sales Forecast
- 26.2.3. Mounjaro (Tirzepatide) Sales Forecast
- 26.2.4. Ozempic (Semaglutide Subcutaneous) Sales Forecast
- 26.2.5. Rybelsus (Semaglutide Oral) Sales Forecast
- 26.2.6. Saxenda (Liraglutide) Sales Forecast
- 26.2.7. Trulicity (Dulaglutide) Sales Forecast
- 26.2.8. Victoza (Liraglutide) Sales Forecast
- 26.2.9. Wegovy (Semaglutide Subcutaneous) Sales Forecast
- 26.2.10. XULTOPHY (Insulin Degludec / Liraglutide ) Sales Forecast
- 26.2.11. Zepbound (Tirzepatide) Sales Forecast
- 26.3. Phase III GLP-1 Drugs: Sales Forecast
- 26.3.1. GMA102 / Glutazumab Sales Forecast
- 26.3.2. JY09 Sales Forecast
- 26.3.3. LY3298176 / Tirzepatide Sales Forecast
- 26.3.4. Mazdutide / LY3305677/ IBI-362 Sales Forecast
- 26.3.5. Orforglipron / LY3502970 Sales Forecast
- 26.3.6. PB-119 / PEG-exenatide / Polyethylene glycol exenatide Sales Forecast
- 26.3.7. Retatrutide / LY3437943 Sales Forecast
- 26.3.8. Semaglutide Oral Sales Forecast
- 26.3.9. Semaglutide Subcutaneous Sales Forecast
- 26.3.10. Survodutide / BI 456906 Sales Forecast
- 26.3.11. XW003 / Ecnoglutide Sales Forecast
- 26.3.12. YN011-isupaglutide Sales Forecast
27. GLP-1 RECEPTOR AGONIST MARKET, BY LEADING DRUG DEVELOPERS
- 27.1. Chapter Overview
- 27.2. Assumptions and Methodology
- 27.3. GLP-1 Receptor Agonist Market: Distribution by Leading Drug Developers, 2020 (USD Billion)
- 27.4. GLP-1 Receptor Agonist Market: Distribution by Leading Drug Developers, Current Year (USD Billion)
- 27.5. GLP-1 Receptor Agonist Market: Distribution by Leading Drug Developers, 2035 (USD Billion)
28. GLP-1 RECEPTOR AGONIST MARKET OPPORTUNITY ANALYSIS: NORTH AMERICA
- 28.1. GLP-1 Receptor Agonist Market in North America: Distribution by Type of Molecule
- 28.1.1. GLP-1 Receptor Agonist Market in North America for Biologics, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.1.2. GLP-1 Receptor Agonist Market in North America for Small Molecules, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.2. GLP-1 Receptor Agonist Market in North America: Distribution by Active Compound Used
- 28.2.1. GLP-1 Receptor Agonist Market in North America for Dulaglutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.2.2. GLP-1 Receptor Agonist Market in North America for Liraglutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.2.3. GLP-1 Receptor Agonist Market in North America for Orforglipron, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.2.4. GLP-1 Receptor Agonist Market in North America for Retatrutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.2.5. GLP-1 Receptor Agonist Market in North America for Semaglutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.2.6. GLP-1 Receptor Agonist Market in North America for Survodutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.2.7. GLP-1 Receptor Agonist Market in North America for Tirzepatide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.2.8. GLP-1 Receptor Agonist Market in North America for Other Active Compounds, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.3. GLP-1 Receptor Agonist Market: Distribution by Type of GLP-1 Agonist Drugs
- 28.3.1. GLP-1 Receptor Agonist Market in North America for Long-acting GLP-1 Agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.3.2. GLP-1 Receptor Agonist Market in North America for Short-acting GLP-1 Agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.4. GLP-1 Receptor Agonist Market in North America: Distribution by GLP-1 Agonist
- 28.4.1. GLP-1 Receptor Agonist Market in North America for Single-agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.4.2. GLP-1 Receptor Agonist Market in North America for Dual-agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.4.3. GLP-1 Receptor Agonist Market in North America for Tri-agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.5. GLP-1 Receptor Agonist Market in North America: Distribution by Route of Administration
- 28.5.1. GLP-1 Receptor Agonist Market in North America for Oral route, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.5.2. GLP-1 Receptor Agonist Market in North America for Parental Route, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.6. GLP-1 Receptor Agonist Market in North America: Distribution by Target Indication
- 28.6.1. GLP-1 Receptor Agonist Market in North America for Alzheimer's Disease, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.6.2. GLP-1 Receptor Agonist Market in North America for Non-Alcoholic Steatohepatitis, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.6.3. GLP-1 Receptor Agonist Market in North America for Obesity, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.6.4. GLP-1 Receptor Agonist Market in North America for Sleep Apnea, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 28.6.5. GLP-1 Receptor Agonist Market in North America for Type 2 Diabetes, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
29. GLP-1 RECEPTOR AGONIST MARKET OPPORTUNITY ANALYSIS: EUROPE
- 29.1. GLP-1 Receptor Agonist Market in Europe: Distribution by Type of Molecule
- 29.1.1. GLP-1 Receptor Agonist Market in Europe for Biologics, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.1.2. GLP-1 Receptor Agonist Market in Europe for Small Molecules, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.2. GLP-1 Receptor Agonist Market in Europe: Distribution by Active Compound Used
- 29.2.1. GLP-1 Receptor Agonist Market in Europe for Dulaglutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.2.2. GLP-1 Receptor Agonist Market in Europe for Liraglutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.2.3. GLP-1 Receptor Agonist Market in Europe for Orforglipron, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.2.4. GLP-1 Receptor Agonist Market in Europe for Retatrutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.2.5. GLP-1 Receptor Agonist Market in Europe for Semaglutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.2.6. GLP-1 Receptor Agonist Market in Europe for Survodutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.2.7. GLP-1 Receptor Agonist Market in Europe for Tirzepatide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.2.8. GLP-1 Receptor Agonist Market in Europe for Other Active Compounds, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.3. GLP-1 Receptor Agonist Market: Distribution by Type of GLP-1 Agonist Drugs
- 29.3.1. GLP-1 Receptor Agonist Market in Europe for Long-acting GLP-1 Agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.3.2. GLP-1 Receptor Agonist Market in Europe for Short-acting GLP-1 Agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.4. GLP-1 Receptor Agonist Market in Europe: Distribution by GLP-1 Agonist
- 29.4.1. GLP-1 Receptor Agonist Market in Europe for Single-agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.4.2. GLP-1 Receptor Agonist Market in Europe for Dual-agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.4.3. GLP-1 Receptor Agonist Market in Europe for Tri-agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.5. GLP-1 Receptor Agonist Market in Europe: Distribution by Route of Administration
- 29.5.1. GLP-1 Receptor Agonist Market in Europe for Oral route, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.5.2. GLP-1 Receptor Agonist Market in Europe for Parental Route, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.6. GLP-1 Receptor Agonist Market in Europe: Distribution by Target Indication
- 29.6.1. GLP-1 Receptor Agonist Market in Europe for Alzheimer's Disease, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.6.2. GLP-1 Receptor Agonist Market in Europe for Non-Alcoholic Steatohepatitis, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.6.3. GLP-1 Receptor Agonist Market in Europe for Obesity, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.6.4. GLP-1 Receptor Agonist Market in Europe for Sleep Apnea, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 29.6.5. GLP-1 Receptor Agonist Market in Europe for Type 2 Diabetes, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
30. GLP-1 RECEPTOR AGONIST MARKET OPPORTUNITY ANALYSIS: ASIA-PACIFIC
- 30.1. GLP-1 Receptor Agonist Market in Asia-Pacific: Distribution by Type of Molecule
- 30.1.1. GLP-1 Receptor Agonist Market in Asia-Pacific for Biologics, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.1.2. GLP-1 Receptor Agonist Market in Asia-Pacific for Small Molecules, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.2. GLP-1 Receptor Agonist Market in Asia-Pacific: Distribution by Active Compound Used
- 30.2.1. GLP-1 Receptor Agonist Market in Asia-Pacific for Dulaglutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.2.2. GLP-1 Receptor Agonist Market in Asia-Pacific for Liraglutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.2.3. GLP-1 Receptor Agonist Market in Asia-Pacific for Orforglipron, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.2.4. GLP-1 Receptor Agonist Market in Asia-Pacific for Retatrutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.2.5. GLP-1 Receptor Agonist Market in Asia-Pacific for Semaglutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.2.6. GLP-1 Receptor Agonist Market in Asia-Pacific for Survodutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.2.7. GLP-1 Receptor Agonist Market in Asia-Pacific for Tirzepatide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.2.8. GLP-1 Receptor Agonist Market in Asia-Pacific for Other Active Compounds, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.3. GLP-1 Receptor Agonist Market: Distribution by Type of GLP-1 Agonist Drugs
- 30.3.1. GLP-1 Receptor Agonist Market in Asia-Pacific for Long-acting GLP-1 Agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.3.2. GLP-1 Receptor Agonist Market in Asia-Pacific for Short-acting GLP-1 Agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.4. GLP-1 Receptor Agonist Market in Asia-Pacific: Distribution by GLP-1 Agonist
- 30.4.1. GLP-1 Receptor Agonist Market in Asia-Pacific for Single-agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.4.2. GLP-1 Receptor Agonist Market in Asia-Pacific for Dual-agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.4.3. GLP-1 Receptor Agonist Market in Asia-Pacific for Tri-agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.5. GLP-1 Receptor Agonist Market in Asia-Pacific: Distribution by Route of Administration
- 30.5.1. GLP-1 Receptor Agonist Market in Asia-Pacific for Oral route, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.5.2. GLP-1 Receptor Agonist Market in Asia-Pacific for Parental Route, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.6. GLP-1 Receptor Agonist Market in Asia-Pacific: Distribution by Target Indication
- 30.6.1. GLP-1 Receptor Agonist Market in Asia-Pacific for Alzheimer's Disease, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.6.2. GLP-1 Receptor Agonist Market in Asia-Pacific for Non-Alcoholic Steatohepatitis, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.6.3. GLP-1 Receptor Agonist Market in Asia-Pacific for Obesity, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.6.4. GLP-1 Receptor Agonist Market in Asia-Pacific for Sleep Apnea, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 30.6.5. GLP-1 Receptor Agonist Market in Asia-Pacific for Type 2 Diabetes, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
31. GLP-1 RECEPTOR AGONIST MARKET OPPORTUNITY ANALYSIS: LATIN AMERICA
- 31.1. GLP-1 Receptor Agonist Market in Latin America: Distribution by Type of Molecule
- 31.1.1. GLP-1 Receptor Agonist Market in Latin America for Biologics, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.1.2. GLP-1 Receptor Agonist Market in Latin America for Small Molecules, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.2. GLP-1 Receptor Agonist Market in Latin America: Distribution by Active Compound Used
- 31.2.1. GLP-1 Receptor Agonist Market in Latin America for Dulaglutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.2.2. GLP-1 Receptor Agonist Market in Latin America for Liraglutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.2.3. GLP-1 Receptor Agonist Market in Latin America for Orforglipron, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.2.4. GLP-1 Receptor Agonist Market in Latin America for Retatrutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.2.5. GLP-1 Receptor Agonist Market in Latin America for Semaglutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.2.6. GLP-1 Receptor Agonist Market in Latin America for Survodutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.2.7. GLP-1 Receptor Agonist Market in Latin America for Tirzepatide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.2.8. GLP-1 Receptor Agonist Market in Latin America for Other Active Compounds, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.3. GLP-1 Receptor Agonist Market: Distribution by Type of GLP-1 Agonist Drugs
- 31.3.1. GLP-1 Receptor Agonist Market in Latin America for Long-acting GLP-1 Agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.3.2. GLP-1 Receptor Agonist Market in Latin America for Short-acting GLP-1 Agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.4. GLP-1 Receptor Agonist Market in Latin America: Distribution by GLP-1 Agonist
- 31.4.1. GLP-1 Receptor Agonist Market in Latin America for Single-agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.4.2. GLP-1 Receptor Agonist Market in Latin America for Dual-agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.4.3. GLP-1 Receptor Agonist Market in Latin America for Tri-agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.5. GLP-1 Receptor Agonist Market in Latin America: Distribution by Route of Administration
- 31.5.1. GLP-1 Receptor Agonist Market in Latin America for Oral route, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.5.2. GLP-1 Receptor Agonist Market in Latin America for Parental Route, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.6. GLP-1 Receptor Agonist Market in Latin America: Distribution by Target Indication
- 31.6.1. GLP-1 Receptor Agonist Market in Latin America for Alzheimer's Disease, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.6.2. GLP-1 Receptor Agonist Market in Latin America for Non-Alcoholic Steatohepatitis, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.6.3. GLP-1 Receptor Agonist Market in Latin America for Obesity, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.6.4. GLP-1 Receptor Agonist Market in Latin America for Sleep Apnea, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 31.6.5. GLP-1 Receptor Agonist Market in Latin America for Type 2 Diabetes, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
32. CONCLUDING REMARKS
33. EXECUTIVE INSIGHTS
34. APPENDIX I: TABULATED DATA
35. APPENDIX II: LIST OF COMPANIES AND ORGANIZATIONS
List of Tables
- Table 7.1 List of GLP-1 Receptor Agonists
- Table 7.2 List of GLP-1 Receptor Agonist Developers
- Table 9.1 AstraZeneca: Pipeline Portfolio
- Table 9.2 AstraZeneca: Recent Developments and Future Outlook
- Table 9.3 D&D Pharmatech: Pipeline Portfolio
- Table 9.4 D&D Pharmatech: Recent Developments and Future Outlook
- Table 9.5 Eli Lilly: Pipeline Portfolio
- Table 9.6 Eli Lilly: Recent Developments and Future Outlook
- Table 9.7 Novo Nordisk: Pipeline Portfolio
- Table 9.8 Novo Nordisk: Recent Developments and Future Outlook
- Table 9.9 Pfizer: Pipeline Portfolio
- Table 9.10 Pfizer: Recent Developments and Future Outlook
- Table 9.11 Sanofi: Pipeline Portfolio
- Table 9.12 Sanofi: Recent Developments and Future Outlook
- Table 9.13 Tonghua Dongbao Pharmaceutical: Pipeline Portfolio
- Table 9.14 Tonghua Dongbao Pharmaceutical: Recent Developments and Future Outlook
- Table 9.15 Vivani: Pipeline Portfolio
- Table 9.16 Vivani: Recent Developments and Future Outlook
- Table 10.1 Biolingus: Pipeline Portfolio
- Table 10.2 Boehringer Ingelheim: Pipeline Portfolio
- Table 10.3 Gmax Biopharm: Pipeline Portfolio
- Table 10.4 Hanmi Pharmaceutical: Pipeline Portfolio
- Table 10.5 PegBio: Pipeline Portfolio
- Table 10.6 QL Biopharma: Pipeline Portfolio
- Table 10.7 Roche: Pipeline Portfolio
- Table 10.8 Sciwind Biosciences: Pipeline Portfolio
- Table 10.9 Viking Therapeutics: Pipeline Portfolio
- Table 10.10 vTv Therapeutics: Pipeline Portfolio
- Table 11.1 GLP-1 Receptor Agonist Market: List of Partnerships and Collaborations, Since 2021
- Table 12.1 GLP-1 Receptor Agonist Market: List of Funding and Investments, Since 2021
- Table 14.1 Patent Analysis: Top CPC Sections
- Table 14.2 Patent Analysis: Top CPC Symbols
- Table 14.3 Patent Analysis: Top CPC Codes
- Table 14.4 Patent Analysis: Summary of Benchmarking Analysis
- Table 14.5 Patent Analysis: Categorization based on Weighted Valuation Scores
- Table 14.6 Patent Portfolio: List of Leading Patents (by Highest Relative Valuation)
- Table 14.7 Patent Portfolio: List of Leading Patents (by Number of Citations)
- Table 18.1 List of GLP-1 Receptor Agonist Drugs Forecasted
- Table 34.1 GLP-1 Receptor Agonist Drug: Distribution by Status of Development
- Table 34.2 GLP-1 Receptor Agonist Drug: Distribution by Type of Molecule
- Table 34.3 GLP-1 Receptor Agonist Drug: Distribution by Active Compound Used
- Table 34.4 GLP-1 Receptor Agonist Drug: Distribution by Type of Agonist
- Table 34.5 GLP-1 Receptor Agonist Drug: Distribution by Route of Administration
- Table 34.6 GLP-1 Receptor Agonist Drug: Distribution by Dosing Frequency
- Table 34.7 GLP-1 Receptor Agonist Drug: Distribution by Type of Therapy
- Table 34.8 GLP-1 Receptor Agonist Drug: Distribution by Target Indication
- Table 34.9 GLP-1 Receptor Agonist Drug: Distribution by Therapeutic Area
- Table 34.10 GLP-1 Receptor Agonist Developer: Distribution by Year of Establishment
- Table 34.11 GLP-1 Receptor Agonist Developer: Distribution by Company Size
- Table 34.12 GLP-1 Receptor Agonist Developer: Distribution by Location of Headquarters
- Table 34.13 GLP-1 Drugs Developer: Distribution by Location of Headquarters (Country) and Status of Development
- Table 34.14 Most Active Developers: Distribution by Number of GLP-1 Receptor Agonist Drugs
- Table 34.15 AstraZeneca: Annual Revenues, Since FY 2021 (USD Billion)
- Table 34.16 D&D Pharmatech: Annual Revenues, Since FY 2021 (Korean Won Billion)
- Table 34.17 Eli Lilly: Annual Revenues, Since FY 2021 (USD Billion)
- Table 34.18 Novo Nordisk: Annual Revenues, Since FY 2021 (DKK Billion)
- Table 34.19 Pfizer: Annual Revenues, Since FY 2021 (USD Billion)
- Table 34.20 Sanofi: Annual Revenues, Since FY 2021 (EUR Billion)
- Table 34.21 Tonghua Dongbao Pharmaceutical: Annual Revenues, Since FY 2021 (RMB Billion)
- Table 34.22 Vivani: Annual Revenues, Since FY 2021 (RMB Billion)
- Table 34.23 Partnerships and Collaborations: Distribution by Year of Partnership, Since 2022
- Table 34.24 Partnerships and Collaborations: Distribution by Type of Partnership
- Table 34.25 Partnerships and Collaborations: Distribution by Year of Partnership and Type of Partnership
- Table 34.26 Partnerships and Collaborations: Distribution by Focus Area
- Table 34.27 Most Active Players: Distribution by Number of Partnerships
- Table 34.28 Partnerships and Collaborations: Distribution by Intracontinental and Intercontinental Deals
- Table 34.29 Partnerships and Collaborations: Distribution by Local and International Deals
- Table 34.30 Funding and Investments: Cumulative Year-wise Distribution of Funding Instances, Since 2021
- Table 34.31 Funding and Investments: Cumulative Year-wise Distribution of Amount Invested (USD Million), Since 2021
- Table 34.32 Funding and Investments: Distribution by Year of Funding and Amount Invested (USD Million), Since 2021
- Table 34.33 Funding and Investments: Distribution by Type of Funding
- Table 34.34 Funding and Investments: Distribution by Year and Type of Funding, Since 2021
- Table 34.35 Funding and Investments: Distribution by Amount Invested and Type of Funding
- Table 34.36 Funding and Investments: Distribution by Purpose of Funding
- Table 34.37 Funding and Investments: Distribution by Geography
- Table 34.38 Most Active Players: Distribution by Number of Instances
- Table 34.39 Most Active Players: Distribution by Amount Invested (USD Million)
- Table 34.40 Leading Investors: Distribution by Number of Funding Instances
- Table 34.41 Funding and Investment Summary, Since 2021
- Table 34.42 Distribution by Trial Registration Year, Since 2021
- Table 34.43 Distribution of Enrolled Patient Population by Trial Registration Year
- Table 34.44 Distribution by Trial Status
- Table 34.45 Distribution of Enrolled Patient Population by Trial Status
- Table 34.46 Distribution by Trial Registration Year and Trial Status
- Table 34.47 Distribution by Trial Phase
- Table 34.48 Distribution of Enrolled Patient Population by Trial Phase
- Table 34.49 Distribution by Type of Sponsor / Collaborator
- Table 34.50 Distribution by Study Design
- Table 34.51 Distribution by Gender
- Table 34.52 Leading Industry Players: Distribution by Number of Registered Trials
- Table 34.53 Leading Non-industry Players: Distribution by Number of Registered Trials
- Table 34.54 Distribution of by Trial Status, Trial Phase and Geography
- Table 34.55 Distribution by Geography
- Table 34.56 Distribution by Trial Status and Geography
- Table 34.57 Distribution of Enrolled Patient Population by Trial Status and Geography
- Table 34.58 Patent Analysis: Distribution by Type of Patent
- Table 34.59 Patent Analysis: Cumulative Distribution by Patent Publication Year, Since 2021
- Table 34.60 Patent Analysis: Distribution by Type of Patent and Publication Year, Since 2021
- Table 34.61 Patent Analysis: Distribution by Patent Application Year, Since Pre-2019
- Table 34.62 Patent Analysis: Patent Jurisdiction
- Table 34.63 Leading Industry Players: Distribution by Number of Patents
- Table 34.64 Leading Non-Industry Players: Distribution by Number of Patents
- Table 34.65 Patent Analysis: Distribution by Patent Age
- Table 34.66 GLP-1: Patent Valuation
- Table 34.67 Global Annual Demand for GLP-1 Drugs, Since 2020 (in units)
- Table 34.68 Global Demand for GLP-1 Receptor Agonist: Distribution by Type of Molecule (in units)
- Table 34.69 Global Demand for GLP-1 Receptor Agonist: Distribution by Type of Active Compound Used (in units)
- Table 34.70 Global Demand for GLP-1 Receptor Agonist: Distribution by Type of GLP-1 Agonist Drugs (in units)
- Table 34.71 Global Demand for GLP-1 Receptor Agonist: Distribution by GLP-1 Agonist (in units)
- Table 34.72 Global Demand for GLP-1 Receptor Agonist: Distribution by Route of Administration (in units)
- Table 34.73 Global Demand for GLP-1 Receptor Agonist: Distribution by Target Indication (in units)
- Table 34.74 Global Demand for GLP-1 Receptor Agonist: Distribution by Geography (in units)
- Table 34.75 Global GLP-1 Receptor Agonist Market, Historical Trends (since 2020) and Forecasted Estimates (Till 2035)
- Table 34.76 Global GLP-1 Receptor Agonist Market, Forecasted Estimates (Till 2035): Conservative Scenario
- Table 34.77 Global GLP-1 Receptor Agonist Market, Forecasted Estimates (Till 2035): Optimistic Scenario
- Table 34.78 GLP-1 Receptor Agonist Market: Distribution by Type of Molecule, 2020, Current Year and 2035
- Table 34.79 GLP-1 Receptor Agonist Market for Biologics, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.80 GLP-1 Receptor Agonist Market for Small Molecules, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.81 GLP-1 Receptor Agonist Market: Distribution by Type of Active Compound Used, 2020, Current Year and 2035
- Table 34.82 GLP-1 Receptor Agonist Market for Dulaglutide, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.83 GLP-1 Receptor Agonist Market for Liraglutide, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.84 GLP-1 Receptor Agonist Market for Orforglipron, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.85 GLP-1 Receptor Agonist Market for Retatrutide, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.86 GLP-1 Receptor Agonist Market for Semaglutide, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.87 GLP-1 Receptor Agonist Market for Survodutide, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.88 GLP-1 Receptor Agonist Market for Tirzepatide, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.89 GLP-1 Receptor Agonist Market for Other Active Compounds, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.90 GLP-1 Receptor Agonist Market: Distribution by Type of GLP-1 Agonist Drugs, 2020, Current Year and 2035
- Table 34.91 GLP-1 Receptor Agonist Market for Long-acting GLP-1 Agonist, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.92 GLP-1 Receptor Agonist Market for Short-acting GLP-1 Agonist, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.93 GLP-1 Receptor Agonist Market: Distribution by GLP-1 Agonist, 2020, Current Year and 2035
- Table 34.94 GLP-1 Receptor Agonist Market for Single-agonist, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.95 GLP-1 Receptor Agonist Market for Dual-agonist, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.96 GLP-1 Receptor Agonist Market for Tri-agonist, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.97 GLP-1 Receptor Agonist Market: Distribution by Route of Administration, 2020, Current Year and 2035
- Table 34.98 GLP-1 Receptor Agonist Market for Oral Route, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.99 GLP-1 Receptor Agonist Market for Parental Route, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.100 GLP-1 Receptor Agonist Market: Distribution by Target Indication, 2020, Current Year and 2035
- Table 34.101 GLP-1 Receptor Agonist Market for Alzheimer's Disease, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.102 GLP-1 Receptor Agonist Market for Non-Alcoholic Steatohepatitis, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.103 GLP-1 Receptor Agonist Market for Obesity, Historical Trends Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.104 GLP-1 Receptor Agonist Market for Sleep Apnea, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.105 GLP-1 Receptor Agonist Market for Type 2 Diabetes, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.106 GLP-1 Receptor Agonist Market: Distribution by Geographical Regions, 2020, Current Year and 2035
- Table 34.107 GLP-1 Receptor Agonist Market in North America, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.108 GLP-1 Receptor Agonist Market in the US, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.109 GLP-1 Receptor Agonist Market in Canada, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.110 GLP-1 Receptor Agonist Market in Europe, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.111 GLP-1 Receptor Agonist Market in Germany, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.112 GLP-1 Receptor Agonist Market in France, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.113 GLP-1 Receptor Agonist Market in the UK, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.114 GLP-1 Receptor Agonist Market in Italy, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.115 GLP-1 Receptor Agonist Market in Spain, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.116 GLP-1 Receptor Agonist Market in Rest of Europe, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.117 GLP-1 Receptor Agonist Market in Asia-Pacific, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.118 GLP-1 Receptor Agonist Market in China, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.119 GLP-1 Receptor Agonist Market in Japan, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.120 GLP-1 Receptor Agonist Market in South Korea, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.121 GLP-1 Receptor Agonist Market in Australia, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.122 GLP-1 Receptor Agonist Market in Rest of Asia-Pacific, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.123 GLP-1 Receptor Agonist Market in Latin America, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.124 GLP-1 Receptor Agonist Market in Brazil, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.125 GLP-1 Receptor Agonist Market in Argentina, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.126 GLP-1 Receptor Agonist Market in Rest of Latin America, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.127 Approved GLP-1 Drug, Feisumei (Benaglutide) Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.128 Approved GLP-1 Receptor Agonist Drug, Fu Laimei (Polyethylene Glycol Loxenatide) Sales Forecast, Till 2035, Conservative, Base and Optimistic Scena
- Table 34.129 Approved GLP-1 Receptor Agonist Drug, Mounjaro (Tirzepatide) Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.130 Approved GLP-1 Receptor Agonist Drug, Ozempic (Semaglutide Subcutaneous) Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD
- Table 34.131 Approved GLP-1 Receptor Agonist Drug, Rybelsus (Semaglutide Oral) Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.132 Approved GLP-1 Receptor Agonist Drug, Saxenda (Liraglutide) Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.133 Approved GLP-1 Receptor Agonist Drug, Trulicity (Dulaglutide) Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.134 Approved GLP-1 Receptor Agonist Drug, Victoza (Liraglutide) Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.135 Approved GLP-1 Receptor Agonist Drug, Wegovy (Semaglutide Subcutaneous) Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD
- Table 34.136 Approved GLP-1 Receptor Agonist Drug, XULTOPHY (Insulin Degludec / Liraglutide) Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.137 Approved GLP-1 Receptor Agonist Drug, Zepbound (Tirzepatide) Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.138 Phase III GLP-1 Receptor Agonist Drug, GMA102 / Glutazumab Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.139 Phase III GLP-1 Receptor Agonist Drug, JY09 Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.140 Phase III GLP-1 Receptor Agonist Drug, LY3298176 / Tirzepatide Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.141 Phase III GLP-1 Receptor Agonist Drug, Mazdutide / LY3305677/ IBI-362 Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Bi
- Table 34.142 Phase III GLP-1 Receptor Agonist Drug, Orforglipron / LY3502970 Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.143 Phase III GLP-1 Receptor Agonist Drug, PB-119 / PEG-exenatide / Polyethylene glycol exenatide Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.144 Phase III GLP-1 Receptor Agonist Drug, Retatrutide / LY3437943 Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.145 Phase III GLP-1 Receptor Agonist Drug, Semaglutide Oral Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.146 Phase III GLP-1 Receptor Agonist Drug, Semaglutide Subcutaneous Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.147 Phase III GLP-1 Receptor Agonist Drug, Survodutide / BI 456906 Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.148 Phase III GLP-1 Receptor Agonist Drug, XW003 / Ecnoglutide Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.149 Phase III GLP-1 Receptor Agonist Drug, YN011-isupaglutide Sales Forecast, Till 2035, Conservative, Base and Optimistic Scenario (USD Billion)
- Table 34.150 GLP-1 Receptor Agonist Market: Distribution by Leading Drug Developers (in terms of GLP-1 drug sales in 2020 (USD Billion))
- Table 34.151 GLP-1 Receptor Agonist Market: Distribution by Leading Drug Developers (in terms of GLP-1 drug sales in the Current Year (USD Billion))
- Table 34.152 GLP-1 Receptor Agonist Market: Distribution by Leading Drug Developers (in terms of GLP-1 drug sales estimated in 2035 (USD Billion))
List of Figures
- Figure 2.1 Research Methodology: Project Methodology
- Figure 2.2 Research Methodology: Data Sources for Secondary Research
- Figure 2.3 Research Methodology: Robust Quality Control
- Figure 3.1 Market Dynamics: Forecast Methodology
- Figure 3.2 Market Dynamics: Market Assessment Framework
- Figure 4.1 Lessons Learnt from Past Recessions
- Figure 5.1 Executive Summary: Market Landscape
- Figure 5.2 Executive Summary: Market Trends
- Figure 5.3 Executive Summary: Market Forecast and Opportunity Analysis
- Figure 6.1 Advantage of GLP-1 Drugs
- Figure 6.2 Challenges Associated with GLP-1 Receptor Agonist
- Figure 6.3 Mechanisms of Action of GLP-1 Receptor Agonist
- Figure 7.1 GLP-1 Receptor Agonist: Distribution by Status of Development
- Figure 7.2 GLP-1 Receptor Agonist: Distribution by Type of Molecule
- Figure 7.3 GLP-1 Receptor Agonist: Distribution by Active Compound Used
- Figure 7.4 GLP-1 Receptor Agonist: Distribution by Type of Agonist
- Figure 7.5 GLP-1 Receptor Agonist: Distribution by Route of Administration
- Figure 7.6 GLP-1 Receptor Agonist: Distribution by Dosing Frequency
- Figure 7.7 GLP-1 Receptor Agonist: Distribution by Type of Therapy
- Figure 7.8 GLP-1 Receptor Agonist: Distribution by Target Indication
- Figure 7.9 GLP-1 Receptor Agonist: Distribution by Therapeutic Area
- Figure 7.10 GLP-1 Receptor Agonist Developer: Distribution by Year of Establishment
- Figure 7.11 GLP-1 Receptor Agonist Developer: Distribution by Company Size
- Figure 7.12 GLP-1 Receptor Agonist Developer: Distribution by Location of Headquarters
- Figure 7.13 GLP-1 Receptor Agonist Developer: Distribution by Location of Headquarters (Country) and Status of Development
- Figure 7.14 Most Active Developers: Distribution by Number of Drugs
- Figure 8.1 Company Competitiveness Analysis: GLP-1 Receptor Agonist Developers based in North America
- Figure 8.2 Company Competitiveness Analysis: GLP-1 Receptor Agonist Developers based in Europe
- Figure 8.3 Company Competitiveness Analysis: GLP-1 Receptor Agonist Developers based in Asia-Pacific and Rest of the World
- Figure 9.1 AstraZeneca: Annual Revenues, Since FY 2021 (USD Billion)
- Figure 9.2 D&D Pharmatech: Annual Revenues, Since FY 2021 (Korean Won Billion)
- Figure 9.3 Eli Lilly: Annual Revenues, Since FY 2021 (USD Billion)
- Figure 9.4 Novo Nordisk: Annual Revenues, Since FY 2021 (DKK Billion)
- Figure 9.5 Pfizer: Annual Revenues, Since FY 2021 (USD Billion)
- Figure 9.6 Sanofi: Annual Revenues, Since FY 2021 (EUR Billion)
- Figure 9.7 Tonghua Dongbao Pharmaceutical: Annual Revenues, Since FY 2021 (RMB Billion)
- Figure 9.8 Vivani: Annual Revenues, Since FY 2021 (RMB Billion)
- Figure 11.1 Partnerships and Collaborations: Distribution by Year of Partnership, Since 2022
- Figure 11.2 Partnerships and Collaborations: Distribution by Type of Partnership
- Figure 11.3 Partnerships and Collaborations: Distribution by Year of Partnership and Type of Partnership
- Figure 11.4 Partnerships and Collaborations: Distribution by Focus Area
- Figure 11.5 Most Active Players: Distribution by Number of Partnerships
- Figure 11.6 Partnerships and Collaborations: Distribution by Intracontinental and Intercontinental Deals
- Figure 11.7 Partnerships and Collaborations: Distribution by Local and International Deals
- Figure 12.1 Funding and Investments: Cumulative Year-wise Distribution of Funding Instances, Since 2021
- Figure 12.2 Funding and Investments: Cumulative Year-wise Distribution of Amount Invested (USD Million), Since 2021
- Figure 12.3 Funding and Investments: Distribution by Year of Funding and Amount Invested (USD Million), Since 2021
- Figure 12.4 Funding and Investments: Distribution by Type of Funding
- Figure 12.5 Funding and Investments: Distribution by Year and Type of Funding, Since 2021
- Figure 12.6 Funding and Investments: Distribution by Amount Invested and Type of Funding
- Figure 12.7 Funding and Investments: Distribution by Purpose of Funding
- Figure 12.8 Funding and Investments: Distribution by Geography
- Figure 12.9 Most Active Players: Distribution by Number of Instances
- Figure 12.10 Most Active Players: Distribution by Amount Invested (USD Million)
- Figure 12.11 Leading Investors: Distribution by Number of Funding Instances
- Figure 12.12 Funding and Investment Summary, Since 2021
- Figure 13.1 Distribution by Trial Registration Year, Since 2021
- Figure 13.2 Distribution of Enrolled Patient Population by Trial Registration Year
- Figure 13.3 Distribution by Trial Status
- Figure 13.4 Distribution of Enrolled Patient Population by Trial Status
- Figure 13.5 Distribution by Trial Registration Year and Trial Status
- Figure 13.6 Distribution by Trial Phase
- Figure 13.7 Distribution of Enrolled Patient Population by Trial Phase
- Figure 13.8 Distribution by Type of Sponsor / Collaborator
- Figure 13.9 Distribution by Study Design
- Figure 13.10 Distribution by Gender
- Figure 13.11 Leading Industry Players: Distribution by Number of Registered Trials
- Figure 13.12 Leading Non-industry Players: Distribution by Number of Registered Trials
- Figure 13.13 Distribution of by Trial Status, Trial Phase and Geography
- Figure 13.14 Distribution by Geography
- Figure 13.15 Distribution by Trial Status and Geography
- Figure 13.16 Distribution of Enrolled Patient Population by Trial Status and Geography
- Figure 14.1 Patent Analysis: Distribution by Type of Patent
- Figure 14.2 Patent Analysis: Cumulative Distribution by Patent Publication Year, Since 2021
- Figure 14.3 Patent Analysis: Distribution by Type of Patent and Publication Year, Since 2021
- Figure 14.4 Patent Analysis: Distribution by Patent Application Year, Since Pre-2019
- Figure 14.5 Patent Analysis: Patent Jurisdiction
- Figure 14.6 Patent Analysis: Distribution by CPC Symbols
- Figure 14.7 Leading Industry Players: Distribution by Number of Patents
- Figure 14.8 Leading Non-Industry Players: Distribution by Number of Patents
- Figure 14.9 Patent Benchmarking Analysis: Distribution of Patent Characteristics (CPC Codes) by Leading Industry Players
- Figure 14.10 Patent Benchmarking Analysis: Distribution of Leading Industry Players by Patent Characteristics (CPC Codes)
- Figure 14.11 Patent Analysis: Distribution by Patent Age
- Figure 14.12 GLP-1 Receptor Agonist: Patent Valuation
- Figure 15.1 Global Annual Demand for GLP-1 Drugs, Since 2020 (in units)
- Figure 15.2 Global Demand for GLP-1 Receptor Agonist: Distribution by Type of Molecule (in units)
- Figure 15.3 Global Demand for GLP-1 Receptor Agonist: Distribution by Type of Active Compound Used (in units)
- Figure 15.4 Global Demand for GLP-1 Receptor Agonist: Distribution by Type of GLP-1 Agonist Drugs (in units)
- Figure 15.5 Global Demand for GLP-1 Receptor Agonist: Distribution by GLP-1 Agonist (in units)
- Figure 15.6 Global Demand for GLP-1 Receptor Agonist: Distribution by Route of Administration (in units)
- Figure 15.7 Global Demand for GLP-1 Receptor Agonist: Distribution by Target Indication (in units)
- Figure 15.8 Global Demand for GLP-1 Receptor Agonist: Distribution by Geography (in units)
- Figure 18.1 Global GLP-1 Receptor Agonist Market, Historical Trends (since 2020) and Forecasted Estimates (Till 2035)
- Figure 18.2 Global GLP-1 Receptor Agonist Market, Forecasted Estimates (Till 2035): Conservative Scenario
- Figure 18.3 Global GLP-1 Receptor Agonist Market, Forecasted Estimates (Till 2035): Optimistic Scenario
- Figure 19.1 GLP-1 Receptor Agonist Market: Distribution by Type of Molecule, 2020, Current Year and 2035
- Figure 19.2 GLP-1 Receptor Agonist Market for Biologics, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 19.3 GLP-1 Receptor Agonist Market for Small Molecules, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 20.1 GLP-1 Receptor Agonist Market: Distribution by Type of Active Compound Used, 2020, Current Year and 2035
- Figure 20.2 GLP-1 Receptor Agonist Market for Dulaglutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 20.3 GLP-1 Receptor Agonist Market for Liraglutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 20.4 GLP-1 Receptor Agonist Market for Orforglipron, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 20.5 GLP-1 Receptor Agonist Market for Retatrutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 20.6 GLP-1 Receptor Agonist Market for Semaglutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 20.7 GLP-1 Receptor Agonist Market for Survodutide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 20.8 GLP-1 Receptor Agonist Market for Tirzepatide, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 20.9 GLP-1 Receptor Agonist Market for Other Active Compounds, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 21.1 GLP-1 Receptor Agonist Market: Distribution by Type of GLP-1 Agonist Drugs, 2020, Current Year and 2035
- Figure 21.2 GLP-1 Receptor Agonist Market for Long-acting GLP-1 Agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 21.3 GLP-1 Receptor Agonist Market for Short-acting GLP-1 Agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 22.1 GLP-1 Receptor Agonist Market: Distribution by GLP-1 Agonist, 2020, Current Year and 2035
- Figure 22.2 GLP-1 Receptor Agonist Market for Single-agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 22.3 GLP-1 Receptor Agonist Market for Dual-agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 22.4 GLP-1 Receptor Agonist Market for Tri-agonist, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 23.1 GLP-1 Receptor Agonist Market: Distribution by Route of Administration, 2020, Current Year and 2035
- Figure 23.2 GLP-1 Receptor Agonist Market for Oral Route, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 23.3 GLP-1 Receptor Agonist Market for Parental Route, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 24.1 GLP-1 Receptor Agonist Market: Distribution by Target Indication, 2020, Current Year and 2035
- Figure 24.2 GLP-1 Receptor Agonist Market for Alzheimer's Disease, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 24.3 GLP-1 Receptor Agonist Market for Non-Alcoholic Steatohepatitis, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 24.4 GLP-1 Receptor Agonist Market for Obesity, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 24.5 GLP-1 Receptor Agonist Market for Sleep Apnea, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 24.6 GLP-1 Receptor Agonist Market for Type 2 Diabetes, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.1 GLP-1 Receptor Agonist Market: Distribution by Geographical Regions, 2020, Current Year and 2035
- Figure 25.2 GLP-1 Receptor Agonist Market in North America: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 25.3 GLP-1 Receptor Agonist Market in the US: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.4 GLP-1 Receptor Agonist Market in Canada: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.5 GLP-1 Receptor Agonist Market in Europe: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.6 GLP-1 Receptor Agonist Market in Germany: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.7 GLP-1 Receptor Agonist Market in France: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.8 GLP-1 Receptor Agonist Market in the UK: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.9 GLP-1 Receptor Agonist Market in Italy: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.10 GLP-1 Receptor Agonist Market in Spain: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.11 GLP-1 Receptor Agonist Market in Rest of Europe: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.12 GLP-1 Receptor Agonist Market in Asia-Pacific: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.13 GLP-1 Receptor Agonist Market in China: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.14 GLP-1 Receptor Agonist Market in Japan: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.15 GLP-1 Receptor Agonist Market in South Korea: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.16 GLP-1 Receptor Agonist Market in Australia: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.17 GLP-1 Receptor Agonist Market in Rest of Asia-Pacific: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.18 GLP-1 Receptor Agonist Market in Latin America: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.19 GLP-1 Receptor Agonist Market in Brazil: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.20 GLP-1 Receptor Agonist Market in Argentina: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 25.21 GLP-1 Receptor Agonist Market in Rest of Latin America: Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- Figure 26.1 Approved GLP-1 Receptor Agonist Drug, Feisumei (Benaglutide) Sales Forecast, Till 2035 (USD Billion)
- Figure 26.2 Approved GLP-1 Receptor Agonist Drug, Fu Laimei (Polyethylene Glycol Loxenatide) Sales Forecast, Till 2035 (USD Billion)
- Figure 26.3 Approved GLP-1 Receptor Agonist Drug, Mounjaro (Tirzepatide) Sales Forecast, Till 2035 (USD Billion)
- Figure 26.4 Approved GLP-1 Receptor Agonist Drug, Ozempic (Semaglutide Subcutaneous) Sales Forecast, Till 2035 (USD Billion)
- Figure 26.5 Approved GLP-1 Receptor Agonist Drug, Rybelsus (Semaglutide Oral) Sales Forecast, Till 2035 (USD Billion)
- Figure 26.6 Approved GLP-1 Receptor Agonist Drug, Saxenda (Liraglutide) Sales Forecast, Till 2035 (USD Billion)
- Figure 26.7 Approved GLP-1 Receptor Agonist Drug, Trulicity (Dulaglutide) Sales Forecast, Till 2035 (USD Billion)
- Figure 26.8 Approved GLP-1 Receptor Agonist Drug, Victoza (Liraglutide) Sales Forecast, Till 2035 (USD Billion)
- Figure 26.9 Approved GLP-1 Receptor Agonist Drug, Wegovy (Semaglutide Subcutaneous) Sales Forecast, Till 2035 (USD Billion)
- Figure 26.10 Approved GLP-1 Receptor Agonist Drug, XULTOPHY (Insulin Degludec / Liraglutide) Sales Forecast, Till 2035 (USD Billion)
- Figure 26.11 Approved GLP-1 Receptor Agonist Drug, Zepbound (Tirzepatide) Sales Forecast, Till 2035 (USD Billion)
- Figure 26.12 Phase III GLP-1 Receptor Agonist Drug, GMA102 / Glutazumab Sales Forecast, Till 2035 (USD Billion)
- Figure 26.13 Phase III GLP-1 Receptor Agonist Drug, JY09 Sales Forecast, Till 2035 (USD Billion)
- Figure 26.14 Phase III GLP-1 Receptor Agonist Drug, LY3298176 / Tirzepatide Sales Forecast, Till 2035 (USD Billion)
- Figure 26.15 Phase III GLP-1 Receptor Agonist Drug, Mazdutide / LY3305677/ IBI-362 Sales Forecast, Till 2035 (USD Billion)
- Figure 26.16 Phase III GLP-1 Receptor Agonist Drug, Orforglipron / LY3502970 Sales Forecast, Till 2035 (USD Billion)
- Figure 26.17 Phase III GLP-1 Receptor Agonist Drug, PB-119 / PEG-exenatide / Polyethylene glycol exenatide Sales Forecast, Till 2035 (USD Billion)
- Figure 26.18 Phase III GLP-1 Receptor Agonist Drug, Retatrutide / LY3437943 Sales Forecast, Till 2035 (USD Billion)
- Figure 26.19 Phase III GLP-1 Receptor Agonist Drug, Semaglutide Oral Sales Forecast, Till 2035 (USD Billion)
- Figure 26.20 Phase III GLP-1 Receptor Agonist Drug, Semaglutide Subcutaneous Sales Forecast, Till 2035 (USD Billion)
- Figure 26.21 Phase III GLP-1 Receptor Agonist Drug, Survodutide / BI 456906 Sales Forecast, Till 2035 (USD Billion)
- Figure 26.22 Phase III GLP-1 Receptor Agonist Drug, XW003 / Ecnoglutide Sales Forecast, Till 2035 (USD Billion)
- Figure 26.23 Phase III GLP-1 Receptor Agonist Drug, YN011-isupaglutide Sales Forecast, Till 2035 (USD Billion)
- Figure 27.1 GLP-1 Receptor Agonist Market: Distribution by Leading Drug Developers (in terms of GLP-1 drug sales in 2020 (USD Billion))
- Figure 27.2 GLP-1 Receptor Agonist Market: Distribution by Leading Drug Developers (in terms of GLP-1 drug sales in the Current Year (USD Billion))
- Figure 27.3 GLP-1 Receptor Agonist Market: Distribution by Leading Drug Developers (in terms of GLP-1 drug sales estimated in 2035 (USD Billion))

