PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2061403
PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2061403
Veterinary Reference Laboratory Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035
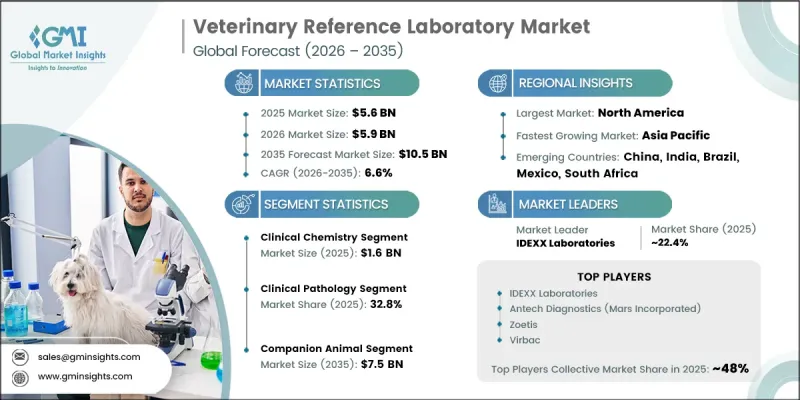
The Global Veterinary Reference Laboratory Market was valued at USD 5.6 billion in 2025 and is estimated to grow at a CAGR of 6.6% to reach USD 10.5 billion by 2035.
Veterinary reference laboratories play a vital role in identifying and monitoring zoonotic diseases affecting both domestic and farm animals. These laboratories provide a broad range of diagnostic services, including bacteriology, clinical pathology, virology, toxicology, and reproductive testing. In addition, they support veterinary healthcare through advanced technologies such as molecular diagnostics, hematology, and immunodiagnostic testing. Rising pet ownership worldwide is significantly increasing demand for animal healthcare and diagnostic services. Growing awareness among pet owners regarding the importance of early disease detection and preventive healthcare is further accelerating the adoption of specialized laboratory testing. Demand for advanced diagnostics related to chronic conditions, metabolic disorders, and infectious diseases in companion animals continues to rise steadily. In the livestock sector, increasing focus on animal health monitoring and food safety compliance is also driving the need for advanced veterinary diagnostics. Supportive government initiatives aimed at improving animal disease management and veterinary healthcare infrastructure are encouraging both public and private investments across the market. Furthermore, expanding partnerships between veterinary clinics and reference laboratories, along with network expansion strategies adopted by major companies, are improving accessibility to diagnostic services in developing regions.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $5.6 Billion |
| Forecast Value | $10.5 Billion |
| CAGR | 6.6% |
The clinical chemistry segment reached USD 1.6 billion in 2025. Clinical chemistry testing plays a crucial role in evaluating organ functionality, metabolic conditions, and electrolyte balance through the analysis of blood and other biological samples. These diagnostic procedures are widely used for identifying disorders related to liver function, kidney health, endocrine systems, and metabolic conditions in both companion and livestock animals. The rising prevalence of chronic health conditions among pets is significantly increasing demand for clinical chemistry diagnostics, contributing to segment growth across veterinary healthcare facilities.
The clinical pathology segment accounted for 32.8% share in 2025. The segment continues to maintain strong market presence due to its importance in routine screening, disease diagnosis, and long-term treatment management. Clinical pathology includes key diagnostic disciplines such as hematology, cytology, urinalysis, and clinical chemistry, all of which support accurate evaluation of animal health conditions. Veterinary professionals increasingly rely on these testing methods for timely diagnosis, treatment planning, and continuous patient monitoring, which continues to strengthen demand for clinical pathology services across veterinary laboratories.
North America Veterinary Reference Laboratory Market held a 44.6% share in 2025. The region continues to lead the industry due to its advanced veterinary healthcare infrastructure, high rate of pet ownership, and substantial spending on animal healthcare services. Growing awareness regarding zoonotic disease prevention, rising adoption of pet insurance, and increasing emphasis on preventive veterinary care are also contributing to regional market growth. In addition, strong investments in veterinary diagnostics and animal healthcare technologies are supporting the continued expansion of the North American veterinary reference laboratory industry.
Key companies operating in the Global Veterinary Reference Laboratory Market include Antech Diagnostics (Mars), APHA Scientific, Colorado State University, Cornell University College of Veterinary Medicine, Friedrich-Loeffler-Institut, GD Animal Health, IDEXX Laboratories, Laboklin, Neogen Corporation, Texas A&M Veterinary Medical Diagnostic Laboratory, Virbac, and Zoetis. Companies operating in the veterinary reference laboratory market are implementing multiple strategies to strengthen their competitive position and expand their global footprint. Industry participants are investing heavily in advanced diagnostic technologies, including molecular diagnostics, digital pathology, and automated testing systems, to improve testing accuracy and turnaround times. Many organizations are also focusing on expanding laboratory networks and forming strategic partnerships with veterinary clinics and healthcare providers to improve service accessibility. Acquisitions, collaborations, and geographic expansion initiatives are helping companies strengthen their presence in emerging markets. In addition, market players are emphasizing research and development activities to introduce innovative diagnostic solutions for infectious diseases and chronic animal health conditions.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research approach
- 1.3 Quality commitments
- 1.3.1 GMI AI policy and data integrity commitment
- 1.3.1.1 Source consistency protocol
- 1.3.1 GMI AI policy and data integrity commitment
- 1.4 Research trail and confidence scoring
- 1.4.1 Research trail components
- 1.4.2 Scoring components
- 1.5 Data collection
- 1.5.1 Partial list of primary sources
- 1.6 Data mining sources
- 1.6.1 Paid sources
- 1.6.1.1 Sources, by region
- 1.6.1 Paid sources
- 1.7 Base estimates and calculations
- 1.7.1 Revenue share analysis
- 1.7.2 Base year calculation
- 1.8 Forecast model
- 1.9 Research transparency addendum
- 1.9.1 Source attribution framework
- 1.9.2 Quality assurance metrics
- 1.9.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional trends
- 2.2.2 Technology trends
- 2.2.3 Application trends
- 2.2.4 Animal type trends
- 2.3 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Value addition at each stage
- 3.1.3 Factors affecting the value chain
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing pet adoption for companionship
- 3.2.1.2 Rising adoption of pet insurance and increasing animal health expenditure
- 3.2.1.3 Increasing outbreaks of animal diseases
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High cost associated with diagnostic services
- 3.2.2.2 Growing adoption of POC portable instruments
- 3.2.3 Opportunities
- 3.2.3.1 Expansion into emerging markets
- 3.2.3.2 Increasing demand for livestock and food safety testing
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape (Driven by Primary Research)
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 MEA
- 3.5 Technology and innovation landscape
- 3.5.1 Current technological trends
- 3.5.2 Emerging technologies (Driven by Primary Research)
- 3.6 Pricing analysis, 2025
- 3.7 Future market trends
- 3.8 Impact of AI and Gen AI on the market
- 3.9 Porter's analysis
- 3.10 PESTEL analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Merger and acquisition
- 4.6.2 Partnership and collaboration
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Technology, 2022 - 2035 ($ Mn)
- 5.1 Key trends
- 5.2 Clinical chemistry
- 5.3 Immunodiagnostics
- 5.3.1 ELISA
- 5.3.2 Lateral flow assays
- 5.3.3 Other immunodiagnostics assays
- 5.4 Molecular diagnostics
- 5.4.1 PCR tests
- 5.4.2 Microarray
- 5.4.3 Other molecular diagnostic services
- 5.5 Hematology
- 5.6 Urinalysis
- 5.7 Other technologies
Chapter 6 Market Estimates and Forecast, By Application, 2022 - 2035 ($ Mn)
- 6.1 Key trends
- 6.2 Clinical pathology
- 6.3 Bacteriology
- 6.4 Virology
- 6.5 Parasitology
- 6.6 Productivity testing
- 6.7 Pregnancy testing
- 6.8 Toxicology testing
- 6.9 Other applications
Chapter 7 Market Estimates and Forecast, By Animal Type, 2022 - 2035 ($ Mn)
- 7.1 Key trends
- 7.2 Companion animals
- 7.2.1 Dogs
- 7.2.2 Cats
- 7.2.3 Horses
- 7.2.4 Other companion animals
- 7.3 Livestock animals
- 7.3.1 Cattle
- 7.3.2 Swine
- 7.3.3 Poultry
- 7.3.4 Sheep and goats
- 7.3.5 Other livestock animals
Chapter 8 Market Estimates and Forecast, By Region, 2022 - 2035 ($ Mn)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Italy
- 8.3.5 Spain
- 8.3.6 Netherlands
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 Japan
- 8.4.3 India
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.6 Middle East and Africa
- 8.6.1 South Africa
- 8.6.2 Saudi Arabia
- 8.6.3 UAE
Chapter 9 Company Profiles
- 9.1 Antech Diagnostics (Mars)
- 9.2 APHA Scientific
- 9.3 Colorado State University
- 9.4 Cornell University College of Veterinary Medicine
- 9.5 Friedrich-Loeffler-Institut
- 9.6 GD Animal Health
- 9.7 IDEXX Laboratories
- 9.8 Laboklin
- 9.9 Neogen Corporation
- 9.10 Texas A&M Veterinary Medical Diagnostic Laboratory
- 9.11 Virbac
- 9.12 Zoetis

