PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2101997

PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2101997
Heavy Metal Supplements Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035
The Global Heavy Metal Supplements Market was valued at USD 31.5 billion in 2025 and is estimated to grow at a CAGR of 4.8% to reach USD 50 billion by 2035.
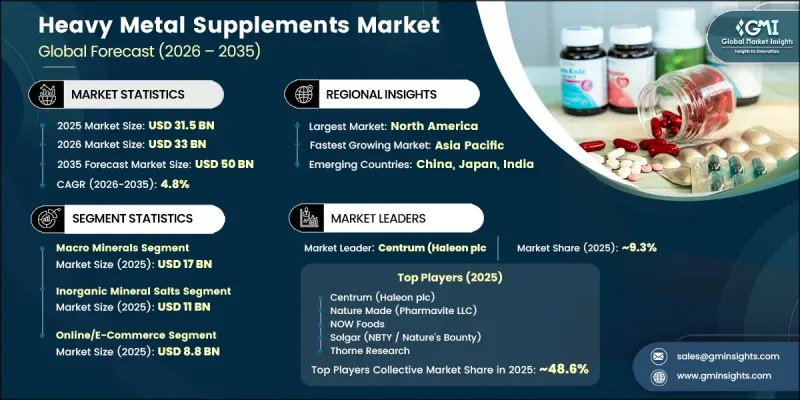
The heavy metal supplements market comprises dietary products formulated with essential metallic micronutrients that support a wide range of physiological functions within the human body. These supplements are developed to help meet daily nutritional requirements, address mineral deficiencies, and support overall health and wellness. They are available in multiple dosage forms to accommodate varying consumer preferences and nutritional needs. The market covers the complete value chain, including product development, manufacturing, distribution, and retail sales through diverse commercial and healthcare channels. Growing awareness of micronutrient deficiencies across different age groups, rising health consciousness, and increasing emphasis on preventive healthcare continue to support market expansion. Consumers are becoming more proactive about maintaining long-term wellness by incorporating mineral supplements into their daily routines. At the same time, the growing popularity of personalized nutrition, lifestyle-focused health management, and preventive wellness strategies is encouraging broader adoption of heavy metal supplements, creating favorable growth opportunities for manufacturers across developed and emerging markets.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $31.5 Billion |
| Forecast Value | $50 Billion |
| CAGR | 4.8% |
The heavy metal supplements market continues to expand across macro minerals, trace minerals, multi-mineral formulations, and emerging mineral categories as consumers place greater importance on balanced nutrition and preventive healthcare. Demand for macro mineral supplements remains strong because they support essential physiological functions associated with overall health and physical performance. Meanwhile, trace mineral products are experiencing increasing adoption due to growing consumer awareness of their contribution to immune support, metabolic health, and overall wellness. Continuous product innovation and greater nutritional awareness are further strengthening demand across all product categories.
The online and e-commerce segment was valued at USD 8.8 billion in 2025. Rising consumer preference for convenient purchasing options, broader product availability, personalized shopping experiences, and subscription-based services continues to accelerate online sales. At the same time, pharmacies, supermarkets, specialty retailers, and healthcare distribution channels remain important sales outlets due to strong consumer confidence, widespread accessibility, and the availability of professionally recommended nutritional products. The continued expansion of digital retail platforms is expected to further strengthen product accessibility and market growth.
North America Heavy Metal Supplements Market generated USD 11 billion in 2025. Rising healthcare expenditures, increasing awareness of preventive nutrition, and growing consumer interest in supporting immune health, bone health, and metabolic wellness continue to drive regional demand. Expanding availability of innovative supplement formats, stronger retail distribution networks, and broader adoption of personalized nutrition programs are creating new opportunities for market participants. In addition, favorable regulatory environments for nutraceutical products and sustained consumer spending on health and wellness continue to reinforce market expansion across North America.
The competitive landscape of the global heavy metal supplements market includes NOW Foods, Blackmores, Thorne Research, Jamieson Wellness, Centrum (Haleon plc), Solgar (NBTY / Nature's Bounty), Nature Made (Pharmavite LLC), Himalaya Drug Company, Designs for Health, Queisser Pharma (Doppelherz), Organika Health Products, and Ritual. Companies operating in the heavy metal supplements market are strengthening their competitive positions by investing in product innovation, premium formulations, and scientifically supported ingredient development to meet evolving consumer preferences. Manufacturers are expanding their product portfolios with convenient delivery formats while improving formulation quality, bioavailability, and ingredient transparency. Strategic partnerships with retailers, healthcare professionals, and online distribution platforms are helping companies increase brand visibility and improve market reach. Businesses are also investing in research and development to support personalized nutrition solutions and enhance product differentiation.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Mineral Type
- 2.2.3 Form
- 2.2.4 Dosage Form
- 2.2.5 Application
- 2.2.6 Distribution Channel
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
- 2.4.1 Executive decision points
- 2.4.2 Critical success factors
- 2.5 Future Outlook and Strategic Recommendations
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.1.5 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising awareness of mineral deficiencies
- 3.2.1.2 Growing focus on preventive healthcare
- 3.2.1.3 Expanding demand for sports nutrition
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Regulatory complexities across different regions
- 3.2.2.2 Risk of excessive mineral consumption
- 3.2.3 Market opportunities
- 3.2.3.1 Development of personalized supplement formulations
- 3.2.3.2 Increasing penetration through online retail
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.6.1 Technology and innovation landscape
- 3.6.2 Current technological trends
- 3.6.3 Emerging technologies
- 3.7 Price trends
- 3.7.1 By region
- 3.7.2 By product type
- 3.8 Future market trends
- 3.9 Technology and Innovation Landscape
- 3.9.1 Current technological trends
- 3.9.2 Emerging technologies
- 3.10 Patent Landscape
- 3.11 Trade statistics (HS code) (Note: the trade statistics will be provided for key countries only)
- 3.11.1 Major importing countries
- 3.11.2 Major exporting countries
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly initiatives
- 3.13 Carbon Footprint Considerations
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 LATAM
- 4.2.1.5 MEA
- 4.2.1 By region
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Mineral Type, 2022 - 2035 (USD Million) (Kilo Tons)
- 5.1 Key trends
- 5.2 Macro Minerals
- 5.2.1 Calcium
- 5.2.2 Magnesium
- 5.2.3 Potassium
- 5.2.4 Other Macro Minerals (Sodium, Phosphorus)
- 5.3 Trace/Micro Minerals
- 5.3.1 Iron
- 5.3.2 Zinc
- 5.3.3 Selenium
- 5.3.4 Copper
- 5.3.5 Manganese
- 5.3.6 Chromium
- 5.3.7 Molybdenum
- 5.3.8 Iodine
- 5.3.9 Others
- 5.4 Multi-Mineral Blends
- 5.4.1 Calcium + Magnesium Combinations
- 5.4.2 Zinc + Selenium Combinations
- 5.4.3 Electrolyte Mineral Formulations
- 5.4.4 Comprehensive Multi-Mineral Complexes
- 5.4.5 Targeted Mineral Duos/Trios
- 5.5 Ultra-Trace & Emerging Minerals
- 5.5.1 Boron
- 5.5.2 Vanadium
- 5.5.3 Lithium (Nutritional/Low-Dose Orotate)
- 5.5.4 Silicon (Orthosilicic Acid)
- 5.5.5 Others
Chapter 6 Market Estimates and Forecast, By Form, 2022 - 2035 (USD Million) (Kilo Tons)
- 6.1 Key trends
- 6.2 Chelated Minerals
- 6.2.1 Amino Acid Chelates
- 6.2.2 Picolinate Chelates
- 6.2.3 Citrate Chelates
- 6.2.4 Malate Chelates
- 6.2.5 Threonate Chelates
- 6.2.6 Other Chelated Forms
- 6.3 Inorganic Mineral Salts
- 6.3.1 Carbonates
- 6.3.2 Sulfates
- 6.3.3 Oxides
- 6.3.4 Chlorides & Phosphates
- 6.4 Organic Mineral Salts
- 6.4.1 Gluconates
- 6.4.2 Fumarates
- 6.4.3 Lactates & Ascorbates
- 6.4.4 Orotates
- 6.5 Colloidal & Ionic Minerals
- 6.5.1 Ionic Liquid Mineral Concentrates
- 6.5.2 Colloidal Mineral Suspensions
- 6.6 Whole Food & Fermented Mineral Complexes
- 6.6.1 Algae-Derived Minerals
- 6.6.2 Fermented Mineral Complexes
- 6.6.3 Whole Food Matrix Minerals
- 6.7 Others
- 6.7.1 Liposomal Mineral Encapsulations
- 6.7.2 Mineral-Protein Complexes
Chapter 7 Market Estimates and Forecast, By Dosage Form, 2022 - 2035 (USD Million) (Kilo Tons)
- 7.1 Key trends
- 7.2 Tablets
- 7.2.1 Standard Compressed Tablets
- 7.2.2 Enteric-Coated Tablets
- 7.2.3 Extended/Sustained-Release Tablets
- 7.2.4 Effervescent Tablets
- 7.3 Capsules
- 7.3.1 Hard-Shell Gelatin Capsules
- 7.3.2 Vegetarian/Vegan HPMC Capsules
- 7.3.3 Softgels
- 7.4 Powders
- 7.4.1 Bulk Powder
- 7.4.2 Single-Serve Stick Packs & Sachets
- 7.5 Liquids & Gels
- 7.5.1 Ionic Mineral Liquid Drops
- 7.5.2 Colloidal Mineral Suspensions
- 7.5.3 Liposomal Liquid Formulations
- 7.5.4 Syrups & Oral Solutions
- 7.6 Gummies
- 7.6.1 Gelatin-Based Gummies
- 7.6.2 Pectin-Based (Vegan) Gummies
- 7.7 Functional Food & Beverage Formats
- 7.7.1 Mineral-Fortified Ready-to-Drink (RTD) Beverages
- 7.7.2 Mineral-Fortified Nutrition Bars & Snacks
- 7.7.3 Mineral-Enriched Fortified Foods
- 7.8 Others
Chapter 8 Market Estimates and Forecast, By Application, 2022 - 2035 (USD Million) (Kilo Tons)
- 8.1 Key trends
- 8.2 General Health & Nutritional Deficiency Correction
- 8.3 Bone & Joint Health
- 8.4 Sports & Athletic Performance
- 8.5 Women's Health
- 8.6 Immune Support
- 8.7 Cardiovascular & Metabolic Health
- 8.8 Gastrointestinal Health
- 8.9 Others
Chapter 9 Market Estimates and Forecast, By Distribution Channel, 2022 - 2035 (USD Million) (Kilo Tons)
- 9.1 Key trends
- 9.2 Online/E-Commerce
- 9.3 Pharmacies & Drug Stores
- 9.4 Supermarkets & Hypermarkets
- 9.5 Health Food & Specialty Stores
- 9.6 Practitioner/Clinical Channel
- 9.7 Others
Chapter 10 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Million) (Kilo Tons)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 U.S.
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Spain
- 10.3.5 Italy
- 10.3.6 Rest of Europe
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 Australia
- 10.4.5 South Korea
- 10.4.6 Rest of Asia Pacific
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Argentina
- 10.5.4 Rest of Latin America
- 10.6 Middle East and Africa
- 10.6.1 Saudi Arabia
- 10.6.2 South Africa
- 10.6.3 UAE
- 10.6.4 Rest of Middle East and Africa
Chapter 11 Company Profiles
- 11.1 Blackmores
- 11.2 Centrum (Haleon plc)
- 11.3 Himalaya Drug Company
- 11.4 Jamieson Wellness
- 11.5 Nature Made (Pharmavite LLC)
- 11.6 NOW Foods
- 11.7 Queisser Pharma (Doppelherz)
- 11.8 Solgar (NBTY / Nature's Bounty)
- 11.9 Thorne Research
- 11.10 Designs for Health
- 11.11 Ritual
- 11.12 Organika Health Products

