PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2109178
PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2109178
North America Hose Pump Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035
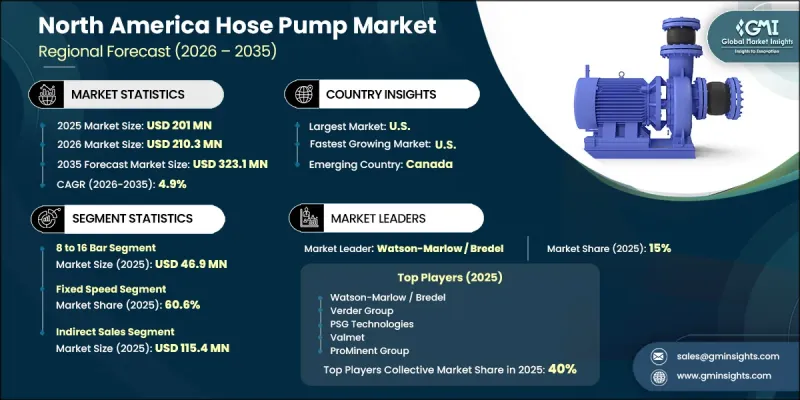
North America Hose Pump Market was valued at USD 201 million in 2025 and is estimated to grow at a CAGR of 4.9% to reach USD 323.1 million by 2035.
Strong industrial activity, ongoing investments in process automation, and the growing need for reliable fluid transfer systems continue to support market expansion across North America. Increasing demand for durable pumping technologies that can efficiently handle abrasive, viscous, and chemically aggressive materials is encouraging wider product adoption across multiple industries. The market also benefits from rising modernization of industrial facilities, continuous investments in infrastructure development, and the need for equipment that minimizes maintenance requirements while improving operational efficiency. Hose pumps remain highly valued because the transferred media stays completely enclosed within a reinforced flexible hose throughout the pumping process. This operating mechanism prevents direct contact between the fluid and the pump's internal mechanical components, reducing wear while supporting cleaner, safer, and more dependable fluid handling.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $201 Million |
| Forecast Value | $323.1 Million |
| CAGR | 4.9% |
The 8-16 bar pressure rating segment captured USD 46.9 million in 2025. This segment maintains its leadership because it satisfies the operating pressure requirements of a broad range of industrial applications that require dependable and continuous fluid transfer. Equipment within this pressure range delivers an effective balance between operational performance, durability, and installation flexibility, allowing users to manage demanding process conditions without requiring higher-pressure systems. Industries continue to favor these solutions because they provide consistent pumping performance, lower operational complexity, and reliable handling of abrasive or high-viscosity materials. In addition, manufacturers continue introducing improved hose materials and enhanced pump designs that further increase service life, operational stability, and maintenance efficiency, strengthening the market position of this pressure category across North America.
The fixed speed segment accounted for a 60.6% share in 2025. Fixed speed systems continue to dominate because they offer a straightforward operating design, competitive acquisition costs, and dependable long-term performance. These pump configurations remain the preferred option for facilities requiring consistent flow rates without the need for continuous speed adjustments. Their relatively simple mechanical construction supports easier installation, faster commissioning, and lower maintenance requirements compared with more sophisticated drive alternatives.
United States Hose Pump Market held an 83.9% share in 2025. The country remains both the largest and the fastest-growing market across the region due to its extensive industrial manufacturing base and strong investment in production infrastructure. Continuous expansion of industrial operations, rising capital expenditure on process equipment, and increasing adoption of advanced pumping technologies continue to support market growth throughout the country. A well-established industrial ecosystem, ongoing modernization initiatives, and sustained demand for high-performance fluid handling equipment further strengthen market opportunities. Companies operating in the North America hose pump market continue strengthening their competitive position by focusing on product innovation, manufacturing efficiency, and customer-centric service strategies.
Major companies operating in the North America hose pump market include global participants such as Watson-Marlow / Bredel, Verder Group, PSG Technologies, ProMinent Group, NETZSCH Group, Valmet, and Ingersoll Rand. Regional manufacturers include Wanner Engineering, Blue-White Industries, AFX Mixing & Pumping Technologies Inc., MACWORX Inc., Flomotion Systems Inc., Lutz-Jesco America Corp., and Sepro Mixing & Pumping Corp. Emerging participants include Tapflo North America and ELRO, both of which continue expanding their presence through product development, customer engagement, and broader regional market penetration. Many manufacturers invest in research and development to improve hose durability, pumping efficiency, and equipment lifespan while introducing designs that simplify maintenance and reduce operational downtime. Businesses also expand their regional distribution networks, strengthen partnerships with industrial distributors, and enhance aftermarket services to improve customer retention. Several companies prioritize customized pumping solutions that address specific operational requirements while broadening their product portfolios to serve diverse industrial applications. Strategic investments in digital monitoring capabilities, energy-efficient technologies, and production capacity further support long-term competitiveness.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Country
- 2.2.2 Pressure rating
- 2.2.3 Hose material
- 2.2.4 Drive type
- 2.2.5 Application
- 2.2.6 Distribution channel
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing water & wastewater treatment investments
- 3.2.1.2 Industrial automation adoption
- 3.2.1.3 Expansion of chemical processing industry
- 3.2.2 Industry pitfalls & challenges
- 3.2.2.1 High initial equipment cost
- 3.2.2.2 Hose replacement requirements
- 3.2.3 Opportunities
- 3.2.3.1 Infrastructure modernization
- 3.2.3.2 Water reuse and circular economy projects
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory framework
- 3.4.1 Global pump efficiency standards (EU Ecodesign Directive, DOE Pump Rule - USA)
- 3.4.2 Food safety & hygienic standards (FDA 21 CFR, EC 1935/2004, EHEDG)
- 3.4.3 Chemical handling & ATEX/IECEx compliance requirements
- 3.4.4 Water & wastewater treatment discharge regulations (US Clean Water Act)
- 3.4.5 Mining safety & environmental regulations by country
- 3.5 Pricing analysis (driven by primary research)
- 3.5.1 Historical price trend analysis (2022–2025) by pump category
- 3.5.2 Pricing strategy by player type (premium / value / cost-plus)
- 3.5.3 Price variance by hose material & pressure rating
- 3.5.4 Aftermarket pricing dynamics (replacement hose elements vs. New pump sales)
- 3.6 Trade data analysis (driven by paid database)
- 3.6.1 Import/export volume & value trends by country
- 3.6.2 Key trade corridors & tariff impact on hose pump equipment
- 3.7 Impact of AI & generative AI on the market
- 3.7.1 AI-driven disruption of existing business models
- 3.7.2 GenAI use cases & adoption roadmap by segment
- 3.7.3 Risks, limitations & regulatory considerations
- 3.8 Capacity & production landscape (driven by primary research)
- 3.8.1 Installed manufacturing capacity by region & key producer
- 3.8.2 Capacity utilization rates & expansion pipelines among leading OEMs
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By country
- 4.2.1.1 U.S.
- 4.2.1.2 Canada
- 4.2.1 By country
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Pressure Rating, 2022 – 2035 (USD Million) (Thousand Units)
- 5.1 Key trends
- 5.2 Below 2 bar
- 5.3 2 to 4 bar
- 5.4 4 to 6 bar
- 5.5 6 to 8 bar
- 5.6 8 to 16 bar
- 5.7 16 to 32 bar
- 5.8 Above 32 bar
Chapter 6 Market Estimates and Forecast, By Hose Material, 2022 – 2035 (USD Million) (Thousand Units)
- 6.1 Key trends
- 6.2 Natural rubber
- 6.3 Nitrile rubber (NBR)
- 6.4 Neoprene (CR)
- 6.5 EPDM
- 6.6 PVC
- 6.7 Polyurethane
- 6.8 Others (PTFE, CSM/Hypalon, Fluoropolymer)
Chapter 7 Market Estimates and Forecast, By Drive Type, 2022 – 2035 (USD Million) (Thousand Units)
- 7.1 Key trends
- 7.2 Fixed speed
- 7.3 Variable speed
Chapter 8 Market Estimates and Forecast, By Application, 2022 – 2035 (USD Million) (Thousand Units)
- 8.1 Key trends
- 8.2 Chemical industry
- 8.3 Mining
- 8.4 Wastewater treatment
- 8.5 Food & beverage
- 8.6 Pharmaceutical & bioprocessing
- 8.7 Others (construction, pulp & paper, energy, etc.)
Chapter 9 Market Estimates and Forecast, By Distribution Channel, 2022 – 2035 (USD Million) (Thousand Units)
- 9.1 Key trends
- 9.2 Direct sales
- 9.3 Indirect sales
Chapter 10 Market Estimates and Forecast, By Country, 2022 – 2035 (USD Million) (Thousand Units)
- 10.1 Key trends
- 10.2 U.S.
- 10.3 Canada
Chapter 11 Company Profiles
- 11.1 Global players
- 11.1.1 Watson-Marlow / Bredel
- 11.1.2 Verder Group
- 11.1.3 PSG Technologies
- 11.1.4 ProMinent Group
- 11.1.5 NETZSCH Group
- 11.1.6 Valmet
- 11.1.7 Ingersoll Rand
- 11.2 Regional players
- 11.2.1 Wanner Engineering
- 11.2.2 Blue-White Industries
- 11.2.3 AFX Mixing & Pumping Technologies Inc.
- 11.2.4 MACWORX Inc.
- 11.2.5 Flomotion Systems Inc.
- 11.2.6 Lutz-Jesco America Corp.
- 11.2.7 Sepro Mixing & Pumping Corp
- 11.3 Emerging players
- 11.3.1 Tapflo North America
- 11.3.2 ELRO

