PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2121103
PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2121103
Foldable OLED Display Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035
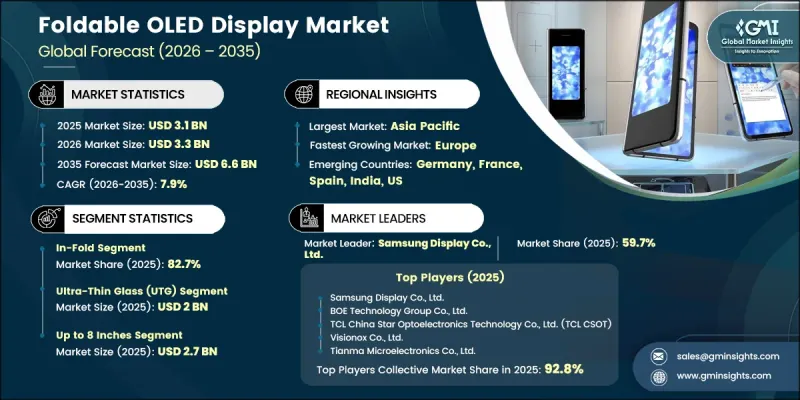
The Global Foldable OLED Display Market was valued at USD 3.1 billion in 2025 and is estimated to grow at a CAGR of 7.9% to reach USD 6.6 billion by 2035.
The market is advancing as demand for flexible display technologies continues to increase across premium consumer electronics and foldable device applications. Ongoing development of next-generation flexible OLED panels and UHG panels is improving the performance and commercial potential of foldable display solutions. Manufacturers are focusing on enhancing brightness, energy efficiency, durability, flexibility, and production yields to address evolving product requirements. The broader adoption of foldable display panels is also encouraging display manufacturers to increase production capabilities and optimize manufacturing processes. Favorable government initiatives supporting next-generation display manufacturing are creating additional opportunities for industry participants, while increasing investments in advanced production facilities are accelerating commercialization. Improvements in display materials, manufacturing precision, protective technologies, and flexible panel design are helping manufacturers overcome performance and durability challenges associated with foldable displays. Growing consumer interest in premium devices and continuous investment in display research and development are expected to support further market expansion.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $3.1 Billion |
| Forecast Value | $6.6 Billion |
| CAGR | 7.9% |
The in-fold segment accounted for an 82.7% share in 2025. In-fold display architecture is gaining preference because its inward-folding structure provides greater protection for the flexible display surface when the device is closed. The configuration can help minimize exposure to external scratches, physical contact, and other potential sources of display damage. Its combination of protection, reliability, and durability is supporting continued adoption among manufacturers and users. Ongoing improvements in flexible panel construction, hinge mechanisms, protective layers, and display materials are further enhancing the overall performance of in-fold designs. Increasing efforts to improve product durability and extend display operating life are expected to reinforce the segment's position throughout the forecast period.
The Ultra-Thin Glass (UTG) segment held USD 2 billion in 2025. UTG technology maintains a strong market position because it provides a combination of scratch resistance, optical clarity, durability, and a premium glass-like surface experience. Compared with conventional plastic-based protective materials, ultra-thin glass can provide enhanced surface characteristics while maintaining the flexibility required for foldable display applications. Continued advances in glass processing, thickness control, flexibility, and durability are helping manufacturers improve the performance of UTG solutions. Increasing emphasis on display protection and premium device quality is expected to sustain demand for ultra-thin glass throughout the forecast period.
North America Foldable OLED Display Market recorded a 17.5% share in 2025. The regional market is supported by strong consumer interest in premium electronic products and increasing acceptance of foldable devices across consumer and enterprise applications. Continued research and development spending in advanced display and semiconductor technologies is also contributing to regional growth. Manufacturers and technology companies are investing in display innovation to improve flexibility, durability, energy efficiency, and overall product performance. Growing demand for advanced display experiences, combined with ongoing technological development, is encouraging further adoption of foldable OLED technology across the region. Continued investments in next-generation display capabilities and supporting technologies are expected to create additional opportunities for market participants in North America.
Prominent companies operating in the global foldable OLED display market include Samsung Display Co., Ltd., BOE Technology Group Co., Ltd., LG Display Co., Ltd., TCL China Star Optoelectronics Technology Co., Ltd. (TCL CSOT), Tianma Microelectronics Co., Ltd., Everdisplay Optronics (EDO), and Visionox Co., Ltd. Companies in the global foldable OLED display market are strengthening their market positions through research and development, manufacturing expansion, technology optimization, strategic partnerships, and continuous product innovation. Leading manufacturers are investing in flexible OLED panel technologies to improve brightness, durability, power efficiency, optical performance, and production yields. Businesses are also increasing manufacturing capabilities and optimizing production processes to support growing demand and improve cost efficiency. Strategic collaborations across the display technology ecosystem are helping companies accelerate innovation and strengthen supply capabilities. Manufacturers are focusing on advanced protective materials, flexible substrates, ultra-thin glass, and improved panel structures to enhance product reliability. Expanding technology portfolios allows companies to address changing requirements across different applications and product categories. Companies are also strengthening their global manufacturing networks and investing in advanced production facilities to improve scalability. These strategies are helping industry participants enhance technological capabilities, expand customer relationships, improve manufacturing efficiency, and reinforce their competitive foothold in the global foldable OLED display market.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 – 2035
- 2.2 Key market trends
- 2.2.1 Folding architecture trends
- 2.2.2 Cover window material trends
- 2.2.3 Panel size trends
- 2.2.4 Application trends
- 2.2.5 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising adoption of foldable smartphones and premium consumer electronics
- 3.2.1.2 Continuous advancements in flexible OLED materials and ultra-thin glass (UTG) technologies
- 3.2.1.3 Expansion of OLED displays into automotive and smart mobility applications
- 3.2.1.4 Government support for advanced semiconductor and display manufacturing ecosystems
- 3.2.1.5 Increasing investments in next-generation OLED manufacturing capacity and production efficiency
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High manufacturing costs of foldable OLED panels and advanced materials
- 3.2.2.2 Durability and reliability concerns associated with foldable displays
- 3.2.3 Market opportunities
- 3.2.3.1 Increasing foldable OLED applications in automotive, laptops, and smart devices
- 3.2.3.2 Development of next-generation OLED materials and scalable manufacturing technologies
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter’s analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Folding Architecture, 2022 – 2035 (USD Million)
- 5.1 Key trends
- 5.2 In-fold
- 5.3 Out-fold
- 5.4 Multi-fold
Chapter 6 Market Estimates and Forecast, By Cover Window Material, 2022 – 2035 (USD Million)
- 6.1 Key trends
- 6.2 Ultra-thin glass (UTG)
- 6.3 Colorless polyimide (CPI) / plastic film
Chapter 7 Market Estimates and Forecast, By Panel Size, 2022 – 2035 (USD Million)
- 7.1 Key trends
- 7.2 Up to 8 inches
- 7.3 Above 8 inches to 13 inches
- 7.4 Above 13 inches
Chapter 8 Market Estimates and Forecast, By Application, 2022 – 2035 (USD Million)
- 8.1 Key trends
- 8.2 Smartphones
- 8.3 Tablets
- 8.4 Laptops
- 8.5 Automotive displays
- 8.6 Others
Chapter 9 Market Estimates and Forecast, By Region, 2022 – 2035 (USD Million)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 Middle East and Africa
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global Key Players
- 10.1.1 Samsung Display Co., Ltd.
- 10.1.2 BOE Technology Group Co., Ltd.
- 10.1.3 TCL China Star Optoelectronics Technology Co., Ltd. (TCL CSOT)
- 10.1.4 Visionox Co., Ltd.
- 10.1.5 Tianma Microelectronics Co., Ltd.
- 10.2 Regional key players
- 10.2.1 Asia Pacific
- 10.2.1.1 LG Display Co., Ltd.
- 10.2.1.2 Everdisplay Optronics (EDO)
- 10.2.1 Asia Pacific

