PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2121177
PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2121177
Inspection Robot Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035
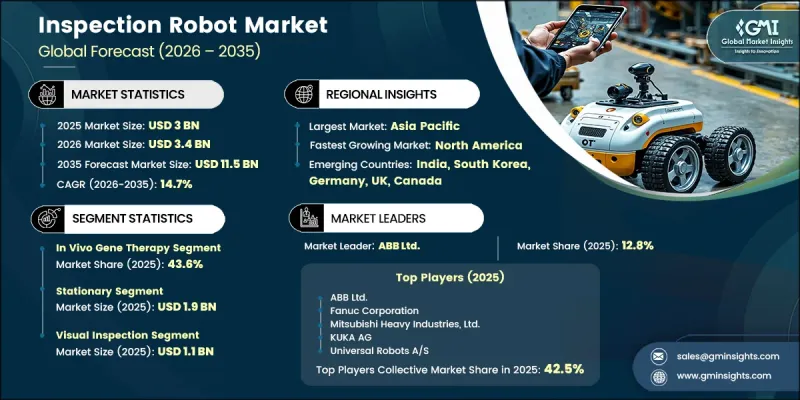
The Global Inspection Robots Market was valued at USD 3 billion in 2025 and is estimated to grow at a CAGR of 14.7% to reach USD 11.5 billion by 2035.
Market expansion is supported by the accelerating adoption of industrial automation across multiple sectors, increasingly stringent workplace safety requirements, and stronger compliance standards for hazardous operating conditions. The expansion of digital infrastructure across energy and utility networks is creating additional opportunities for robotic inspection technologies. Growing investment in AI-enabled predictive maintenance is also encouraging organizations to deploy automated systems capable of identifying equipment conditions and supporting maintenance planning. At the same time, industries are increasingly adopting intelligent approaches to inspect assets, machinery, and infrastructure. Demand is developing across energy and utilities, construction, manufacturing, and other industrial environments as businesses seek to improve inspection efficiency, strengthen operational reliability, reduce human exposure to dangerous conditions, and support continuous asset monitoring.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $3 Billion |
| Forecast Value | $11.5 Billion |
| CAGR | 14.7% |
The inspection robots market is gaining momentum as manufacturers and industrial operators accelerate the adoption of automation and Industry 4.0 technologies. Digital transformation initiatives are encouraging businesses to deploy robotic systems that can perform inspection activities while supporting production continuity and identifying potential equipment issues at an earlier stage. Automated inspection can help organizations improve operational efficiency, reduce unplanned downtime, and maintain consistent monitoring standards. Workplace safety requirements are providing another important growth driver as regulations increasingly encourage businesses to limit direct worker exposure to dangerous industrial environments. Inspection robots allow operators to conduct remote assessments and maintenance-related activities while reducing the need for personnel to enter potentially hazardous locations.
The semi-autonomous segment accounted for a 43.6% share in 2025. Semi-autonomous inspection robots combine automated navigation and operational capabilities with human oversight, creating a balance between robotic efficiency and human decision-making. This operating model can improve inspection accuracy, operational dependability, and compatibility with existing industrial systems. The ability to retain human involvement in important inspection decisions makes these robots suitable for applications where technical judgment and regulatory requirements remain essential. Demand for semi-autonomous systems is supported by their use across manufacturing, oil and gas, utilities, mining, and infrastructure inspection.
The stationary segment generated USD 1.9 billion in 2025. Increasing adoption of fixed robotic inspection systems is supporting the segment's strong position as manufacturers seek reliable automation for controlled inspection environments. Stationary robots provide high levels of precision, consistency, and repeatability, allowing organizations to automate recurring inspection activities and maintain standardized quality requirements. Their capabilities are particularly valuable in environments where inspection tasks need to be performed repeatedly with minimal variation. Manufacturers are increasingly integrating stationary robotic systems into automated production and testing operations as they seek to improve product quality, optimize production workflows, and reduce manual inspection requirements.
North America Inspection Robots Market held a 30.5% share in 2025. Regional growth is being supported by expanding industrial automation, broader implementation of Industry 4.0 technologies, and strict workplace safety requirements across manufacturing, energy and utilities, and critical infrastructure. Organizations are increasingly evaluating automated inspection systems to reduce personnel exposure to dangerous operating conditions while improving productivity and inspection consistency. Regulatory agencies, energy organizations, and industrial operators are encouraging the adoption of technologies that can strengthen workplace safety and improve operational performance. The region's established industrial base, continued investment in automation, and increasing focus on advanced inspection technologies are creating favorable conditions for robotic solutions.
Prominent companies operating in the global inspection robots market include FANUC CORPORATION, ABB Ltd., Cognex Corporation, Denso Wave, DSI Robotics, Energy Robotics GmbH, Honeybee Robotics, Ltd., Innok Robotics GmbH, JH Robotics, Inc., KUKA AG, Mitsubishi Heavy Industries, Ltd., Nexxis, Robotnik Automation S.L., Staubli, SuperDroid Robotics, and Universal Robots A/S. Companies in the inspection robots market are strengthening their market presence by investing in robotics research and development, artificial intelligence, machine vision, autonomous navigation, and advanced sensing technologies. Participants are expanding product portfolios to address different inspection requirements across industrial environments and infrastructure applications. Strategic partnerships with technology providers, industrial operators, system integrators, and research organizations are helping companies accelerate product development and improve commercial reach. Businesses are also focusing on software enhancements that improve robotic perception, data analysis, remote operation, and predictive maintenance capabilities. Geographic expansion and stronger distribution networks are enabling suppliers to reach new customers and industrial markets.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 – 2035
- 2.2 Key market trends
- 2.2.1 Type trends
- 2.2.2 Technology trends
- 2.2.3 Application trends
- 2.2.4 End-use industry trends
- 2.2.5 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factors affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing industrial automation and Industry 4.0 adoption
- 3.2.1.2 Rising worker safety regulations and demand for remote inspection in hazardous environments
- 3.2.1.3 Growing investments in predictive maintenance and digital asset management
- 3.2.1.4 Expanding inspection requirements for aging energy, utility, and critical infrastructure assets
- 3.2.1.5 Rapid advancements in AI, autonomous navigation, machine vision, and industrial sensing technologies
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High initial deployment and integration costs
- 3.2.2.2 Limited operation in complex and unstructured environments
- 3.2.3 Market opportunities
- 3.2.3.1 Expansion of AI-powered autonomous inspection and predictive maintenance
- 3.2.3.2 Growing adoption across energy, utilities, and critical infrastructure inspection
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter’s analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/Startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Type, 2022 – 2035 (USD Million)
- 5.1 Key trends
- 5.2 Non-autonomous
- 5.3 Semi-autonomous
- 5.4 Fully Autonomous
Chapter 6 Market Estimates and Forecast, By Technology, 2022 – 2035 (USD Million)
- 6.1 Key trends
- 6.2 Stationary
- 6.3 Mobile
Chapter 7 Market Estimates and Forecast, By Application, 2022 – 2035 (USD Million)
- 7.1 Key trends
- 7.2 Visual inspection
- 7.3 Ultrasonic inspection
- 7.4 Laser scanning inspection
- 7.5 Thermal inspection
- 7.6 Quality inspection
Chapter 8 Market Estimates and Forecast, By End Use Industry, 2022 – 2035 (USD Million)
- 8.1 Key trends
- 8.2 Oil & gas
- 8.3 Power & utilities
- 8.4 Petrochemical
- 8.5 Automotive
- 8.6 Construction
- 8.7 Food & beverages
- 8.8 Manufacturing
- 8.9 Others
Chapter 9 Market Estimates and Forecast, By Region, 2022 – 2035 (USD Million)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 Middle East and Africa
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global Key Players
- 10.1.1 ABB Ltd.
- 10.1.2 FANUC CORPORATION
- 10.1.3 Mitsubishi Heavy Industries, Ltd.
- 10.1.4 KUKA AG
- 10.1.5 Universal Robots A/S
- 10.2 Regional key players
- 10.2.1 North America
- 10.2.1.1 Cognex Corporation
- 10.2.1.2 DSI Robotics
- 10.2.1.3 Honeybee Robotics, Ltd.
- 10.2.1.4 JH Robotics, Inc.
- 10.2.1.5 Superdroid Robotics
- 10.2.2 Asia Pacific
- 10.2.2.1 Denso Wave
- 10.2.3 Europe
- 10.2.3.1 Innok Robotics GmbH
- 10.2.3.2 Robotnik Automation S.L.
- 10.2.3.3 Staubli
- 10.2.1 North America
- 10.3 Niche Players/Disruptors
- 10.3.1 Energy Robotics GmbH
- 10.3.2 Nexxis

