PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2121178
PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2121178
Boat and Ship Telematics Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035
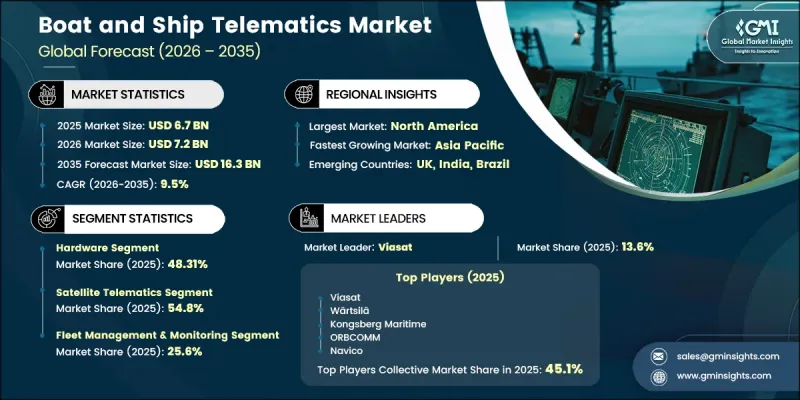
The Global Boat and Ship Telematics Market was valued at USD 6.7 billion in 2025 and is estimated to grow at a CAGR of 9.5% to reach USD 16.3 billion by 2035.
Rising maritime safety requirements and increasingly stringent environmental regulations are creating strong demand for connected vessel technologies. Regulatory authorities are placing greater emphasis on operational monitoring, emissions management, vessel security, fuel efficiency, and environmental reporting, encouraging fleet operators to integrate advanced telematics solutions. These systems give operators access to timely vessel data and help them improve operational visibility while supporting regulatory reporting requirements. The continuous evolution of maritime environmental standards is expected to further increase the need for connected monitoring capabilities across the shipping industry. At the same time, higher fuel expenses and rising operating costs are pushing vessel operators to improve fleet efficiency and control unnecessary expenditures. Telematics technology can provide greater insight into vessel operations, enabling companies to make more informed decisions regarding asset performance, fuel consumption, routing, and fleet utilization. As commercial operators increasingly prioritize cost optimization, asset productivity, and operational transparency, the adoption of boat and ship telematics solutions is expected to accelerate throughout the forecast period.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $6.7 Billion |
| Forecast Value | $16.3 Billion |
| CAGR | 9.5% |
The hardware segment accounted for the 48.31% share in 2025. Strong demand for onboard communication, positioning, monitoring, and control equipment continues to support the segment's leading position. Vessel owners and fleet operators are increasing investments in GPS/GNSS receivers, AIS transponders, satellite communication terminals, onboard sensors, marine antennas, and telematics control units. These hardware components provide the infrastructure required to collect, transmit, and process vessel-related information. Growing emphasis on navigation performance, fleet visibility, engine monitoring, fuel management, and regulatory requirements is encouraging operators to modernize onboard equipment. The expansion of connected vessel infrastructure across both commercial and recreational applications is also contributing to hardware demand. As maritime operators seek more reliable and integrated monitoring capabilities, the deployment of advanced telematics hardware is expected to remain a major component of market development.
The satellite telematics segment held 54.8% share in 2025. The segment benefits from the ability of satellite connectivity to maintain communication and data transmission across maritime areas where terrestrial networks provide limited or no coverage. This capability makes satellite-based telematics particularly important for vessels that operate across broad geographic areas and require consistent connectivity. Satellite solutions support essential maritime functions, including vessel tracking, navigation, communication, fleet supervision, and regulatory requirements. Their broad coverage enables operators to maintain access to critical vessel information even when ships travel outside conventional communication infrastructure. Continued expansion of long-distance maritime activities and growing demand for reliable vessel connectivity are expected to sustain the leading position of satellite telematics during the forecast period.
United States Boat and Ship Telematics Market held an 83.6% share, generating USD 1.9 billion in 2025. The country's strong position reflects the scale of its commercial maritime activities, established water transportation infrastructure, developed recreational boating industry, and growing acceptance of connected vessel technologies. Operators across the region are increasingly adopting telematics platforms to gain improved visibility into vessel operations and support more efficient fleet management. The presence of an established maritime technology ecosystem and increasing attention toward operational efficiency and regulatory compliance are also supporting market development.
Major companies operating in the global boat and ship telematics industry include Wartsila, Furuno Electric, ORBCOMM, Saab, Iridium Communications, Garmin, Kongsberg Maritime, Viasat, Thales, Navico Group, KVH Industries, Inmarsat, L3Harris Technologies, and other prominent industry participants. Companies in the boat and ship telematics market are pursuing several strategies to expand their market foothold and strengthen their competitive positions. Leading participants are investing in product development to improve connectivity, data accuracy, monitoring capabilities, automation, and system integration. Companies are also expanding their technology portfolios by combining telematics hardware, software, communication infrastructure, and analytics capabilities into more comprehensive solutions. Strategic collaborations, technology partnerships, distribution agreements, and geographic expansion are helping market participants reach new customer groups and strengthen regional coverage. Businesses are also focusing on improving platform scalability and interoperability so operators can integrate telematics technologies with existing maritime systems. Continued investment in research and development allows companies to introduce more efficient and reliable solutions while responding to changing regulatory requirements. In addition, providers are emphasizing customer support, service capabilities, and customized solutions to improve retention and build long-term relationships. These strategies are helping companies increase adoption, broaden their customer base, and reinforce their positions in the growing boat and ship telematics market.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Component
- 2.2.3 Technology
- 2.2.4 Function
- 2.2.5 Vessel Type
- 2.2.6 Sales Channel
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Cost structure
- 3.1.3 Profit margin
- 3.1.4 Value addition at each stage
- 3.1.5 Vertical integration trends
- 3.1.6 Disruptors
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Stringent maritime safety and environmental regulations
- 3.2.1.2 Fuel-efficiency and operating-cost reduction priorities
- 3.2.1.3 Growth in global seaborne trade
- 3.2.1.4 Maritime digitalization and automation
- 3.2.2 Market Restraints
- 3.2.2.1 High upfront costs for telematics deployment and retrofitting existing vessels.
- 3.2.2.2 Limited and expensive connectivity in remote offshore and deep-sea regions.
- 3.2.3 Market Opportunities
- 3.2.3.1 Rising demand for autonomous and remotely operated vessels is creating new opportunities for advanced telematics platforms.
- 3.2.3.2 Expansion of smart ports and digital maritime infrastructure is increasing the need for connected vessel solutions.
- 3.2.3.3 Growing adoption of predictive maintenance and AI-driven analytics offers significant potential for reducing vessel downtime.
- 3.2.3.4 Increasing digitalization of fishing fleets and inland waterways presents untapped growth opportunities for telematics providers.
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Pricing Analysis (Driven by Primary Research)
- 3.4.1 Historical Price Trend Analysis, 2022-2025
- 3.4.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.5 Regulatory landscape
- 3.5.1 North America
- 3.5.1.1 United States Coast Guard – Vessel Monitoring & AIS Regulations
- 3.5.1.2 Federal Communications Commission – Maritime Radio & Satellite Communication
- 3.5.2 Europe
- 3.5.2.1 European Maritime Safety Agency – SafeSeaNet & Maritime Digital Services
- 3.5.2.2 European Union – EU MRV Regulation
- 3.5.3 Asia-Pacific
- 3.5.3.1 Maritime and Port Authority of Singapore – Digital Port & Smart Shipping Regulations
- 3.5.3.2 Ministry of Land, Infrastructure, Transport and Tourism – Maritime Safety & Vessel Equipment Standards
- 3.5.4 Latin America
- 3.5.4.1 Brazilian Navy – Maritime Traffic & Vessel Monitoring Regulations
- 3.5.4.2 Maritime Authority of Panama – Vessel Registration & Maritime Safety Requirements
- 3.5.5 Middle East & Africa
- 3.5.5.1 Saudi Ports Authority (Mawani) – Smart Ports & Maritime Digitalization Regulations
- 3.5.5.2 South African Maritime Safety Authority – Vessel Tracking & Maritime Safety
- 3.5.1 North America
- 3.6 Technology and Innovation landscape
- 3.6.1 Current technologies
- 3.6.1.1 Satellite-Based Telematics & Connectivity
- 3.6.1.2 Cellular (4G/5G) Telematics
- 3.6.1.3 AIS-Based Vessel Tracking & Monitoring
- 3.6.1.4 GNSS/GPS-Based Positioning & Navigation
- 3.6.2 Emerging technologies
- 3.6.2.1 AI-Powered Predictive Maintenance & Vessel Analytics
- 3.6.2.2 IoT-Enabled Smart Vessel Telematics
- 3.6.2.3 Edge Computing for Real-Time Vessel Data Processing
- 3.6.2.4 Autonomous Vessel Telematics & Remote Operations
- 3.6.1 Current technologies
- 3.7 Porter’s analysis
- 3.8 PESTEL analysis
- 3.9 Cost breakdown analysis, 2025
- 3.10 Patent analysis (Driven by Primary Research)
- 3.11 Impact of AI & generative AI on the market
- 3.11.1 AI-Driven Disruption of Existing Business Models
- 3.11.2 GenAI use cases & adoption roadmap by segment
- 3.11.3 Risks, Limitations & Regulatory Considerations
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly Initiatives
- 3.12.5 Carbon footprint considerations
- 3.13 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.13.1 Base Case - key macro & industry variables driving CAGR
- 3.13.2 Optimistic Scenarios - Favorable Macro and Industry Tailwinds
- 3.13.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia-Pacific
- 4.2.4 Latin America
- 4.2.5 Middle East & Africa
- 4.3 Competitive positioning matrix
- 4.4 Key developments
- 4.4.1 Mergers & acquisitions
- 4.4.2 Partnerships & collaborations
- 4.4.3 New product launches
- 4.4.4 Expansion plans and funding
- 4.5 Company tier benchmarking
- 4.5.1 Tier classification criteria & qualifying thresholds
- 4.5.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates & Forecast, By Component, 2022 - 2035 ($Mn)
- 5.1 Key trends
- 5.2 Hardware
- 5.2.1 GPS & Navigation Systems
- 5.2.2 Sensors & IoT Devices
- 5.2.3 Satellite Transponders & Antennas
- 5.2.4 Communication Modems & Systems
- 5.2.5 Onboard Display & Interface Devices
- 5.3 Software
- 5.3.1 Fleet Management Software
- 5.3.2 Route Optimization Platforms
- 5.3.3 Remote Monitoring & Diagnostics Software
- 5.3.4 Predictive Maintenance Applications
- 5.3.5 Security & Surveillance Software
- 5.4 Services
- 5.4.1 Installation & Integration Services
- 5.4.2 Managed Connectivity Services
- 5.4.3 Data Analytics & Reporting Services
Chapter 6 Market Estimates & Forecast, By Technology, 2022 - 2035 ($Mn)
- 6.1 Key trends
- 6.2 Satellite Telematics
- 6.3 Cellular Telematics
- 6.4 Hybrid Systems
Chapter 7 Market Estimates & Forecast, By Function, 2022 - 2035 ($Mn)
- 7.1 Key trends
- 7.2 Navigation & Positioning
- 7.3 Fleet Management & Monitoring
- 7.4 Safety & Security
- 7.5 Communication & Connectivity
- 7.6 Environmental Compliance & Reporting
- 7.7 Cargo & Asset Tracking
Chapter 8 Market Estimates & Forecast, By Vessel Type, 2022 - 2035 ($Mn)
- 8.1 Key trends
- 8.2 Commercial Cargo
- 8.3 Passenger
- 8.4 Fishing & Aquaculture
- 8.5 Offshore & Energy
- 8.6 Government & Military
- 8.7 Leisure & Recreational Boats
Chapter 9 Market Estimates & Forecast, By Sales Channel, 2022 - 2035 ($Mn)
- 9.1 Key trends
- 9.2 OEM & Shipyard Integration
- 9.3 Aftermarket & Retrofit
Chapter 10 Market Estimates & Forecast, By Region, 2022 - 2035 ($Mn)
- 10.1 North America
- 10.1.1 US
- 10.1.2 Canada
- 10.2 Europe
- 10.2.1 UK
- 10.2.2 Germany
- 10.2.3 France
- 10.2.4 Italy
- 10.2.5 Spain
- 10.2.6 Belgium
- 10.2.7 Netherlands
- 10.2.8 Sweden
- 10.2.9 Russia
- 10.3 Asia Pacific
- 10.3.1 China
- 10.3.2 India
- 10.3.3 Japan
- 10.3.4 Australia
- 10.3.5 Singapore
- 10.3.6 South Korea
- 10.3.7 Vietnam
- 10.3.8 Indonesia
- 10.3.9 Thailand
- 10.4 Latin America
- 10.4.1 Brazil
- 10.4.2 Mexico
- 10.4.3 Argentina
- 10.5 MEA
- 10.5.1 South Africa
- 10.5.2 Saudi Arabia
- 10.5.3 UAE
Chapter 11 Company Profiles
- 11.1 Global Players
- 11.1.1 KVH Industries
- 11.1.2 Iridium Communications
- 11.1.3 Viasat
- 11.1.4 Saab
- 11.1.5 Kongsberg Maritime
- 11.1.6 Wartsila
- 11.1.7 Furuno Electric
- 11.1.8 Garmin
- 11.1.9 Thales
- 11.1.10 L3Harris Technologies
- 11.2 Regional Players
- 11.2.1 Raymarine
- 11.2.2 Intellian Technologies
- 11.2.3 SRT Marine Systems
- 11.2.4 Kpler
- 11.2.5 Pole Star Global
- 11.2.6 ShipIn Systems
- 11.2.7 CLS
- 11.2.8 Anschutz
- 11.2.9 ComNav Marine
- 11.2.10 Jotron

