PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2121198
PUBLISHER: Global Market Insights Inc. | PRODUCT CODE: 2121198
Cardiovascular Devices Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035
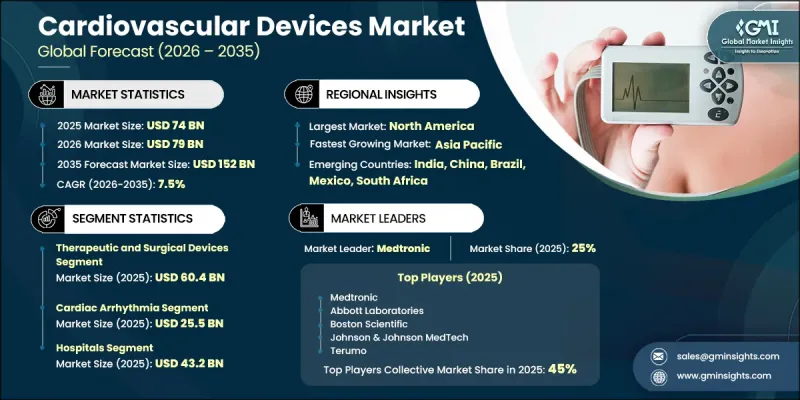
The Global Cardiovascular Devices Market was valued at USD 74 billion in 2025 and is estimated to grow at a CAGR of 7.5% to reach USD 152 billion by 2035.
The market is witnessing growth due to the increasing prevalence of cardiovascular diseases, a rapidly expanding aging population, rising healthcare investments, continuous technological advancements, and growing preference for minimally invasive treatment approaches. The rising worldwide incidence of cardiovascular conditions remains one of the primary factors supporting market expansion, as healthcare providers require more advanced solutions for disease detection, monitoring, and treatment. Increasing demand for efficient cardiac care is encouraging the adoption of innovative cardiovascular technologies, including advanced intervention systems, implantable devices, wearable monitoring solutions, and intelligent diagnostic platforms. Growing awareness regarding preventive cardiac health and improved healthcare accessibility across developing regions is also contributing to higher utilization of cardiovascular devices. Healthcare systems are increasingly focusing on early disease management, accurate diagnosis, and effective therapeutic interventions to address the growing cardiovascular disease burden. The combination of rising patient demand, technological progress, and increasing healthcare infrastructure development continues to create strong growth opportunities for the global Cardiovascular Devices Market.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $74 Billion |
| Forecast Value | $152 Billion |
| CAGR | 7.5% |
The therapeutic and surgical devices segment generated USD 60.4 billion in 2025. This segment includes a wide range of essential cardiovascular solutions designed to support cardiac treatment procedures and improve patient outcomes. These devices play a central role in interventional cardiology and cardiovascular surgeries by providing effective solutions for managing complex heart-related conditions. The segment maintains its leading position because therapeutic and surgical devices deliver critical treatment capabilities and are widely used in procedures requiring immediate and reliable cardiovascular intervention.
The hospitals segment generated USD 43.2 billion and accounted for a 58.3% share in 2025. Hospitals represent the largest end-user segment due to their advanced medical infrastructure, specialized healthcare professionals, and capability to provide comprehensive cardiovascular services. These facilities support a wide range of cardiovascular procedures, including diagnosis, intervention, surgery, and long-term patient monitoring. The availability of integrated cardiac care services, emergency treatment capabilities, and advanced medical technologies continues to strengthen hospital demand for cardiovascular devices.
North America Cardiovascular Devices Market accounted for a 41.8% share in 2025. The regional market continues to expand due to the increasing prevalence of cardiovascular diseases, strong healthcare infrastructure, and rapid adoption of advanced medical technologies. Rising cases of heart-related conditions associated with lifestyle-related risk factors continue to increase demand for innovative diagnostic and treatment solutions. Technological advancements are further supporting regional growth through the development of minimally invasive cardiovascular systems, artificial intelligence-enabled diagnostic technologies, advanced implantable devices, and remote patient monitoring solutions.
Major companies operating in the global cardiovascular devices market include Abbott Laboratories, AngioDynamics, Biotronik, Boston Scientific, Edwards, Johnson & Johnson MedTech, Koninklijke Philips, Medtronic, Meril Life Sciences, MicroPort Scientific, Olympus, Pneumbra, Relisys Medical Devices, Sahajanand Medical Technologies, Terumo, and Translumina Therapeutics. Companies operating in the cardiovascular devices market are strengthening their market positions through continuous innovation, strategic partnerships, and investments in advanced medical technologies. Leading manufacturers are focusing on developing next-generation cardiovascular devices with improved safety, accuracy, efficiency, and patient outcomes. Companies are expanding their product portfolios through research and development initiatives aimed at creating minimally invasive solutions, intelligent monitoring systems, and advanced treatment technologies. Strategic collaborations, mergers, acquisitions, and geographic expansion efforts are helping organizations enhance their market presence and strengthen their technological capabilities. Businesses are also investing in digital healthcare solutions, artificial intelligence integration, and remote monitoring technologies to improve clinical outcomes and healthcare delivery.
Table of Contents
Chapter 1 Research Methodology
- 1.1 Research approach
- 1.2 Quality commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research trail & confidence scoring
- 1.3.1 Research trail components
- 1.3.2 Scoring components
- 1.4 Data collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Device type trends
- 2.2.2 Application trends
- 2.2.3 End use trends
- 2.2.4 Regional trends
- 2.3 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing number of patients suffering from cardiovascular diseases
- 3.2.1.2 Growing integration of remote patient monitoring and connected cardiovascular devices
- 3.2.1.3 Technological advancements in cardiovascular devices
- 3.2.1.4 Rising demand for minimally invasive procedures
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High risk associated with cardiac procedures
- 3.2.2.2 Complex regulatory approval processes for cardiovascular devices
- 3.2.3 Market opportunities
- 3.2.3.1 Increasing applications of AI in cardiovascular diseases
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape (Driven by primary research)
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.5 Technology landscape (Driven by primary research)
- 3.5.1 Current technological trends
- 3.5.1.1 Advanced imaging and sensing systems for real-time cardiovascular diagnostics
- 3.5.1.2 AI-integrated cardiovascular devices for automated detection and risk stratification
- 3.5.2 Emerging technologies
- 3.5.2.1 Bioengineered and adaptive materials for next-generation cardiovascular implants and stents
- 3.5.2.2 Ultra-high-speed 3D visualization and digital twin technologies for dynamic cardiovascular assessment
- 3.5.1 Current technological trends
- 3.6 Future market trends (Driven by primary research)
- 3.7 Reimbursement scenario
- 3.8 Patent analysis
- 3.9 Pricing trend analysis
- 3.10 Impact of AI and Generative AI on the market (Driven by primary research)
- 3.11 Porter's analysis
- 3.12 PESTEL analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis by region
- 4.2.1 Global
- 4.2.2 North America
- 4.2.3 Europe
- 4.2.4 Asia Pacific
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers and acquisitions
- 4.6.2 Partnerships and collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Device Type, 2022 - 2035 ($ Mn)
- 5.1 Key trends
- 5.2 Diagnostic and monitoring devices
- 5.2.1 Electrocardiogram systems
- 5.2.2 Holter and event monitors
- 5.2.3 Remote cardiac monitoring devices
- 5.2.4 Cardiac diagnostic ultrasound
- 5.2.5 Other diagnostic and monitoring devices
- 5.3 Therapeutic and surgical devices
- 5.3.1 Catheters
- 5.3.1.1 Electrophysiology ablation catheters
- 5.3.1.2 Electrophysiology diagnostic and mapping catheters
- 5.3.1.3 Interventional catheters
- 5.3.2 Coronary intervention devices
- 5.3.2.1 Drug eluting stents
- 5.3.2.2 Bare metal stents
- 5.3.2.3 Bioresorbable scaffolds
- 5.3.2.4 PTCA balloons
- 5.3.2.5 Atherectomy devices
- 5.3.2.6 Guidewires
- 5.3.2.7 Embolic protection devices
- 5.3.2.8 Other coronary intervention devices
- 5.3.3 Cardiac rhythm management (CRM) devices
- 5.3.3.1 Pacemakers
- 5.3.3.2 Implantable cardioverter defibrillators
- 5.3.3.3 Cardiac resynchronization therapy devices
- 5.3.3.4 Implantable loop recorders
- 5.3.3.5 Other cardiac rhythm management devices
- 5.3.4 Structural heart devices
- 5.3.4.1 LAA closure devices
- 5.3.4.2 Heart valves
- 5.3.5 Cardiac surgery devices
- 5.3.5.1 Coronary artery bypass graft (CABG) surgical tools
- 5.3.5.2 Other cardiac surgical devices
- 5.3.6 Ventricular assist devices
- 5.3.1 Catheters
Chapter 6 Market Estimates and Forecast, By Application, 2022 - 2035 ($ Mn)
- 6.1 Key trends
- 6.2 Coronary artery disease
- 6.3 Cardiac arrhythmia
- 6.4 Heart failure
- 6.5 Other applications
Chapter 7 Market Estimates and Forecast, By End Use, 2022 - 2035 ($ Mn)
- 7.1 Key trends
- 7.2 Hospitals
- 7.3 Ambulatory surgical centers
- 7.4 Cardiac centers
- 7.5 Other end users
Chapter 8 Market Estimates and Forecast, By Region, 2022 - 2035 ($ Mn)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Spain
- 8.3.5 Italy
- 8.3.6 Netherlands
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 Japan
- 8.4.3 India
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.6 Middle East and Africa
- 8.6.1 South Africa
- 8.6.2 Saudi Arabia
- 8.6.3 UAE
Chapter 9 Company Profiles
- 9.1 Abbott Laboratories
- 9.2 AngioDynamics
- 9.3 Biotronik
- 9.4 Boston Scientific
- 9.5 Edwards
- 9.6 Johnson & Johnson MedTech
- 9.7 Koninklijke Philips
- 9.8 Medtronic
- 9.9 Meril Life Sciences
- 9.10 MicroPort Scientific
- 9.11 Olympus
- 9.12 Pneumbra
- 9.13 Relisys Medical Devices
- 9.14 Sahajanand Medical Technologies
- 9.15 Terumo
- 9.16 Translumina Therapeutics

