PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2129350
PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2129350
Data Center Air Handling Units Market by Type, Capacity, Data Center Type (Hyperscale, Enterprise, Colocation Providers), and Region - Global Forecast to 2032
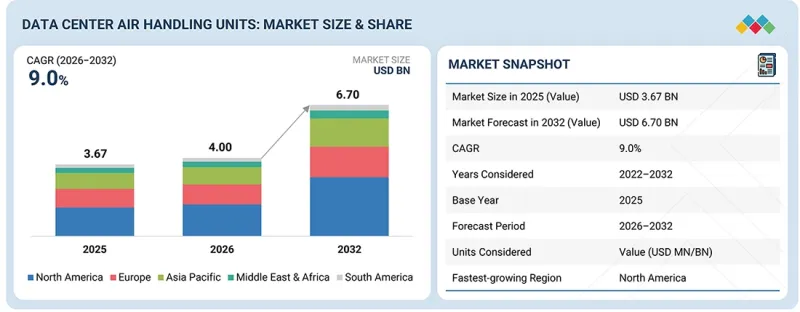
The data center air handling units market is projected to grow from USD 4.00 billion in 2026 to USD 6.70 billion by 2032, at a CAGR of 9.0% during the forecast period. The increasing adoption of artificial intelligence (AI), generative AI, high-performance computing (HPC), and cloud computing is the primary driver of the global data center air handling units market.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2022-2032 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Units Considered | Value (USD Million/Billion) |
| Segments | Data Center Type, Type, Capacity, and Region |
| Regions covered | Asia Pacific, Europe, North America, Middle East & Africa, and South America |
AI servers equipped with advanced GPUs and accelerators from companies such as NVIDIA, AMD, and Intel generate substantially higher heat loads than conventional server architectures, pushing rack power densities from traditional 5-15 kW to 50-100 kW and, in some AI deployments, beyond 150 kW per rack. These elevated thermal loads require advanced thermal management solutions that can efficiently dissipate heat while ensuring continuous system reliability and performance.
"By type, the AHU integrated with chilled water systems segment is estimated to account for the largest, in terms of value, during the forecast period."
The AHU integrated with chilled water systems segment is projected to account for the largest market share due to increasing adoption of chilled water-based cooling in hyperscale, colocation, and enterprise data centers. Chilled water-based cooling provides high efficiency and high-scale cooling.
An ongoing trend is the proliferation of hyperscale data centers and AI-enabled computing infrastructure, which is also driving the use of chilled water systems with AHUs. Higher rack power densities across data centers are prompting operators to embrace a centralized chilled water-cooling architecture that can effectively remove heat from the entire facility. Furthermore, such systems can incorporate other emerging technologies such as variable-speed pumps, intelligent controls, free cooling schemes, and highly efficient chillers for enhanced efficiency.
"By data center type, the hyperscale data centers segment is projected to witness the highest CAGR during the forecast period."
Based on data center type, the hyperscale data centers segment is projected to register the fastest growth in the global data center air handling units market during the forecast period. Large cloud service providers and technology companies are rapidly deploying hyperscale data centers to cater to the soaring demand for digital workloads. As the utilization of AI/ML, HPC and cloud-based applications increases, there is a need for more sophisticated cooling infrastructures. AHUs, along with chilled water systems, free cooling, intelligent controls and variable-speed fans, are all being employed to control increased BTU loads with lower overall energy consumption. Hydrogen and methane-based nuclear cell-powered hyperscale operators are also offering an environmentally sustainable approach to data center development and operation via the deployment of highly energy-efficient HVAC components and systems to achieve 1.2PUE standards.
"By capacity, the >=50,000 M3/H segment is the highest growth during the forecast period."
In terms of capacity, the above >=50,000 m3/h segment is projected to grow at the highest CAGR in the overall data center air handling units market during the forecast period. The growth of this segment can be attributed to high demand for AHUs having airflow capacity of above 50,000 m 3/h due to the rapid growth of hyperscale data centers, large colocation facilities, and AI-focused computing infrastructure.
With increasing applications to AI/ML/HPC and cloud-based applications, the use of large-capacity air handling units (AHUs) is being further promoted. AHUs of this capacity increasingly feature chilled water cooling, free cooling, EC fans, variable air volume for cooling/heating, and intelligent monitoring systems.
"North America is projected to be the largest data center air handling units market, in terms of value, during the forecast period."
North America is estimated to be the largest market for data center air handling units during the forecast period. This growth is primarily driven by its established digital infrastructure, a significant presence of hyperscale cloud providers, and the rapid increase in artificial intelligence (AI) and high-performance computing (HPC) workloads. The US and Canada continue to experience significant investment in hyperscale, colocation, and enterprise data centers. Companies like Amazon Web Services (AWS), Microsoft, Google, Meta, Oracle, and CoreWeave are expanding their AI-ready infrastructures. As more high-density server racks and GPU clusters are implemented, thermal loads are increasing, which in turn raises the demand for enhanced thermal management solutions across the region.
Moreover, the region is at the forefront of developing next-generation cooling technologies. These include direct-to-chip liquid cooling, immersion cooling, precision air conditioning, computer room air handlers (CRAHs), computer room air conditioners (CRACs), coolant distribution units (CDUs), heat exchangers, and smart thermal monitoring systems. With these advanced tools, data center teams can improve cooling efficiency, maintain optimal temperatures, reduce energy consumption, and achieve better Power Usage Effectiveness (PUE) outcomes, all while managing the growing demands of power-hungry AI applications.
Profile break-up of primary participants for the report:
- By Company Type: Tier 1 - 45%, Tier 2 - 22%, and Tier 3 - 33%
- By Designation: C-Level Executives- 50%, Directors- 10%, and Others - 40%
- By Region: North America - 17%, Asia Pacific - 17%, Europe - 33%, Middle East & Africa - 25%, and South America - 8%
Leading players operating in the data center air handling units market include STULZ GMBH (Germany), Samsung Electronics (South Korea), Systemair AB (Sweden), Vertiv Group Corp (US), Swegon Group AB, (Sweden), Munters Group AB (Sweden), Johnson Controls (US), Trane (Ireland), Carrier (US), Daikin (Japan), Mitsubishi Electric Corporation (Japan), LG Electronics (South Korea), Trox SE (Germany), Airedale International Air Conditioning Ltd (Modine) (UK), AL-KO THERM GMBH (Germany), AAON (US), Zeco Aircon (India), GD Midea Heating & Ventilating Equipment Co., Ltd. (China), and others. These key players are significant contributors to the data center air handling units market. These players have adopted various strategies, including agreements, joint ventures, and expansions, to increase their market share and business revenue.
Research Coverage:
The report defines, segments, and projects the size of the data center air handling units market based on data center type, capacity, type, and region. It strategically profiles the key players and comprehensively analyzes their market shares and core competencies. It also tracks and analyzes competitive developments, such as expansions, partnerships, and acquisitions undertaken by them in the market.
Reasons to Buy the Report:
The report is expected to help market leaders/new entrants by providing them with the closest approximations of revenue numbers for the data center air handling units market and its segments. This report is also expected to help stakeholders gain a deeper understanding of the market's competitive landscape, acquire valuable insights to enhance their business positions, and develop effective go-to-market strategies. It also enables stakeholders to understand the market's pulse and provides information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following pointers:
- Analysis of drivers (Rapid expansion of data center market, Growing emphasis on energy efficient and sustainable data center cooling, Increasing server rack power density driving demand for advanced airflow management), restraints (Growing adoption of liquid cooling technologies for high density computing, High capital investment and lifecycle costs of advanced AHU systems), opportunities (Increasing adoption of hybrid cooling architectures in AI ready data centers, Growing retrofit and modernization of legacy data center cooling infrastructure), and challenges (Integration challenges in hybrid cooling architectures) influencing the growth of the data center air handling units market
- Product Development/Innovation: Detailed insights into upcoming technologies and research & development activities in the data center air handling units market
- Market Development: Comprehensive information about lucrative markets - the report analyzes the data center air handling units market across varied regions.
- Market Diversification: Exhaustive information about new products, various types, untapped geographies, recent developments, and investments in the data center air handling units market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and product offerings of leading players such as STULZ GMBH (Germany), Samsung Electronics (South Korea), Systemair AB (Sweden), Vertiv Group Corp (US), Swegon Group AB, (Sweden), Munters Group AB (Sweden), Johnson Controls (US), Trane (Ireland), Carrier (US), Daikin (Japan), Mitsubishi Electric Corporation (Japan), LG Electronics (South Korea), Trox SE (Germany), Airedale International Air Conditioning Ltd (Modine) (UK), AL-KO THERM GMBH (Germany), AAON (US), Zeco Aircon (India), GD Midea Heating & Ventilating Equipment Co., Ltd. (China), and others
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 LIMITATIONS
- 1.6 STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN DATA CENTER AHU MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN DATA CENTER AHU MARKET
- 3.2 DATA CENTER AHU MARKET, BY DATA CENTER TYPE
- 3.3 DATA CENTER AHU MARKET, BY AHU TYPE
- 3.4 DATA CENTER AHU MARKET, BY CAPACITY
- 3.5 DATA CENTER AHU MARKET, BY REGION
- 3.6 DATA CENTER AHU MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rapid expansion of data center market
- 4.2.1.2 Growing emphasis on energy-efficient and sustainable data center cooling
- 4.2.1.3 Increasing server rack power density driving demand for advanced airflow management
- 4.2.2 RESTRAINTS
- 4.2.2.1 Growing adoption of liquid cooling technologies for high-density computing
- 4.2.2.2 High capital investment and lifecycle costs of advanced AHU systems
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Increasing adoption of hybrid cooling architectures in AI-ready data centers
- 4.2.3.2 Growing retrofit and modernization of legacy data center cooling infrastructure
- 4.2.4 CHALLENGES
- 4.2.4.1 Integration challenges in hybrid cooling architectures
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN DATA CENTER AHU MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS SECTOR OPPORTUNITIES
- 4.5 EMERGING BUSINESS MODELS AND ECOSYSTEM SHIFTS
- 4.5.1 EMERGING BUSINESS MODELS
- 4.5.2 ECOSYSTEM SHIFTS
- 4.6 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
- 4.6.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 BARGAINING POWER OF SUPPLIERS
- 5.1.2 BARGAINING POWER OF BUYERS
- 5.1.3 THREAT OF SUBSTITUTES
- 5.1.4 THREAT OF NEW ENTRANTS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMICS INDICATORS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 DATA CENTER INDUSTRY
- 5.2.4 MANUFACTURING INDUSTRY
- 5.2.5 TRENDS IN GLOBAL HYPERSCALE AND AI DATA CENTER INDUSTRY
- 5.3 VALUE CHAIN ANALYSIS
- 5.3.1 PROMINENT COMPANIES
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 KEY CONFERENCES & EVENTS IN 2026-2027
- 5.6 TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- 5.7 INVESTMENT AND FUNDING SCENARIO
- 5.8 CASE STUDY ANALYSIS
- 5.8.1 CASE STUDY 1: JOHNSON CONTROLS (SILENT-AIRE) - MODULAR DATA CENTER AIR HANDLING UNIT SOLUTION
- 5.8.2 CASE STUDY 2: BESPOKE AIR HANDLING UNIT DEPLOYMENT FOR A HYPERSCALE DATA CENTER IN BELGIUM BY DAIKIN APPLIED UK
6 KEY EMERGING TECHNOLOGIES
- 6.1 KEY TECHNOLOGIES
- 6.1.1 INTELLIGENT AHU CONTROL AND MONITORING SYSTEMS
- 6.1.2 HIGH EFFICIENCY EC FAN AND VARIABLE AIRFLOW TECHNOLOGY
- 6.2 ADJACENT TECHNOLOGY ANALYSIS
- 6.2.1 MODULAR AND PREFABRICATED AHU SYSTEMS
- 6.2.2 WASTE HEAT RECOVERY AND REUSE SYSTEMS
- 6.3 COMPLEMENTARY TECHNOLOGY ANALYSIS
- 6.3.1 HYBRID AIR-LIQUID COOLING INTEGRATION SYSTEMS
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 SHORT TERM (2026 TO 2028) | FOUNDATION & EARLY COMMERCIALIZATION
- 6.4.2 MID TERM (2028 TO 2032) | EXPANSION & STANDARDIZATION
- 6.4.3 LONG TERM (2032 TO 2035+) | MASS COMMERCIALIZATION & AUTONOMOUS THERMAL MANAGEMENT
- 6.5 PATENT ANALYSIS
- 6.5.1 INTRODUCTION
- 6.5.2 METHODOLOGY
- 6.5.3 DOCUMENT TYPE
- 6.5.4 INSIGHTS
- 6.5.5 LEGAL STATUS OF PATENTS
- 6.5.6 JURISDICTION ANALYSIS
- 6.5.7 TOP APPLICANTS
- 6.5.7.1 List of major patents
- 6.6 FUTURE APPLICATIONS
- 6.6.1 INTELLIGENT AUTONOMOUS AHU CONTROL SYSTEMS: INTELLIGENT AHUS THAT CONTINUOUSLY OPTIMIZE AIRFLOW, TEMPERATURE, HUMIDITY, AND ENERGY CONSUMPTION THROUGH ADAPTIVE CONTROLS AND PREDICTIVE ANALYTICS
- 6.6.2 HYBRID COOLING COMPATIBLE AHUS: AHUS DESIGNED FOR SEAMLESS INTEGRATION WITH HYBRID COOLING ARCHITECTURES IN HIGH DENSITY DATA CENTER ENVIRONMENTS
- 6.6.3 MODULAR AND SCALABLE AHU PLATFORMS: FACTORY-ASSEMBLED MODULAR AHUS THAT ENABLE RAPID DEPLOYMENT, STANDARDIZED EXPANSION, AND SCALABLE COOLING INFRASTRUCTURE FOR HYPERSCALE AND EDGE DATA CENTERS
- 6.6.4 HEAT RECOVERY COMPATIBLE AHUS: AHUS ENGINEERED FOR COMPATIBILITY WITH FACILITY LEVEL HEAT RECOVERY SYSTEMS TO SUPPORT SUSTAINABLE DATA CENTER COOLING STRATEGIES
- 6.7 IMPACT OF AI/GEN AI ON DATA CENTER AHU MARKET
- 6.7.1 INTRODUCTION
- 6.7.2 TOP USE CASES AND MARKET POTENTIAL
- 6.7.3 BEST PRACTICES: COMPANIES/ INSTITUTIONS USE CASES
- 6.7.4 CASE STUDIES OF DATA CENTER AHU MARKET
- 6.7.5 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.7.6 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN DATA CENTER AHU MARKET
- 6.7.7 JOHNSON CONTROLS (SILENT-AIRE): CUSTOM AIR HANDLING FOR AI READY HYPERSCALE DATA CENTERS
- 6.7.8 DAIKIN: INTEGRATED AIR HANDLING FOR AI-READY DATA CENTERS
7 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 CARBON IMPACT AND ECO APPLICATIONS OF DATA CENTER AHU MARKET
- 7.3 SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, AND ECO STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION MAKING PROCESS
- 8.2 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS IN VARIOUS END-USE INDUSTRIES
- 8.5 MARKET PROFITABILITY
- 8.5.1 REVENUE POTENTIAL
- 8.5.2 COST DYNAMICS
- 8.5.3 MARGIN OPPORTUNITIES IN KEY APPLICATIONS
9 DATA CENTER AHU MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 CHILLED WATER (CHW) AHU
- 9.2.1 EXPANSION OF HYPERSCALE DATA CENTERS AND AI-READY INFRASTRUCTURE DRIVES DEMAND FOR CHILLED WATER AHUS
- 9.3 DX (DIRECT EXPANSION) AHU
- 9.3.1 GROWING DEMAND FOR EDGE AND MODULAR DATA CENTERS DRIVES ADOPTION OF DX AHUS
- 9.4 EVAPORATIVE/ADIABATIC AHU
- 9.4.1 INCREASING FOCUS ON ENERGY EFFICIENCY AND SUSTAINABILITY DRIVES ADOPTION OF EVAPORATIVE/ADIABATIC AHUS
- 9.5 OUTSIDE AIR/AIR SIDE ECONOMIZER AHU
- 9.5.1 INCREASING EMPHASIS ON ENERGY EFFICIENT COOLING DRIVES ADOPTION OF OUTSIDE AIR/AIR SIDE ECONOMIZER AHUS
- 9.6 HYBRID (DUAL MEDIUM NATIVE) AHU
- 9.6.1 INCREASING ADOPTION OF FLEXIBLE COOLING ARCHITECTURES DRIVES DEMAND FOR HYBRID AHUS
10 DATA CENTER AHU MARKET, BY CAPACITY
- 10.1 INTRODUCTION
- 10.2 <= 5,000 M3/H
- 10.2.1 GROWING DEPLOYMENT OF EDGE AND MODULAR DATA CENTERS SUPPORTS DEMAND FOR AHUS WITH CAPACITIES UP TO 5,000 M3/H
- 10.3 5,001-15,000 M3/H
- 10.3.1 GROWING EXPANSION OF ENTERPRISE AND REGIONAL COLOCATION DATA CENTERS SUPPORTS DEMAND FOR AHUS WITH CAPACITIES OF 5,001-15,000 M3/H
- 10.4 15,001-30,000 M3/H
- 10.4.1 INCREASING DEPLOYMENT OF MODULAR HYPERSCALE AND LARGE COLOCATION DATA CENTERS DRIVES DEMAND FOR AHUS WITH CAPACITIES OF 15,001-30,000 M3/H
- 10.5 30,001-50,000 M3/H
- 10.5.1 INCREASING RACK POWER DENSITIES DRIVE DEMAND FOR AHUS WITH CAPACITIES OF 30,001-50,000 M3/H
- 10.6 >= 50,001 M3/H
- 10.6.1 EXPANSION OF AI MEGA CAMPUSES DRIVES DEMAND FOR AHUS WITH CAPACITIES OF >= 50,001 M3/H
11 DATA CENTER AHU MARKET, BY DATA CENTER TYPE
- 11.1 INTRODUCTION
- 11.2 HYPERSCALE
- 11.2.1 EXPANSION OF AI INFRASTRUCTURE AND HYPERSCALE DATA CENTERS DRIVES DEMAND FOR HIGH-CAPACITY AIR HANDLING UNITS
- 11.3 COLOCATION PROVIDERS
- 11.3.1 GROWING DEMAND FOR AI-READY INFRASTRUCTURE DRIVES AHU ADOPTION IN COLOCATION DATA CENTERS
- 11.4 ENTERPRISES
- 11.4.1 MODERNIZATION OF LEGACY DATA CENTER INFRASTRUCTURE SUPPORTS AHU ADOPTION IN ENTERPRISE DATA CENTERS
12 DATA CENTER AIR HANDLING UNITS MARKET, BY REGION
- 12.1 INTRODUCTION
- 12.2 NORTH AMERICA
- 12.2.1 US
- 12.2.1.1 Hyperscale expansion, liquid cooling integration, and AI-driven infrastructure investment to sustain market leadership
- 12.2.2 CANADA
- 12.2.2.1 Cold-climate free cooling and renewable power pricing to anchor sustainable AHU demand
- 12.2.3 MEXICO
- 12.2.3.1 Nearshoring-led digital investment and hyperscale market entry to drive demand for heat-tolerant AHU systems
- 12.2.1 US
- 12.3 EUROPE
- 12.3.1 GERMANY
- 12.3.1.1 EnEfG efficiency mandates and record hyperscale capital deployment to reshape Frankfurt's air handling standards
- 12.3.2 UK
- 12.3.2.1 AI growth zones and critical national infrastructure status to unlock a new wave of AHU-equipped capacity
- 12.3.3 FRANCE
- 12.3.3.1 Nuclear-backed low-carbon power and sovereign cloud investment to fuel hyperscale AHU demand
- 12.3.4 ITALY
- 12.3.4.1 Milan's rise to tier-one status and Mediterranean connectivity to drive new AHU-equipped campus construction
- 12.3.5 SPAIN
- 12.3.5.1 Solar-rich power availability and fast-tracked mega-campuses to position Spain as a leading growth market
- 12.3.6 RUSSIA
- 12.3.6.1 Import substitution and data localization mandates to sustain a domestically oriented AHU market
- 12.3.7 REST OF EUROPE
- 12.3.1 GERMANY
- 12.4 ASIA PACIFIC
- 12.4.1 CHINA
- 12.4.1.1 East-west data computing program and sovereign AI buildout to anchor the region's largest AHU market
- 12.4.2 JAPAN
- 12.4.2.1 Sovereign AI investment and severe power constraints to elevate demand for high-efficiency, space-optimized AHU systems
- 12.4.3 INDIA
- 12.4.3.1 Infrastructure-status incentives and record hyperscaler commitments to drive Asia's fastest-growing AHU demand
- 12.4.4 SOUTH KOREA
- 12.4.4.1 18.4 GW national AI data center megaproject to reshape long-term demand for high-density AHU infrastructure
- 12.4.5 THAILAND
- 12.4.5.1 BOI incentives and regional diversification beyond Singapore to accelerate new AHU-equipped capacity
- 12.4.6 TAIWAN
- 12.4.6.1 Semiconductor leadership and AI chipmaker R&D investment to drive precision, high-density AHU requirements
- 12.4.7 AUSTRALIA
- 12.4.7.1 Record capital inflows and OpenAI-NEXTDC partnership to underpin strong AHU demand through 2030
- 12.4.8 REST OF ASIA PACIFIC
- 12.4.1 CHINA
- 12.5 MIDDLE EAST & AFRICA
- 12.5.1 GCC COUNTRIES
- 12.5.1.1 Saudi Arabia
- 12.5.1.1.1 HUMAIN's multi-gigawatt sovereign AI buildout to drive the region's most aggressive AHU demand growth
- 12.5.1.2 UAE
- 12.5.1.2.1 Stargate UAE and G42's international partnerships to cement the country's position as a regional AI hub
- 12.5.1.3 Qatar
- 12.5.1.3.1 Brookfield-QAI partnership and national digital transformation strategy to expand Doha's AHU-equipped capacity
- 12.5.1.4 Rest of GCC Countries
- 12.5.1.1 Saudi Arabia
- 12.5.2 SOUTH AFRICA
- 12.5.2.1 Sub-Saharan Africa's leading connectivity hub status to drive steady, grid-resilient AHU investment
- 12.5.3 TURKEY
- 12.5.3.1 Istanbul's Europe-Asia connectivity bridge and Google's regional investment to support steady AHU growth
- 12.5.4 REST OF MIDDLE EAST & AFRICA
- 12.5.1 GCC COUNTRIES
- 12.6 SOUTH AMERICA
- 12.6.1 BRAZIL
- 12.6.1.1 ByteDance's record USD 39 billion campus and hyperscale cloud expansion to anchor South America's largest AHU market
- 12.6.2 ARGENTINA
- 12.6.2.1 Digital banking growth and government modernization programs to sustain incremental AHU demand despite macro headwinds
- 12.6.3 REST OF SOUTH AMERICA
- 12.6.1 BRAZIL
13 COMPETITIVE LANDSCAPE
- 13.1 INTRODUCTION
- 13.2 KEY PLAYERS' STRATEGIES/RIGHT TO WIN
- 13.3 REVENUE ANALYSIS, 2025
- 13.3.1 TOP PLAYERS' REVENUE ANALYSIS
- 13.4 MARKET SHARE ANALYSIS, 2025
- 13.4.1 RANKING ANALYSIS OF KEY MARKET PLAYERS
- 13.4.2 MARKET SHARE ANALYSIS, 2025
- 13.5 BRAND/PRODUCT COMPARISON
- 13.6 COMPANY VALUATION AND FINANCIAL METRICS
- 13.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 13.7.1 STARS
- 13.7.2 EMERGING LEADERS
- 13.7.3 PERVASIVE PLAYERS
- 13.7.4 PARTICIPANTS
- 13.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 13.7.5.1 Company footprint
- 13.7.6 REGION FOOTPRINT
- 13.7.7 TYPE FOOTPRINT
- 13.7.8 CAPACITY FOOTPRINT
- 13.7.9 DATA CENTER TYPE FOOTPRINT
- 13.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 13.8.1 PROGRESSIVE COMPANIES
- 13.8.2 RESPONSIVE COMPANIES
- 13.8.3 DYNAMIC COMPANIES
- 13.8.4 STARTING BLOCKS
- 13.8.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 13.8.5.1 Detailed list of key startups/SMEs
- 13.8.5.2 Competitive benchmarking of key startups/SMEs
- 13.9 COMPETITIVE SCENARIO
- 13.9.1 PRODUCT LAUNCHES
- 13.9.2 DEALS
14 COMPANY PROFILES
- 14.1 MAJOR PLAYERS
- 14.1.1 VERTIV GROUP CORP.
- 14.1.1.1 Business overview
- 14.1.1.2 Products/Solutions/Services offered
- 14.1.1.3 Recent developments
- 14.1.1.3.1 Product Launches
- 14.1.1.4 MnM view
- 14.1.1.4.1 Key strengths
- 14.1.1.4.2 Strategic choices
- 14.1.1.4.3 Weaknesses and competitive threats
- 14.1.2 STULZ GMBH
- 14.1.2.1 Business overview
- 14.1.2.2 Products/Solutions/Services offered
- 14.1.2.3 MnM view
- 14.1.2.3.1 Key strengths
- 14.1.2.3.2 Strategic choices
- 14.1.2.3.3 Weaknesses and competitive threats
- 14.1.3 SAMSUNG ELECTRONICS CO., LTD. (FLAKTGROUP)
- 14.1.3.1 Business overview
- 14.1.3.2 Products/Solutions/Services offered
- 14.1.3.3 Recent developments
- 14.1.3.4 MnM view
- 14.1.3.4.1 Key strengths
- 14.1.3.4.2 Strategic choices
- 14.1.3.4.3 Weaknesses and competitive threats
- 14.1.4 SYSTEMAIR AB
- 14.1.4.1 Business overview
- 14.1.4.2 Products/Solutions/Services offered
- 14.1.4.3 Recent developments
- 14.1.4.3.1 Product Launches
- 14.1.4.4 MnM view
- 14.1.4.4.1 Key strengths
- 14.1.4.4.2 Strategic choices
- 14.1.4.4.3 Weaknesses and competitive threats
- 14.1.5 SWEGON GROUP AB
- 14.1.5.1 Business overview
- 14.1.5.2 Products/Solutions/Services offered
- 14.1.5.3 Recent developments
- 14.1.5.4 MnM view
- 14.1.5.4.1 Key strengths
- 14.1.5.4.2 Strategic choices
- 14.1.5.4.3 Weaknesses and competitive threats
- 14.1.6 MUNTERS GROUP AB
- 14.1.6.1 Business overview
- 14.1.6.2 Products/Solutions/Services offered
- 14.1.7 JOHNSON CONTROLS
- 14.1.7.1 Business overview
- 14.1.7.2 Products/Solutions/Services offered
- 14.1.8 TRANE
- 14.1.8.1 Business overview
- 14.1.8.2 Products/Solutions/Services offered
- 14.1.9 CARRIER
- 14.1.9.1 Business overview
- 14.1.9.2 Products/Solutions/Services offered
- 14.1.10 DAIKIN INDUSTRIES LTD.
- 14.1.10.1 Business overview
- 14.1.10.2 Products/Solutions/Services offered
- 14.1.10.3 Recent developments
- 14.1.10.3.1 Deals
- 14.1.11 MITSUBISHI ELECTRIC CORPORATION
- 14.1.11.1 Business overview
- 14.1.11.2 Products/Solutions/Services offered
- 14.1.11.3 Recent developments
- 14.1.11.3.1 Deals
- 14.1.11.3.2 Expansions
- 14.1.12 LG ELECTRONICS
- 14.1.12.1 Business overview
- 14.1.12.2 Products/Solutions/Services offered
- 14.1.13 TROX SE
- 14.1.13.1 Business overview
- 14.1.13.2 Products/Solutions/Services offered
- 14.1.14 AIREDALE INTERNATIONAL AIR CONDITIONING LTD.
- 14.1.14.1 Business overview
- 14.1.14.2 Products/Solutions/Services offered
- 14.1.14.3 Recent developments
- 14.1.14.3.1 Product Launches
- 14.1.14.3.2 Deals
- 14.1.15 AL-KO THERM GMBH
- 14.1.15.1 Business overview
- 14.1.15.2 Products/Solutions/Services offered
- 14.1.16 AAON
- 14.1.16.1 Business overview
- 14.1.16.2 Products/Solutions/Services offered
- 14.1.17 GD MIDEA HEATING & VENTILATING EQUIPMENT CO., LTD.
- 14.1.17.1 Business overview
- 14.1.17.2 Products/Solutions/Services offered
- 14.1.18 ZECO AIRCON
- 14.1.18.1 Business overview
- 14.1.18.2 Products/Solutions/Services offered
- 14.1.1 VERTIV GROUP CORP.
- 14.2 OTHER PLAYERS
- 14.2.1 ROSENBERG VENTILATOREN GMBH
- 14.2.2 MENERGA GMBH
- 14.2.3 CHAT UNION CLIMAVENETA
- 14.2.4 NORTEK AIR SOLUTIONS, LLC
- 14.2.5 HAAKON INDUSTRIES
- 14.2.6 MAMMOTH INC.
- 14.2.7 ENTROPIC
15 RESEARCH METHODOLOGY
- 15.1 RESEARCH DATA
- 15.1.1 SECONDARY DATA
- 15.1.1.1 List of key secondary sources
- 15.1.1.2 Key data from secondary sources
- 15.1.2 PRIMARY DATA
- 15.1.2.1 Key data from primary sources
- 15.1.2.2 Key industry insights
- 15.1.2.3 List of primary participants
- 15.1.2.4 Breakdown of primary interviews
- 15.1.1 SECONDARY DATA
- 15.2 MARKET SIZE ESTIMATION
- 15.2.1 BOTTOM-UP APPROACH
- 15.2.2 TOP-DOWN APPROACH
- 15.3 MARKET FORECAST APPROACH
- 15.3.1 DEMAND-SIDE ANALYSIS
- 15.3.2 SUPPLY-SIDE ANALYSIS
- 15.3.3 CALCULATIONS FOR SUPPLY-SIDE ANALYSIS
- 15.4 GROWTH FORECAST
- 15.5 DATA TRIANGULATION
- 15.6 RESEARCH ASSUMPTIONS
- 15.7 RESEARCH LIMITATIONS
- 15.8 RISK ASSESSMENT
- 15.9 FACTOR ANALYSIS
16 APPENDIX
- 16.1 DISCUSSION GUIDE
- 16.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 16.3 CUSTOMIZATION OPTIONS
- 16.4 RELATED REPORTS
- 16.5 AUTHOR DETAILS
List of Tables
- TABLE 1 DATA CENTER AIR HANDLING UNITS MARKET: INCLUSIONS AND EXCLUSIONS
- TABLE 2 DATA CENTER AHU MARKET: PORTER'S FIVE FORCES ANALYSIS
- TABLE 3 GDP PERCENTAGE CHANGE, BY KEY COUNTRIES, 2021-2029
- TABLE 4 DATA CENTER AHU MARKET: ECOSYSTEM ANALYSIS
- TABLE 5 DATA CENTER AHU MARKET: DETAILED LIST OF CONFERENCES & EVENTS
- TABLE 6 DATA CENTER AHU MARKET: TOTAL NUMBER OF PATENTS, 2015-2025
- TABLE 7 PATENTS RELATED TO DATA CENTER AHUS
- TABLE 8 TOP USE CASES AND MARKET POTENTIAL
- TABLE 9 BEST PRACTICES: COMPANIES IMPLEMENTING USE CASES
- TABLE 10 DATA CENTER AHU MARKET: CASE STUDIES RELATED TO GEN AI IMPLEMENTATION
- TABLE 11 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- TABLE 12 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 13 EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 14 ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 15 ROW: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 16 STANDARDS FOR DATA CENTER AHU
- TABLE 17 CERTIFICATIONS, LABELING, AND ECO STANDARDS IN DATA CENTER AHU MARKET
- TABLE 18 INFLUENCE OF STAKEHOLDERS IN BUYING PROCESS FOR TOP END-USE INDUSTRIES (%)
- TABLE 19 KEY BUYING CRITERIA BY END USER
- TABLE 20 DATA CENTER AHU MARKET: UNMET NEEDS IN KEY END-USE INDUSTRIES
- TABLE 21 DATA CENTER AHU MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 22 DATA CENTER AHU MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 23 CHILLED WATER (CHW) AHU MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 24 CHILLED WATER (CHW) AHU MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 25 DX (DIRECT EXPANSION) AHU MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 26 DX (DIRECT EXPANSION) AHU MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 27 EVAPORATIVE/ADIABATIC AHU MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 28 EVAPORATIVE/ADIABATIC AHU MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 29 OUTSIDE AIR/AIR SIDE ECONOMIZER AHU MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 30 OUTSIDE AIR/AIR SIDE ECONOMIZER AHU MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 31 HYBRID (DUAL MEDIUM NATIVE) AIR HANDLING UNITS, BY REGION, 2022-2025 (USD MILLION)
- TABLE 32 HYBRID (DUAL MEDIUM NATIVE) AIR HANDLING UNITS, BY REGION, 2026-2032 (USD MILLION)
- TABLE 33 DATA CENTER AHU MARKET, BY CAPACITY, 2022-2025 (USD MILLION)
- TABLE 34 DATA CENTER AHU MARKET, BY CAPACITY, 2026-2032 (USD MILLION)
- TABLE 35 <= 5,000 M3/H: DATA CENTER AHU MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 36 <= 5,000 M3/H: DATA CENTER AHU MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 37 5,001-15,000 M3/H: DATA CENTER AHU MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 38 5,001-15,000 M3/H: DATA CENTER AHU MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 39 15,001-30,000 M3/H: DATA CENTER AHU MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 40 15,001-30,000 M3/H: DATA CENTER AHU MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 41 30,001-50,000 M3/H: DATA CENTER AHU MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 42 30,001-50,000 M3/H: DATA CENTER AHU MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 43 >= 50,001 M3/H: DATA CENTER AHU MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 44 >= 50,001 M3/H: DATA CENTER AHU MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 45 DATA CENTER AHU MARKET, BY DATA CENTER TYPE, 2022-2025 (USD MILLION)
- TABLE 46 DATA CENTER AHU MARKET, BY DATA CENTER TYPE, 2026-2032 (USD MILLION)
- TABLE 47 HYPERSCALE: DATA CENTER AHU MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 48 HYPERSCALE: DATA CENTER AHU MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 49 COLOCATION PROVIDERS: DATA CENTER AHU MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 50 COLOCATION PROVIDERS: DATA CENTER AHU MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 51 ENTERPRISES: DATA CENTER AHU MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 52 ENTERPRISES: DATA CENTER AHU MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 53 DATA CENTER AIR HANDLING UNITS MARKET, BY REGION, 2022-2025 (USD MILLION)
- TABLE 54 DATA CENTER AIR HANDLING UNITS MARKET, BY REGION, 2026-2032 (USD MILLION)
- TABLE 55 NORTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 56 NORTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 57 NORTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 58 NORTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 59 NORTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET, BY DATA CENTER TYPE, 2022-2025 (USD MILLION)
- TABLE 60 NORTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET, BY DATA CENTER TYPE, 2026-2032 (USD MILLION)
- TABLE 61 NORTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET, BY CAPACITY, 2022-2025 (USD MILLION)
- TABLE 62 NORTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET, BY CAPACITY, 2026-2032 (USD MILLION)
- TABLE 63 US: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 64 US: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 65 CANADA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 66 CANADA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 67 MEXICO: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 68 MEXICO: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 69 EUROPE: DATA CENTER AIR HANDLING UNITS MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 70 EUROPE: DATA CENTER AIR HANDLING UNITS MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 71 EUROPE: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 72 EUROPE: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 73 EUROPE: DATA CENTER AIR HANDLING UNITS MARKET, BY DATA CENTER TYPE, 2022-2025 (USD MILLION)
- TABLE 74 EUROPE: DATA CENTER AIR HANDLING UNITS MARKET, BY DATA CENTER TYPE, 2026-2032 (USD MILLION)
- TABLE 75 EUROPE: DATA CENTER AIR HANDLING UNITS MARKET, BY CAPACITY, 2022-2025 (USD MILLION)
- TABLE 76 EUROPE: DATA CENTER AIR HANDLING UNITS MARKET, BY CAPACITY, 2026-2032 (USD MILLION)
- TABLE 77 GERMANY: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 78 GERMANY: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 79 UK: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 80 UK: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 81 FRANCE: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 82 FRANCE: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 83 ITALY: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 84 ITALY: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 85 SPAIN: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 86 SPAIN: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 87 RUSSIA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 88 RUSSIA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 89 REST OF EUROPE: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 90 REST OF EUROPE: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 91 ASIA PACIFIC: DATA CENTER AIR HANDLING UNITS MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 92 ASIA PACIFIC: DATA CENTER AIR HANDLING UNITS MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 93 ASIA PACIFIC: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 94 ASIA PACIFIC: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 95 ASIA PACIFIC: DATA CENTER AIR HANDLING UNITS MARKET, BY DATA CENTER TYPE, 2022-2025 (USD MILLION)
- TABLE 96 ASIA PACIFIC: DATA CENTER AIR HANDLING UNITS MARKET, BY DATA CENTER TYPE, 2026-2032 (USD MILLION)
- TABLE 97 ASIA PACIFIC: DATA CENTER AIR HANDLING UNITS MARKET, BY CAPACITY, 2022-2025 (USD MILLION)
- TABLE 98 ASIA PACIFIC: DATA CENTER AIR HANDLING UNITS MARKET, BY CAPACITY, 2026-2032 (USD MILLION)
- TABLE 99 CHINA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 100 CHINA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 101 JAPAN: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 102 JAPAN: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 103 INDIA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 104 INDIA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 105 SOUTH KOREA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 106 SOUTH KOREA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 107 THAILAND: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 108 THAILAND: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 109 TAIWAN: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 110 TAIWAN: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 111 AUSTRALIA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 112 AUSTRALIA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 113 REST OF ASIA PACIFIC: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 114 REST OF ASIA PACIFIC: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 115 MIDDLE EAST & AFRICA: DATA CENTER AIR HANDLING UNITS MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 116 MIDDLE EAST & AFRICA: DATA CENTER AIR HANDLING UNITS MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 117 MIDDLE EAST & AFRICA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 118 MIDDLE EAST & AFRICA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 119 MIDDLE EAST & AFRICA: DATA CENTER AIR HANDLING UNITS MARKET, BY DATA CENTER TYPE, 2022-2025 (USD MILLION)
- TABLE 120 MIDDLE EAST & AFRICA: DATA CENTER AIR HANDLING UNITS MARKET, BY DATA CENTER TYPE, 2026-2032 (USD MILLION)
- TABLE 121 MIDDLE EAST & AFRICA: DATA CENTER AIR HANDLING UNITS MARKET, BY CAPACITY, 2022-2025 (USD MILLION)
- TABLE 122 MIDDLE EAST & AFRICA: DATA CENTER AIR HANDLING UNITS MARKET, BY CAPACITY, 2026-2032 (USD MILLION)
- TABLE 123 SAUDI ARABIA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 124 SAUDI ARABIA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 125 UAE: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 126 UAE: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 127 QATAR: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 128 QATAR: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 129 REST OF GCC COUNTRIES: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 130 REST OF GCC COUNTRIES: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 131 SOUTH AFRICA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 132 SOUTH AFRICA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 133 TURKEY: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 134 TURKEY: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 135 REST OF MIDDLE EAST & AFRICA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 136 REST OF MIDDLE EAST & AFRICA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 137 SOUTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET, BY COUNTRY, 2022-2025 (USD MILLION)
- TABLE 138 SOUTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET, BY COUNTRY, 2026-2032 (USD MILLION)
- TABLE 139 SOUTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 140 SOUTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 141 SOUTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET, BY DATA CENTER TYPE, 2022-2025 (USD MILLION)
- TABLE 142 SOUTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET, BY DATA CENTER TYPE, 2026-2032 (USD MILLION)
- TABLE 143 SOUTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET, BY CAPACITY, 2022-2025 (USD MILLION)
- TABLE 144 SOUTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET, BY CAPACITY, 2026-2032 (USD MILLION)
- TABLE 145 BRAZIL: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 146 BRAZIL: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 147 ARGENTINA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 148 ARGENTINA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 149 REST OF SOUTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2022-2025 (USD MILLION)
- TABLE 150 REST OF SOUTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET, BY TYPE, 2026-2032 (USD MILLION)
- TABLE 151 DATA CENTER AIR HANDLING UNITS MARKET: OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS, 2021-2026
- TABLE 152 DATA CENTER AIR HANDLING UNITS MARKET: DEGREE OF COMPETITION, 2025
- TABLE 153 DATA CENTER AIR HANDLING UNITS MARKET: REGION FOOTPRINT
- TABLE 154 DATA CENTER AIR HANDLING UNITS MARKET: TYPE FOOTPRINT
- TABLE 155 DATA CENTER AIR HANDLING UNITS MARKET: CAPACITY FOOTPRINT
- TABLE 156 DATA CENTER AIR HANDLING UNITS MARKET: DATA CENTER TYPE FOOTPRINT
- TABLE 157 DATA CENTER AIR HANDLING UNITS MARKET: DETAILED LIST OF KEY STARTUPS/SMES
- TABLE 158 DATA CENTER AIR HANDLING UNITS MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES (1/2)
- TABLE 159 DATA CENTER AIR HANDLING UNITS MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES (2/2)
- TABLE 160 DATA CENTER AIR HANDLING UNITS MARKET: PRODUCT LAUNCHES, JANUARY 2021-JULY 2026
- TABLE 161 DATA CENTER AIR HANDLING UNITS MARKET: DEALS, JANUARY 2021-JULY 2026
- TABLE 162 VERTIV GROUP CORP.: COMPANY OVERVIEW
- TABLE 163 VERTIV GROUP CORP.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 164 VERTIV GROUP CORP.: PRODUCT LAUNCHES
- TABLE 165 STULZ GMBH: COMPANY OVERVIEW
- TABLE 166 STULZ GMBH: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 167 SAMSUNG ELECTRONICS CO., LTD. (FLAKTGROUP): COMPANY OVERVIEW
- TABLE 168 SAMSUNG ELECTRONICS CO., LTD. (FLAKTGROUP): PRODUCTS/SOLUTIONS/ SERVICES OFFERED
- TABLE 169 SAMSUNG ELECTRONICS CO., LTD. (FLAKTGROUP): DEALS
- TABLE 170 SYSTEMAIR AB: COMPANY OVERVIEW
- TABLE 171 SYSTEMAIR AB: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 172 SYSTEMAIR AB: PRODUCT LAUNCHES
- TABLE 173 SWEGON GROUP AB: COMPANY OVERVIEW
- TABLE 174 SWEGON GROUP AB: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 175 SWEGON GROUP AB: DEALS
- TABLE 176 MUNTERS GROUP AB: COMPANY OVERVIEW
- TABLE 177 MUNTERS GROUP AB: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 178 JOHNSON CONTROLS: COMPANY OVERVIEW
- TABLE 179 JOHNSON CONTROLS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 180 TRANE: COMPANY OVERVIEW
- TABLE 181 TRANE: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 182 CARRIER: COMPANY OVERVIEW
- TABLE 183 CARRIER: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 184 DAIKIN INDUSTRIES LTD.: COMPANY OVERVIEW
- TABLE 185 DAIKIN INDUSTRIES LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 186 DAIKIN INDUSTRIES LTD.: DEALS
- TABLE 187 MITSUBISHI ELECTRIC CORPORATION: COMPANY OVERVIEW
- TABLE 188 MITSUBISHI ELECTRIC CORPORATION: PRODUCTS/SOLUTIONS/ SERVICES OFFERED
- TABLE 189 MITSUBISHI ELECTRIC CORPORATION: DEALS
- TABLE 190 MITSUBISHI ELECTRIC CORPORATION: EXPANSIONS
- TABLE 191 LG ELECTRONICS: COMPANY OVERVIEW
- TABLE 192 LG ELECTRONICS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 193 TROX SE: COMPANY OVERVIEW
- TABLE 194 TROX SE: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 195 AIREDALE INTERNATIONAL AIR CONDITIONING LTD.: COMPANY OVERVIEW
- TABLE 196 AIREDALE INTERNATIONAL AIR CONDITIONING LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 197 AIREDALE INTERNATIONAL AIR CONDITIONING LTD.: PRODUCT LAUNCHES
- TABLE 198 AIREDALE INTERNATIONAL AIR CONDITIONING LTD.: DEALS
- TABLE 199 AL-KO THERM GMBH: COMPANY OVERVIEW
- TABLE 200 AL-KO THERM GMBH: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 201 AAON: COMPANY OVERVIEW
- TABLE 202 AAON: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 203 GD MIDEA HEATING & VENTILATING EQUIPMENT CO., LTD.: COMPANY OVERVIEW
- TABLE 204 GD MIDEA HEATING & VENTILATING EQUIPMENT CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 205 ZECO AIRCON: COMPANY OVERVIEW
- TABLE 206 ZECO AIRCON: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 207 ROSENBERG VENTILATOREN GMBH: COMPANY OVERVIEW
- TABLE 208 MENERGA GMBH: COMPANY OVERVIEW
- TABLE 209 CHAT UNION CLIMAVENETA: COMPANY OVERVIEW
- TABLE 210 NORTEK AIR SOLUTIONS, LLC: COMPANY OVERVIEW
- TABLE 211 HAAKON INDUSTRIES: COMPANY OVERVIEW
- TABLE 212 MAMMOTH INC.: COMPANY OVERVIEW
- TABLE 213 ENTROPIC: COMPANY OVERVIEW
List of Figures
- FIGURE 1 DATA CENTER AIR HANDLING UNITS MARKET SEGMENTATION AND REGIONAL SCOPE
- FIGURE 2 KEY INSIGHTS AND MARKET HIGHLIGHTS
- FIGURE 3 GLOBAL DATA CENTER AHU MARKET, 2026-2032
- FIGURE 4 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN DATA CENTER AHU MARKET (2020-2025)
- FIGURE 5 DISRUPTIVE TRENDS IMPACTING GROWTH OF DATA CENTER AHU MARKET
- FIGURE 6 HIGH-GROWTH SEGMENTS IN DATA CENTER AHU MARKET
- FIGURE 7 NORTH AMERICA TO EXHIBIT FASTEST GROWTH DURING FORECAST PERIOD
- FIGURE 8 EXPANSION OF AI-READY DATA CENTERS AND HIGH-DENSITY COMPUTING TO CREATE LUCRATIVE OPPORTUNITIES FOR AHU MANUFACTURERS
- FIGURE 9 HYPERSCALE DATA CENTERS TO BE LARGEST SEGMENT DURING FORECAST PERIOD
- FIGURE 10 CHILLED WATER (CHW) AHU TO SECURE LEADING POSITION DURING FORECAST PERIOD
- FIGURE 11 30,001-50,000 M3/H TO BE LARGEST MARKET BY CAPACITY DURING FORECAST PERIOD
- FIGURE 12 NORTH AMERICA TO DOMINATE GLOBAL DATA CENTER AHU MARKET
- FIGURE 13 US TO BE FASTEST-GROWING MARKET DURING FORECAST PERIOD
- FIGURE 14 DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES IN DATA CENTER AHU MARKET
- FIGURE 15 NUMBER OF DATA CENTERS WORLDWIDE FOR TOP 10 COUNTRIES, 2026
- FIGURE 16 GLOBAL DATA CENTER POWER USAGE EFFECTIVENESS (PUE)
- FIGURE 17 PORTER'S FIVE FORCES ANALYSIS: DATA CENTER AHU MARKET
- FIGURE 18 GROWTH IN AI MARKET 2023 VS. 2033 (USD BILLION)
- FIGURE 19 VALUE CHAIN ANALYSIS: DATA CENTER AHU MARKET
- FIGURE 20 DATA CENTER AHU MARKET: ECOSYSTEM ANALYSIS
- FIGURE 21 DATA CENTER AHU MARKET: ECOSYSTEM ANALYSIS
- FIGURE 22 TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- FIGURE 23 DATA CENTER AHU MARKET: INVESTMENT AND FUNDING SCENARIO, 2026 (USD MILLION)
- FIGURE 24 PATENT ANALYSIS, BY DOCUMENT TYPE, 2015 - 2025
- FIGURE 25 PATENT PUBLICATION TRENDS, 2015 - 2025
- FIGURE 26 LEGAL STATUS OF PATENTS, JANUARY 2015 - DECEMBER 2025
- FIGURE 27 JURISDICTION OF US REGISTERED HIGHEST SHARE OF PATENTS, 2015-2025
- FIGURE 28 TOP PATENT APPLICANTS, 2015-2025
- FIGURE 29 FUTURE APPLICATIONS OF DATA CENTER AHU MARKET
- FIGURE 30 SUCCESS STORIES AND REAL WORLD APPLICATIONS
- FIGURE 31 DATA CENTER AHU MARKET: DECISION MAKING FACTORS
- FIGURE 32 INFLUENCE OF STAKEHOLDERS IN BUYING PROCESS, BY END USER
- FIGURE 33 KEY BUYING CRITERIA FOR TOP THREE END-USE INDUSTRIES
- FIGURE 34 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- FIGURE 35 CHILLED WATER (CHW) AHU TO ACCOUNT FOR LARGER SHARE DURING FORECAST PERIOD
- FIGURE 36 30,001-50,000 M3/H TO BE LARGEST CAPACITY TYPE FOR DATA CENTER AHU MARKET DURING FORECAST PERIOD
- FIGURE 37 HYPERSCALE DATA CENTERS TO BE LARGEST AND FASTEST-GROWING DATA CENTER TYPE DURING FORECAST PERIOD
- FIGURE 38 NORTH AMERICA TO ACCOUNT FOR THE LARGEST MARKET SHARE IN 2032
- FIGURE 39 NORTH AMERICA: DATA CENTER AIR HANDLING UNITS MARKET SNAPSHOT
- FIGURE 40 EUROPE: DATA CENTER AIR HANDLING UNITS MARKET SNAPSHOT
- FIGURE 41 ASIA PACIFIC: DATA CENTER AIR HANDLING UNITS MARKET SNAPSHOT
- FIGURE 42 DATA CENTER AIR HANDLING UNITS MARKET: REVENUE ANALYSIS OF KEY COMPANIES, 2021-2025
- FIGURE 43 DATA CENTER AIR HANDLING UNITS MARKET: RANKING OF TOP FIVE PLAYERS, 2025
- FIGURE 44 DATA CENTER AIR HANDLING UNITS MARKET SHARE ANALYSIS, 2025
- FIGURE 45 DATA CENTER AIR HANDLING UNITS MARKET: BRAND/PRODUCT COMPARISON
- FIGURE 46 DATA CENTER AIR HANDLING UNITS MARKET: EV/EBITDA
- FIGURE 47 DATA CENTER AIR HANDLING UNITS MARKET: EV/REVENUE
- FIGURE 48 DATA CENTER AIR HANDLING UNITS MARKET: YEAR-TO-DATE (YTD) PRICE TOTAL RETURN AND FIVE-YEAR STOCK BETA OF KEY MANUFACTURERS
- FIGURE 49 DATA CENTER AIR HANDLING UNITS MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 50 DATA CENTER AIR HANDLING UNITS MARKET: COMPANY FOOTPRINT
- FIGURE 51 DATA CENTER AIR HANDLING UNITS MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 52 VERTIV GROUP CORP.: COMPANY SNAPSHOT
- FIGURE 53 SAMSUNG ELECTRONICS CO., LTD. (FLAKTGROUP): COMPANY SNAPSHOT
- FIGURE 54 SYSTEMAIR AB: COMPANY SNAPSHOT
- FIGURE 55 MUNTERS GROUP AB: COMPANY SNAPSHOT
- FIGURE 56 JOHNSON CONTROLS: COMPANY SNAPSHOT
- FIGURE 57 TRANE: COMPANY SNAPSHOT
- FIGURE 58 CARRIER: COMPANY SNAPSHOT
- FIGURE 59 DAIKIN INDUSTRIES LTD.: COMPANY SNAPSHOT
- FIGURE 60 MITSUBISHI ELECTRIC CORPORATION: COMPANY SNAPSHOT
- FIGURE 61 LG ELECTRONICS: COMPANY SNAPSHOT
- FIGURE 62 AAON: COMPANY SNAPSHOT
- FIGURE 63 GD MIDEA HEATING & VENTILATING EQUIPMENT CO., LTD.: COMPANY SNAPSHOT
- FIGURE 64 DATA CENTER AIR HANDLING UNITS MARKET: RESEARCH DESIGN
- FIGURE 65 MARKET SIZE ESTIMATION METHODOLOGY: BOTTOM-UP APPROACH
- FIGURE 66 MARKET SIZE ESTIMATION METHODOLOGY: TOP-DOWN APPROACH
- FIGURE 67 MAIN MATRIX CONSIDERED TO ASSESS DEMAND FOR DATA CENTER AIR HANDLING UNITS
- FIGURE 68 STEPS CONSIDERED TO ANALYZE SUPPLY OF DATA CENTER AIR HANDLING UNITS
- FIGURE 69 DATA CENTER AIR HANDLING UNITS MARKET: DATA TRIANGULATION

