PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125449

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125449
Air Handling Units (AHU) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the air handling units market size in 2026 is estimated at USD 16.95 billion, growing from 2025 value of USD 15.99 billion with 2031 projections showing USD 22.69 billion, growing at 6.01% CAGR over 2026-2031.
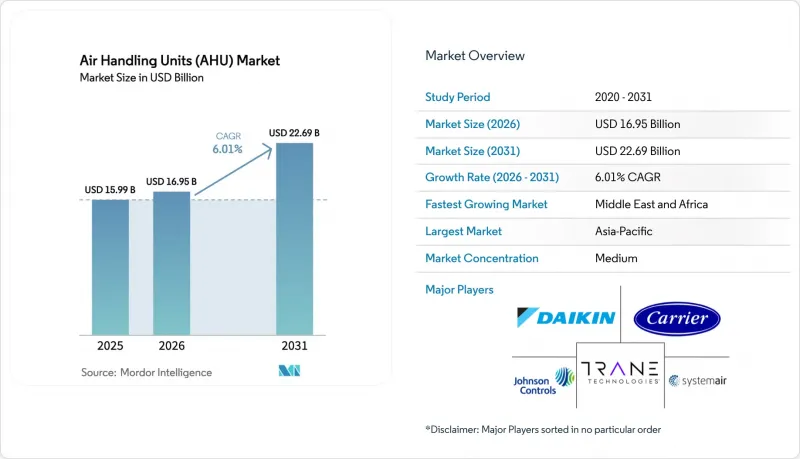
This report is Segmented by Type (Custom, Packaged, Modular, and More), Capacity (Less Than 5, 000, 5, 001-15, 000, and More), Installation (Indoor, Outdoor/Rooftop), Technology (Heat-Pipe, Run-Around Coil, Plate Heat Exchanger, and More), Application (Comfort, Process Ventilation), End-User (Residential, Commercial, Industrial), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Air Handling Units (AHU) Market Trends and Insights
Healthcare & Pharma Clean-room Filtration Uptick in Asia
Asia's pharmaceutical build-out is boosting demand for AHUs that maintain ISO 14644-1 Class 5-to-8 spaces while balancing energy use. Manufacturers tailor units to divergent FDA and EU GMP Annex 1 velocity criteria to serve cross-border production requirements. China and India now specify HEPA-filtered air systems for biotech and semiconductor fabs, integrating real-time particle monitoring with building controls for compliance and efficiency.
EU Ecodesign 2023/813 Mandating Lower SFP & Higher Heat-Recovery
Regulation 2024/1781 requires AHUs to curb fan power and exceed 73% heat-recovery effectiveness, pushing energy wheels from option to baseline. Industrial fans from 125 W to 500 kW must also meet tighter efficiency rules, a change forecast to save 31 TWh by 2030. Lifecycle digital passports extend compliance beyond first sale and create after-sales differentiation.
Volatile Aluminium & Copper Prices Inflating Coil/Fan Costs
Tariffs drove 25% spikes in aluminum and steel costs, compressing AHU margins and deferring projects in 2025. Copper volatility adds risk to heat-exchanger budgets that can represent 30% of unit material value. Manufacturers hedge purchases, redesign for reduced material intensity and renegotiate supply contracts, but engineering cycles lengthen.
Other drivers and restraints analyzed in the detailed report include:
- Hyperscale Data-Centre Build-outs Requiring Modular Indirect Adiabatic AHUs
- Retrofit Demand for Energy-Recovery Ventilation in Japan & South Korea
- Skilled-Labour Shortages Delaying On-site Assembly of Large Custom AHUs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Packaged units held 41.35% 2025 revenue as standard offices favored predictable selection. Modular systems, however, show 8.52% CAGR as data-center developers demand capacity blocks that install quickly and expand without downtime. Custom configurations thrive in pharmaceuticals and electronics manufacturing where bespoke filtration and humidity targets preclude catalog solutions. The air handling units market sees suppliers shifting to configurable frames that shorten lead times while preserving customization. Modular construction also limits skilled-labor exposure by transferring more assembly to the factory, a key advantage in tight labor markets.
Growth momentum stems from hyperscale data processing, where indirect adiabatic modules and liquid-cooling ready coils dominate. Flexible footprints permit phasing that aligns capital spending with rack deployment. As a result, the air handling units market integrates skid-mounted fans, coils and controls into plug-and-play packages validated in-house before shipment.
The 5,001-15,000 m3/h tier accounts for 47.40% 2025 revenues, serving hospitals, higher-education and mixed-use developments. Yet units exceeding 15,000 m3/h expand at 9.25% CAGR driven by electrified process heat and district networks. The air handling units market size for >15,000 m3/h installations is supported by European industrial heat-pump projects totaling 23 GW potential, worth EUR 4.6-11.5 billion. MAN's 20-33 MW CO2 heat-pump illustrates momentum toward mega-scale AHUs integrated with thermal loops.
Smaller capacity units (<5,000 m3/h) stay relevant in premium residential towers where central treatment improves indoor air quality. Variable-speed EC fans and compact heat-recovery wheels help meet tight acoustical and spatial constraints, though market growth lags larger systems.
Complete Report Scope:
- By Type
- Custom
- Packaged
- Modular
- DX Integrated
- Heat-Recovery Units
- By Capacity
- Less than 5,000
- 5,001 - 15,000
- Greater than 15,000
- By Installation Type
- Indoor
- Outdoor / Rooftop
- By Technology
- Heat-Pipe
- Run-Around Coil
- Plate Heat Exchanger
- Desiccant-Based
- Thermodynamic Heat Pump AHU
- By Application
- Comfort Ventilation
- Process Ventilation and Dehumidification
- By End-user
- Residential
- Commercial
- Offices
- Hospitality and Leisure
- Healthcare Facilities
- Educational Institutions
- Retail and Shopping Malls
- Industrial
- Food and Beverage
- Pharmaceuticals and Biotech
- Oil and Gas / Petrochemicals
- Automotive and Machinery
- Other Industrial
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific leads the air handling units market with 31.55% 2025 revenue. China's 185 million-unit air-conditioner production base anchors the regional supply chain, while India's HVAC spending trajectory toward USD 30 billion by 2030 at 15.8% CAGR boosts domestic AHU demand. Japan and South Korea advance retrofit activity through stringent IAQ revisions and successful underground-facility demonstrations that cut radon 98%. Local players collaborate with global OEMs to supply modular systems that satisfy diverse project timelines.
Europe's mature regulatory environment accelerates technology turnover. The Ecodesign framework pushes heat-recovery effectiveness and digital product passports, enlarging the air handling units market share of high-efficiency models. Industrial heat-pump deployment from Scandinavia to Germany drives >15,000 m3/h unit demand. Suppliers navigate extended conformity assessments for A2L refrigerants, but eventual approvals unlock a replacement cycle across aging installations.
The Middle East records the fastest 9.02% CAGR thanks to mega-projects in Saudi Arabia, Qatar and the UAE. District-cooling networks specify desert-ready rooftop AHUs that thrive at 50 °C. Government visions prioritize sustainability, rewarding equipment that reduces peak electricity loads. Meanwhile North America faces raw-material surcharges and technician shortages, yet hyperscale data centers are ordering modular thermal-management systems in volumes unprecedented for the region. The air handling units market size linked to data-center build-outs is projected to expand at double-digit rates through 2031.
- Daikin Industries Ltd.
- Carrier Global Corp.
- Trane Technologies plc
- Lennox International Inc.
- Johnson Controls International plc
- Systemair AB
- TROX GmbH
- Swegon Group AB
- Hitachi Ltd.
- Blue Star Ltd.
- FlaktGroup
- Greenheck Fan Corp.
- Nortek Air Solutions
- GEA Group AG
- Mitsubishi Electric Hydronics (Climaveneta)
- Dantherm A/S
- VTS Group
- Munters AB
- Howden Group
- Modine Manufacturing Co.
- CIAT Group (Carrier)
- TICA Industries
- Trosten Industries Co. LLC
- Johnson Controls-Hitachi Air Conditioning
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Healthcare and Pharma Clean-room Filtration Uptick in Asia
- 4.2.2 EU Ecodesign 2023/813 Mandating Lower SFP and Higher Heat-Recovery
- 4.2.3 Hyperscale Data-Centre Build-outs Requiring Modular Indirect Adiabatic AHUs (N. America)
- 4.2.4 Retrofit Demand for Energy-Recovery Ventilation in Japan and South Korea
- 4.2.5 GCC District-Cooling Projects Spurring Custom High-Ambient Rooftop AHUs
- 4.2.6 Electrification of Industrial Heat Loads Driving Heat-Pump AHUs Greater than15 000 m3/h (Europe)
- 4.3 Market Restraints
- 4.3.1 Volatile Aluminium and Copper Prices Inflating Coil/Fan Costs
- 4.3.2 Skilled-Labour Shortages Delaying On-site Assembly of Large Custom AHUs (US)
- 4.3.3 Decentralised DOAS Adoption as Substitute in Small Commercial Spaces
- 4.3.4 Lengthy EU Approvals for Low-GWP Refrigerant Equipment
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macro Trends on the Market
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Custom
- 5.1.2 Packaged
- 5.1.3 Modular
- 5.1.4 DX Integrated
- 5.1.5 Heat-Recovery Units
- 5.2 By Capacity
- 5.2.1 Less than 5,000
- 5.2.2 5,001 - 15,000
- 5.2.3 Greater than 15,000
- 5.3 By Installation Type
- 5.3.1 Indoor
- 5.3.2 Outdoor / Rooftop
- 5.4 By Technology
- 5.4.1 Heat-Pipe
- 5.4.2 Run-Around Coil
- 5.4.3 Plate Heat Exchanger
- 5.4.4 Desiccant-Based
- 5.4.5 Thermodynamic Heat Pump AHU
- 5.5 By Application
- 5.5.1 Comfort Ventilation
- 5.5.2 Process Ventilation and Dehumidification
- 5.6 By End-user
- 5.6.1 Residential
- 5.6.2 Commercial
- 5.6.2.1 Offices
- 5.6.2.2 Hospitality and Leisure
- 5.6.2.3 Healthcare Facilities
- 5.6.2.4 Educational Institutions
- 5.6.2.5 Retail and Shopping Malls
- 5.6.3 Industrial
- 5.6.3.1 Food and Beverage
- 5.6.3.2 Pharmaceuticals and Biotech
- 5.6.3.3 Oil and Gas / Petrochemicals
- 5.6.3.4 Automotive and Machinery
- 5.6.3.5 Other Industrial
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 United Kingdom
- 5.7.2.2 Germany
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 South Korea
- 5.7.3.5 Rest of Asia-Pacific
- 5.7.4 Middle East
- 5.7.4.1 Israel
- 5.7.4.2 Saudi Arabia
- 5.7.4.3 United Arab Emirates
- 5.7.4.4 Turkey
- 5.7.4.5 Rest of Middle East
- 5.7.5 Africa
- 5.7.5.1 South Africa
- 5.7.5.2 Egypt
- 5.7.5.3 Rest of Africa
- 5.7.6 South America
- 5.7.6.1 Brazil
- 5.7.6.2 Argentina
- 5.7.6.3 Rest of South America
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Daikin Industries Ltd.
- 6.4.2 Carrier Global Corp.
- 6.4.3 Trane Technologies plc
- 6.4.4 Lennox International Inc.
- 6.4.5 Johnson Controls International plc
- 6.4.6 Systemair AB
- 6.4.7 TROX GmbH
- 6.4.8 Swegon Group AB
- 6.4.9 Hitachi Ltd.
- 6.4.10 Blue Star Ltd.
- 6.4.11 FlaktGroup
- 6.4.12 Greenheck Fan Corp.
- 6.4.13 Nortek Air Solutions
- 6.4.14 GEA Group AG
- 6.4.15 Mitsubishi Electric Hydronics (Climaveneta)
- 6.4.16 Dantherm A/S
- 6.4.17 VTS Group
- 6.4.18 Munters AB
- 6.4.19 Howden Group
- 6.4.20 Modine Manufacturing Co.
- 6.4.21 CIAT Group (Carrier)
- 6.4.22 TICA Industries
- 6.4.23 Trosten Industries Co. LLC
- 6.4.24 Johnson Controls-Hitachi Air Conditioning
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

