PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2131875
PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2131875
Switchgear Market by Insulation type (Gas-insulated, Air-insulated), Installation (Indoor, Outdoor), Current (AC, DC), Voltage (Low, Medium, High), End User (Power Utilities, Industries, Renewables, Datacenter), and Region - Global Forecast to 2031
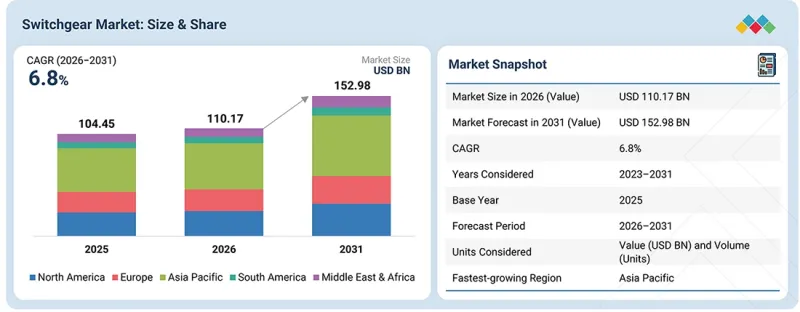
The switchgear market is valued at USD 104.45 billion in 2025 and is estimated to reach USD 110.17 billion in 2026, before reaching USD 152.98 billion by 2031, registering a CAGR of 6.8% during the forecast period of 2026-2031. This growth is supported by a combination of structural and cyclical demand drivers across the global power ecosystem.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2023-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Billion), Volume (Units) |
| Segments | by Insulation type , Voltage, End User, and Region |
| Regions covered | North America, Europe, Asia Pacific, Middle East & Africa, South America |
Utilities worldwide are undertaking large-scale grid modernization and transmission and distribution infrastructure upgrades to replace aging assets, enhance grid reliability, and accommodate increasing electricity demand driven by rapid urbanization and industrialization, particularly across emerging economies in Asia Pacific, the Middle East, and South America.
Concurrently, the accelerating addition of renewable energy capacity, including utility-scale solar and wind installations, is generating significant demand for switchgear to support grid interconnection, power evacuation, and collection-system protection. The rapid expansion of global data center capacity, driven by cloud computing, artificial intelligence workloads, and digitalization, is further increasing demand for high-reliability and redundant power distribution infrastructure, including advanced medium- and low-voltage switchgear. In addition, the electrification of transportation and the associated expansion of EV charging infrastructure, together with continued industrial capacity expansion across oil and gas, metals, chemicals, and manufacturing, is supporting sustained investment in switchgear equipment across voltage classes and end-use segments.
Beyond these core demand drivers, the market is being shaped by several emerging trends influencing technology adoption, product innovation, and competitive positioning. A key trend is the accelerating transition from SF6 gas-insulated switchgear toward SF6-free and eco-efficient alternatives, driven by tightening environmental regulations and utility sustainability commitments focused on reducing greenhouse gas emissions from the power sector. The integration of digital technologies, including IoT-enabled sensors, real-time condition monitoring, predictive maintenance analytics, and digital twin capabilities, is transforming conventional switchgear into intelligent, grid-aware assets that improve operational efficiency and reduce unplanned outages. The market is also witnessing increasing adoption of compact and space-optimized switchgear designs, particularly gas-insulated and hybrid configurations, to address land constraints in urban substations, offshore wind platforms, and space-constrained industrial facilities. Furthermore, the growing penetration of DC-based applications, including HVDC transmission corridors, data center power architectures, and renewable energy systems, is driving increased interest in DC switchgear solutions. Finally, the growing focus on grid resilience and decentralized energy systems, including microgrids and distributed energy resources, is supporting the adoption of modular and digitally integrated switchgear solutions capable of managing bidirectional power flows and increasingly dynamic grid conditions.
"Air-insulated switchgear held the largest share of the switchgear market, by insulation type, in 2025."
Air-insulated switchgear holds the largest market share in 2025, primarily due to its lower capital cost, ease of installation and maintenance, and broad compatibility with existing utility and industrial infrastructure. Its widespread legacy installed base, particularly across cost-sensitive markets in Asia Pacific, South America, and the Middle East & Africa, continues to support strong replacement and brownfield demand. Additionally, AIS avoids the regulatory scrutiny associated with SF6-based gas-insulated systems, while its simpler design ensures broader manufacturer availability and lower total cost of ownership, together reinforcing its dominant position in the market.
"By installation, the indoor segment accounted for the largest market share in 2025."
The indoor segment held the largest market share in 2025, driven by its widespread adoption across urban substations, commercial buildings, industrial facilities, and data centers, where space optimization and protection from weather and environmental exposure are key priorities. Indoor switchgear also supports safer operation and easier maintenance in densely populated and space-constrained settings, making it the preferred choice for utilities and businesses expanding within urban and metropolitan areas. Additionally, rising investments in data centers and commercial infrastructure, both of which favor compact, enclosed switchgear solutions, continue to reinforce the segment's leading position in the overall market.
Breakdown of Primaries:
In-depth interviews with key industry participants, subject-matter experts, C-level executives of key market players, and industry consultants, among other experts, were conducted to obtain and verify critical qualitative and quantitative information, as well as to assess future market prospects. The primary interviews were distributed as follows:
By Company Type: Tier 1 - 40%, Tier 2 - 35%, and Tier 3 - 25%
By Designation: C-Level Executives - 35%, Directors - 25%, and Managers - 40%
By Region: Asia Pacific - 55%, North America - 20%, Europe - 12%, Middle East & Africa - 8%, and South America - 5%,
Notes: Managers include sales managers, production managers, and regional managers.
Tier 1 company: revenue >USD 5 billion; tier 2 company: revenue between USD 1 and USD 5 billion; and tier 3 company: revenue <USD 1 billion in 2025
Well-established global leaders predominantly govern the switchgear market. Notable players in the switchgear market include ABB (Switzerland), GE Vernova (US), Siemens (Germany), Schneider Electric (France), Eaton (Ireland), Mitsubishi Electric Corporation (Japan), LS ELECTRIC Co., Ltd. (South Korea), Fuji Electric Co., Ltd. (Japan), HD Hyundai Electric Co., Ltd. (South Korea), TOSHIBA CORPORATION (Japan), and several others.
Research Coverage:
The report offers a detailed definition, description, and forecast of the switchgear market, focusing on insulation types (air-insulated switchgear, gas-insulated switchgears, other insulation types), installation (indoor, outdoor), voltage (low (up to 1 kV), medium (2-36 kV), high (above 36 kV)), current (AC, DC), end user (power utilities, industrial, renewables, commercial, EV charging infrastructure, datacenters, other end users), and region (North America, Europe, Asia Pacific, Middle East & Africa, South America). It provides a qualitative and quantitative analysis of market drivers, limitations, opportunities, and challenges. Key elements covered are competitive landscape assessment, market dynamics, value estimates, and future trends, along with investment information on major players in the switchgear market.
Key Benefits of Buying the Report
The report is thoughtfully designed to benefit both established industry leaders and newcomers in the switchgear market. It provides reliable revenue forecasts for the entire market as well as its individual sub-segments. This data is a valuable resource for stakeholders, enabling them to gain a comprehensive understanding of the competitive landscape and formulate effective market strategies for their businesses. Furthermore, the report serves as a channel for stakeholders to grasp the current state of the market, providing essential insights into market drivers, limitations, challenges, and growth opportunities. By incorporating these insights, stakeholders can make well-informed decisions and stay informed about the constantly evolving dynamics of the switchgear industry.
- Analysis of key drivers (Rising global T&D investment to support electrification, Data center power demand growth driving MV/HV switchgear needs, EV charging infrastructure expansion, Offshore wind and marine project development), restraints (High capital cost of digital and sf6-free switchgear, Volatility in raw material costs), opportunities (Large-scale retrofit demand from aging sf6 installed base, Digital/smart switchgear enabling recurring service revenue), and challenges (Cybersecurity risk from increased digital substation connectivity) influencing the growth of the switchgear market.
- Product Development/Innovation: Product development and innovation in the switchgear market are increasingly centered around sustainability, digitalization, and compactness. Leading manufacturers are investing heavily in SF6-free and eco-efficient switchgear technologies, utilizing alternative insulating mediums such as clean air, vacuum, and synthetic gas blends, in response to tightening environmental regulations and utility net-zero commitments. In parallel, the integration of digital technologies, including IoT-enabled sensors, real-time condition monitoring, predictive maintenance analytics, and digital twin capabilities, is transforming switchgear from passive protective equipment into intelligent, grid-aware assets capable of enhancing operational efficiency and reducing unplanned downtime. Manufacturers are also focused on developing compact, modular switchgear designs to address space constraints in urban substations, offshore wind platforms, and data centers, alongside growing efforts to develop DC-compatible switchgear solutions in support of HVDC transmission, EV charging, and renewable energy applications. Collectively, these innovation efforts are aimed at improving reliability, reducing environmental impact, and enabling greater automation and grid resilience across the evolving power ecosystem.
- Market Development: Market development in the switchgear space is being driven by a combination of strategic partnerships, capacity expansions, and geographic diversification as manufacturers seek to strengthen their positioning across high-growth regions and emerging application areas. Leading players are expanding local manufacturing and assembly facilities, particularly across Asia Pacific, the Middle East, and South America, to capitalize on rising grid infrastructure investment, renewable energy build-out, and industrialization, while also mitigating supply chain risks and import dependencies. Companies are increasingly forming collaborations and joint ventures with utilities, EPC contractors, and renewable energy developers to secure long-term supply agreements and gain early access to large-scale grid modernization and data center projects. At the same time, several manufacturers are pursuing mergers and acquisitions to strengthen their SF6-free and digital switchgear portfolios, acquire complementary technology capabilities, and accelerate entry into high-growth end-use segments such as EV charging infrastructure and hyperscale data centers. These developments collectively reflect a market that is actively repositioning itself to align with evolving regulatory requirements, decentralized energy trends, and the broader digitalization of power infrastructure.
- Market Diversification: Market diversification within the switchgear industry is being shaped by manufacturers' efforts to broaden their presence across insulation technologies, voltage classes, and end-use applications to reduce dependence on any single revenue stream and capture emerging demand pockets. Companies traditionally focused on air-insulated and medium voltage switchgear are increasingly expanding into gas-insulated, SF6-free, and high-voltage product lines to serve transmission-level and space-constrained applications, while also building dedicated DC switchgear portfolios to tap into HVDC transmission, data center, and EV charging opportunities. End-use diversification is equally prominent, with players moving beyond traditional utility and industrial customers to actively target fast-growing segments such as renewables, data centers, and EV charging infrastructure, which offer stronger long-term growth visibility than mature end markets. Geographically, manufacturers are diversifying their footprint beyond core developed markets into emerging economies across Asia Pacific, the Middle East, and South America, supported by local manufacturing, distribution partnerships, and region-specific product customization. This broad-based diversification strategy is enabling companies to balance growth opportunities with risk mitigation, while positioning themselves to capture value across the full spectrum of the evolving power infrastructure landscape.
Competitive Assessment: A comprehensive evaluation has been conducted to scrutinize the market presence, growth strategies, and service offerings of key players in the switchgear market. These prominent companies include ABB (Switzerland), GE Vernova (US), Siemens (Germany), Schneider Electric (France), Eaton (Ireland), Mitsubishi Electric Corporation (Japan), LS ELECTRIC Co., Ltd. (South Korea), Fuji Electric Co., Ltd. (Japan), HD Hyundai Electric Co., Ltd. (South Korea), TOSHIBA CORPORATION (Japan), and several others. This analysis provides in-depth insights into the competitive positions of these major players, their approaches to driving market growth, top companies' market shares within the switchgear market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY CONSIDERED
- 1.5 UNIT CONSIDERED
- 1.6 LIMITATIONS
- 1.7 STAKEHOLDERS
- 1.8 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN SWITCHGEAR MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN SWITCHGEAR MARKET
- 3.2 SWITCHGEAR MARKET, BY REGION
- 3.3 ASIA PACIFIC: SWITCHGEAR MARKET, BY INSTALLATION AND COUNTRY
- 3.4 SWITCHGEAR MARKET SHARE, BY INSTALLATION
- 3.5 SWITCHGEAR MARKET SHARE, BY VOLTAGE
- 3.6 SWITCHGEAR MARKET SHARE, BY INSULATION TYPE
- 3.7 SWITCHGEAR MARKET SHARE, BY CURRENT
- 3.8 SWITCHGEAR MARKET SHARE, BY END USER
- 3.9 SWITCHGEAR MARKET, BY REGION
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Sustained growth in global electricity generation and regional demand expansion
- 4.2.1.2 Rapid growth in data center power demand is accelerating high-density switchgear deployment
- 4.2.1.3 Increasing renewable capacity additions across wind, solar, and hydro are driving new substation and interconnection switchgear demand
- 4.2.1.4 Rising energy-efficiency investments across buildings, industry, and transportation are prompting replacement of aging low- and medium-voltage switchgear
- 4.2.2 RESTRAINTS
- 4.2.2.1 Volatile copper and aluminum prices are rising input costs and compressing manufacturer margins across value chain
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Accelerating electric vehicle sales and charging infrastructure expansion are increasing demand for specialized switchgear systems
- 4.2.3.2 Accelerating offshore wind installations globally are expanding demand for specialized, compact, high-value switchgear systems
- 4.2.3.3 Sustained growth in global power sector investment is translating into higher capital allocation toward transmission and distribution switching infrastructure
- 4.2.4 CHALLENGES
- 4.2.4.1 Shortage of skilled technical workforce for installation, operation, and maintenance of advanced switchgear systems
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.5 EMERGING BUSINESS MODELS AND ECOSYSTEM SHIFTS
- 4.6 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 INTENSITY OF COMPETITIVE RIVALRY
- 5.1.2 THREAT OF NEW ENTRANTS
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 THREAT OF SUBSTITUTES
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST
- 5.2.3 TRENDS IN DATA CENTER INDUSTRY
- 5.2.4 TRENDS IN RENEWABLE ENERGY INDUSTRY
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 PRICING RANGE OF SWITCHGEAR, BY VOLTAGE, 2025
- 5.5.2 AVERAGE SELLING PRICE TREND OF SWITCHGEAR, BY REGION, 2022-2025
- 5.6 TRADE ANALYSIS
- 5.6.1 IMPORT SCENARIO (HS CODE 853720)
- 5.6.2 EXPORT SCENARIO (HS CODE 853720)
- 5.6.3 IMPORT SCENARIO (HS CODE 853521)
- 5.6.4 EXPORT SCENARIO (HS CODE 853521)
- 5.6.5 IMPORT SCENARIO (HS CODE 853529)
- 5.6.6 EXPORT SCENARIO (HS CODE 853529)
- 5.7 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 HORNSEA 3 OFFSHORE WIND FARM POWERED BY SIEMENS ENERGY'S SF6-FREE SWITCHGEAR
- 5.10.2 WESTERN DOWNS BATTERY ENERGY STORAGE SYSTEM ENABLED BY TGOOD'S PREFABRICATED MV SWITCHGEAR
- 5.10.3 KHAVDA RENEWABLE ENERGY ZONE'S HV TRANSMISSION INFRASTRUCTURE DELIVERED BY GE VERNOVA FOR ADANI
- 5.11 IMPACT OF US TARIFF - SWITCHGEAR MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON COUNTRIES/REGIONS
- 5.11.4.1 US
- 5.11.4.2 Europe
- 5.11.4.3 Asia Pacific
- 5.11.5 IMPACT ON END USERS
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 SOLID-STATE SWITCHGEAR AND CIRCUIT BREAKERS
- 6.1.2 SF6-FREE AND ECO-EFFICIENT GAS INSULATION TECHNOLOGY
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 DIGITAL SUBSTATIONS AND IEC 61850-BASED COMMUNICATION PLATFORMS
- 6.2.2 AI AND IOT-ENABLED PREDICTIVE MAINTENANCE PLATFORMS
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 BATTERY ENERGY STORAGE SYSTEMS
- 6.3.2 POWER ELECTRONICS AND WIDE-BANDGAP SEMICONDUCTORS
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 SHORT-TERM (2026-2028) | FOUNDATION AND COMPLIANCE-DRIVEN ADOPTION
- 6.4.2 MID-TERM (2028-2031) | SCALE-UP AND DIGITAL-NATIVE INTEGRATION
- 6.4.3 LONG-TERM (2031-2035+) |AUTONOMOUS, FULLY ELECTRIFIED GRID ECOSYSTEM
- 6.5 PATENT ANALYSIS
- 6.6 FUTURE APPLICATIONS
- 6.7 IMPACT OF AI/GEN AI ON SWITCHGEAR MARKET
- 6.7.1 TOP USE CASES AND MARKET POTENTIAL
- 6.7.2 BEST PRACTICES FOLLOWED BY OEMS IN SWITCHGEAR PROCESSING
- 6.7.3 CASE STUDIES RELATED TO AI/GEN AI IMPLEMENTATION IN SWITCHGEAR MARKET
- 6.7.4 INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.7.5 CLIENTS' READINESS TO ADOPT AI/GEN AI-INTEGRATED SWITCHGEAR
- 6.8 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.3 IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS OF VARIOUS END USERS
- 8.5 MARKET PROFITABILITY
9 SWITCHGEAR MARKET, BY INSULATION TYPE
- 9.1 INTRODUCTION
- 9.2 AIR-INSULATED SWITCHGEAR
- 9.2.1 LOW COST AND SIMPLICITY TO DRIVE ADOPTION
- 9.3 GAS-INSULATED SWITCHGEAR
- 9.3.1 PREFERRED TECHNOLOGY FOR COMPACT AND HIGH RELIABILITY GRID EXPANSION
- 9.4 OTHER INSULATION TYPES
10 SWITCHGEAR MARKET, BY INSTALLATION
- 10.1 INTRODUCTION
- 10.2 INDOOR
- 10.2.1 PREFERRED CHOICE FOR SPACE OPTIMIZED URBAN AND INDUSTRIAL INFRASTRUCTURE
- 10.3 OUTDOOR
- 10.3.1 EXPANSION OF UTILITY-SCALE PROJECTS AND GROWTH OF RENEWABLE ENERGY INFRASTRUCTURE TO PROPEL MARKET
11 SWITCHGEAR MARKET, BY VOLTAGE
- 11.1 INTRODUCTION
- 11.2 LOW (UP TO 1 KV)
- 11.2.1 RISE OF BEHIND-THE-METER POWER SYSTEMS TO DRIVE MARKET
- 11.3 MEDIUM (2-36 KV)
- 11.3.1 DIVERSE HIGH-LOAD APPLICATIONS TO DRIVE ADOPTION
- 11.4 HIGH (ABOVE 36 KV)
- 11.4.1 TRANSMISSION EXPANSION AND LONG-DISTANCE POWER FLOWS TO DRIVE SWITCHGEAR DEMAND
12 SWITCHGEAR MARKET, BY CURRENT
- 12.1 INTRODUCTION
- 12.2 AC
- 12.2.1 CONTINUES TO ANCHOR GLOBAL SWITCHGEAR DEMAND
- 12.3 DC
- 12.3.1 EMERGES AS FASTEST-GROWING SWITCHGEAR SEGMENT AMID RISING ELECTRIFICATION
13 SWITCHGEAR MARKET, BY END USER
- 13.1 INTRODUCTION
- 13.2 POWER UTILITIES
- 13.2.1 INCREASING GRID INVESTMENTS TO DRIVE MARKET
- 13.3 INDUSTRIAL
- 13.3.1 INDUSTRIAL FACILITIES SUSTAIN STEADY DEMAND AS ELECTRIFICATION DEEPENS ACROSS HEAVY MANUFACTURING
- 13.4 COMMERCIAL
- 13.4.1 COMMERCIAL ESTABLISHMENTS EXPAND SWITCHGEAR DEMAND AS BUILDINGS BECOME MORE POWER-INTENSIVE
- 13.5 DATA CENTERS
- 13.5.1 SURGE IN DIGITAL INFRASTRUCTURE DEMAND TO PROPEL MARKET
- 13.6 RENEWABLES
- 13.6.1 DRIVE SUSTAINED SWITCHGEAR DEMAND AS WIND AND SOLAR CAPACITY EXPANDS AT RECORD PACE
- 13.7 EV CHARGING INFRASTRUCTURE
- 13.7.1 GAINS MOMENTUM AS TRANSPORT ELECTRIFICATION ACCELERATES GRID CONNECTION NEEDS
- 13.8 OTHER END USERS
14 SWITCHGEAR MARKET, BY REGION
- 14.1 INTRODUCTION
- 14.2 ASIA PACIFIC
- 14.2.1 CHINA
- 14.2.1.1 Mega-grid expansion, renewable integration, and next-generation SF6-free innovation to drive market
- 14.2.2 INDIA
- 14.2.2.1 Grid digitalization to support market growth
- 14.2.3 JAPAN
- 14.2.3.1 Advancing grid resilience through AI-driven substation expansion, offshore wind policy reform, and SF6-free switchgear leadership to propel market
- 14.2.4 AUSTRALIA
- 14.2.4.1 Building grid flexibility through battery storage scale-up and critical substation renewal to propel market
- 14.2.5 REST OF ASIA PACIFIC
- 14.2.1 CHINA
- 14.3 EUROPE
- 14.3.1 GERMANY
- 14.3.1.1 Grid congestion, offshore wind delays, and battery storage growth to drive switchgear demand
- 14.3.2 UK
- 14.3.2.1 Renewable energy contracts, battery storage growth, and doubling grid connections by 2050 to propel market
- 14.3.3 FRANCE
- 14.3.3.1 Nuclear fleet recovery, renewable acceleration, and new generation of EPR2 reactors to support market growth
- 14.3.4 ITALY
- 14.3.4.1 Renewable energy expansion and grid investments to strengthen switchgear demand
- 14.3.5 REST OF EUROPE
- 14.3.1 GERMANY
- 14.4 NORTH AMERICA
- 14.4.1 US
- 14.4.1.1 USD 2 billion manufacturing buildout to power AI data center boom
- 14.4.2 CANADA
- 14.4.2.1 Battery storage growth and grid infrastructure reinvestment to support market growth
- 14.4.3 MEXICO
- 14.4.3.1 Expanding switchgear manufacturing capacity to propel market
- 14.4.1 US
- 14.5 SOUTH AMERICA
- 14.5.1 BRAZIL
- 14.5.1.1 Renewable-led grid transition, AI data center boom, and multi-billion-real network modernization to drive market
- 14.5.2 ARGENTINA
- 14.5.2.1 Unlocking switchgear demand through Vaca Muerta USD 6.6 billion transmission buildout and landmark AI data center investment
- 14.5.3 REST OF SOUTH AMERICA
- 14.5.1 BRAZIL
- 14.6 MIDDLE EAST & AFRICA
- 14.6.1 GCC COUNTRIES
- 14.6.1.1 Saudi Arabia
- 14.6.1.1.1 Building multi-billion-dollar GIS substation pipeline to connect 130-GW renewable energy source and support AI data center expansion to drive market
- 14.6.1.2 UAE
- 14.6.1.2.1 Scaling substation capacity to power nuclear, 24/7 solar storage, and AI data center growth
- 14.6.1.3 Rest of GCC Countries
- 14.6.1.1 Saudi Arabia
- 14.6.2 EGYPT
- 14.6.2.1 Scale of grid investment and ambitious renewable integration targets to support market growth
- 14.6.3 SOUTH AFRICA
- 14.6.3.1 Landmark independent transmission program and World Bank-backed grid expansion position market for sustained high-voltage switchgear demand
- 14.6.4 REST OF MIDDLE EAST & AFRICA
- 14.6.1 GCC COUNTRIES
15 COMPETITIVE LANDSCAPE
- 15.1 OVERVIEW
- 15.2 KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN, JANUARY 2023-AUGUST 2026
- 15.3 MARKET SHARE ANALYSIS, 2025
- 15.4 REVENUE ANALYSIS, 2021-2025
- 15.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 15.5.1 STARS
- 15.5.2 EMERGING LEADERS
- 15.5.3 PERVASIVE PLAYERS
- 15.5.4 PARTICIPANTS
- 15.5.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 15.5.5.1 Region footprint
- 15.5.5.2 Insulation type footprint
- 15.5.5.3 Installation footprint
- 15.5.5.4 Voltage footprint
- 15.5.5.5 Current footprint
- 15.5.5.6 End-user footprint
- 15.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 15.6.1 PROGRESSIVE COMPANIES
- 15.6.2 RESPONSIVE COMPANIES
- 15.6.3 DYNAMIC COMPANIES
- 15.6.4 STARTING BLOCKS
- 15.6.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 15.6.5.1 Detailed list of key startups/SMEs
- 15.6.5.2 Competitive benchmarking of key startups/SMEs
- 15.7 COMPANY VALUATION AND FINANCIAL METRICS
- 15.8 BRAND COMPARISON
- 15.8.1 ABB (SWITZERLAND)
- 15.8.2 SIEMENS (GERMANY)
- 15.8.3 SCHNEIDER ELECTRIC (FRANCE)
- 15.8.4 EATON (IRELAND)
- 15.8.5 GE VERNOVA (US)
- 15.9 COMPETITIVE SCENARIO
- 15.9.1 PRODUCT LAUNCHES
- 15.9.2 DEALS
- 15.9.3 EXPANSIONS
- 15.9.4 OTHER DEVELOPMENTS
16 COMPANY PROFILES
- 16.1 KEY PLAYERS
- 16.1.1 SCHNEIDER ELECTRIC
- 16.1.1.1 Business overview
- 16.1.1.2 Products/Solutions/Services offered
- 16.1.1.3 Recent developments
- 16.1.1.3.1 Product launches
- 16.1.1.3.2 Deals
- 16.1.1.3.3 Expansions
- 16.1.1.3.4 Other developments
- 16.1.1.4 MnM view
- 16.1.1.4.1 Key strengths/Right to win
- 16.1.1.4.2 Strategic choices
- 16.1.1.4.3 Weaknesses/Competitive threats
- 16.1.2 ABB
- 16.1.2.1 Business overview
- 16.1.2.2 Products/Solutions/Services offered
- 16.1.2.3 Recent developments
- 16.1.2.3.1 Product launches
- 16.1.2.3.2 Deals
- 16.1.2.3.3 Expansions
- 16.1.2.3.4 Other developments
- 16.1.2.4 MnM view
- 16.1.2.4.1 Key strengths/Right to win
- 16.1.2.4.2 Strategic choices
- 16.1.2.4.3 Weaknesses/Competitive threats
- 16.1.3 SIEMENS
- 16.1.3.1 Business overview
- 16.1.3.2 Products/Solutions/Services offered
- 16.1.3.3 Recent developments
- 16.1.3.3.1 Product launches
- 16.1.3.3.2 Deals
- 16.1.3.3.3 Expansions
- 16.1.3.3.4 Other developments
- 16.1.3.4 MnM view
- 16.1.3.4.1 Key strengths/Right to win
- 16.1.3.4.2 Strategic choices
- 16.1.3.4.3 Weaknesses/Competitive threats
- 16.1.4 GE VERNOVA
- 16.1.4.1 Business overview
- 16.1.4.2 Products/Solutions/Services offered
- 16.1.4.3 Recent developments
- 16.1.4.3.1 Product launches
- 16.1.4.3.2 Deals
- 16.1.4.3.3 Expansions
- 16.1.4.3.4 Other developments
- 16.1.4.4 MnM view
- 16.1.4.4.1 Key strengths/Right to win
- 16.1.4.4.2 Strategic choices
- 16.1.4.4.3 Weaknesses/Competitive threats
- 16.1.5 EATON
- 16.1.5.1 Business overview
- 16.1.5.2 Products/Solutions/Services offered
- 16.1.5.3 Recent developments
- 16.1.5.3.1 Product launches
- 16.1.5.3.2 Deals
- 16.1.5.3.3 Expansions
- 16.1.5.3.4 Other developments
- 16.1.5.4 MnM view
- 16.1.5.4.1 Key strengths/Right to win
- 16.1.5.4.2 Strategic choices
- 16.1.5.4.3 Weaknesses/Competitive threats
- 16.1.6 HITACHI ENERGY LTD.
- 16.1.6.1 Business overview
- 16.1.6.2 Products/Solutions/Services offered
- 16.1.6.3 Recent developments
- 16.1.6.3.1 Other developments
- 16.1.7 SIEMENS ENERGY
- 16.1.7.1 Business overview
- 16.1.7.2 Products/Solutions/Services offered
- 16.1.7.3 Recent developments
- 16.1.7.3.1 Deals
- 16.1.7.3.2 Expansions
- 16.1.7.3.3 Other developments
- 16.1.8 MITSUBISHI ELECTRIC CORPORATION
- 16.1.8.1 Business overview
- 16.1.8.2 Products/Solutions/Services offered
- 16.1.8.3 Recent developments
- 16.1.8.3.1 Deals
- 16.1.8.3.2 Expansions
- 16.1.8.3.3 Other developments
- 16.1.9 FUJI ELECTRIC CO., LTD.
- 16.1.9.1 Business overview
- 16.1.9.2 Products/Solutions/Services offered
- 16.1.9.3 Recent developments
- 16.1.9.3.1 Expansions
- 16.1.9.3.2 Other developments
- 16.1.10 HYOSUNG HEAVY INDUSTRIES
- 16.1.10.1 Business overview
- 16.1.10.2 Products/Solutions/Services offered
- 16.1.10.3 Recent developments
- 16.1.10.3.1 Other developments
- 16.1.11 TOSHIBA CORPORATION
- 16.1.11.1 Business overview
- 16.1.11.2 Products/Solutions/Services offered
- 16.1.11.3 Recent developments
- 16.1.11.3.1 Expansions
- 16.1.11.3.2 Other developments
- 16.1.12 HD HYUNDAI ELECTRIC CO., LTD.
- 16.1.12.1 Business overview
- 16.1.12.2 Products/Solutions/Services offered
- 16.1.12.3 Recent developments
- 16.1.12.3.1 Other developments
- 16.1.13 MEIDENSHA CORPORATION
- 16.1.13.1 Business overview
- 16.1.13.2 Products/Solutions/Services offered
- 16.1.13.3 Recent developments
- 16.1.13.3.1 Expansions
- 16.1.14 CG POWER & INDUSTRIAL SOLUTIONS LTD.
- 16.1.14.1 Business overview
- 16.1.14.2 Products/Solutions/Services offered
- 16.1.14.3 Recent developments
- 16.1.14.3.1 Expansions
- 16.1.14.3.2 Other developments
- 16.1.15 LS ELECTRIC CO., LTD.
- 16.1.15.1 Business overview
- 16.1.15.2 Products/Solutions/Services offered
- 16.1.15.3 Recent developments
- 16.1.15.3.1 Deals
- 16.1.15.3.2 Expansions
- 16.1.15.3.3 Other developments
- 16.1.16 NVENT ELECTRIC PLC
- 16.1.16.1 Business overview
- 16.1.16.2 Products/Solutions/Services offered
- 16.1.16.3 Recent developments
- 16.1.16.3.1 Deals
- 16.1.17 CHINT GROUP
- 16.1.17.1 Business overview
- 16.1.17.2 Products/Solutions/Services offered
- 16.1.18 WEG
- 16.1.18.1 Business overview
- 16.1.18.2 Products/Solutions/Services offered
- 16.1.19 DOHO ELECTRIC
- 16.1.19.1 Business overview
- 16.1.19.2 Products/Solutions/Services offered
- 16.1.20 LUCY ELECTRIC
- 16.1.20.1 Business overview
- 16.1.20.2 Products/Solutions/Services offered
- 16.1.20.3 Recent developments
- 16.1.20.3.1 Deals
- 16.1.21 TBEA CO., LTD.
- 16.1.21.1 Business overview
- 16.1.21.2 Products/Solutions/Services offered
- 16.1.21.3 Recent developments
- 16.1.21.3.1 Deals
- 16.1.1 SCHNEIDER ELECTRIC
- 16.2 OTHER PLAYERS
- 16.2.1 BHARAT HEAVY ELECTRICALS LIMITED
- 16.2.2 CHINA XD ELECTRIC CO., LTD.
- 16.2.3 TGOOD GLOBAL
- 16.2.4 SIEYUAN ELECTRIC CO., LTD.
- 16.2.5 ORMAZABAL
- 16.2.6 S&C ELECTRIC COMPANY
- 16.2.7 SGC SWITCHGEAR COMPANY
17 RESEARCH METHODOLOGY
- 17.1 RESEARCH DATA
- 17.1.1 SECONDARY DATA
- 17.1.1.1 List of key secondary sources
- 17.1.1.2 Key data from secondary sources
- 17.1.2 PRIMARY DATA
- 17.1.2.1 Key data from primary sources
- 17.1.2.2 List of primary interview participants
- 17.1.2.3 Key industry insights
- 17.1.2.4 Breakdown of primary interviews
- 17.1.1 SECONDARY DATA
- 17.2 MARKET SIZE ESTIMATION
- 17.2.1 BOTTOM-UP APPROACH
- 17.2.2 TOP-DOWN APPROACH
- 17.2.3 DEMAND-SIDE ANALYSIS
- 17.2.3.1 Regional analysis
- 17.2.3.2 Country analysis
- 17.2.3.3 Demand-side assumptions
- 17.2.3.4 Demand-side calculations
- 17.2.4 SUPPLY-SIDE ANALYSIS
- 17.2.4.1 Supply-side assumptions
- 17.2.4.2 Supply-side calculations
- 17.3 MARKET FORECAST APPROACH
- 17.4 DATA TRIANGULATION
- 17.5 FACTOR ANALYSIS
- 17.6 RESEARCH ASSUMPTIONS AND LIMITATIONS
- 17.7 RISK ANALYSIS
18 APPENDIX
- 18.1 INSIGHTS FROM INDUSTRY EXPERTS
- 18.2 DISCUSSION GUIDE
- 18.3 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 18.4 CUSTOMIZATION OPTIONS
- 18.5 RELATED REPORTS
- 18.6 AUTHOR DETAILS
List of Tables
- TABLE 1 SWITCHGEAR MARKET: INCLUSIONS AND EXCLUSIONS
- TABLE 2 SWITCHGEAR MARKET: SUMMARY OF CHANGES
- TABLE 3 INTERCONNECTED MARKETS
- TABLE 4 KEY MOVES AND STRATEGIC FOCUS OF TIER-1/2/3 PLAYERS
- TABLE 5 IMPACT OF PORTER'S FIVE FORCES
- TABLE 6 GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2022-2031
- TABLE 7 SWITCHGEAR MARKET: ROLE OF COMPANIES IN SWITCHGEAR ECOSYSTEM
- TABLE 8 PRICING RANGE OF SWITCHGEAR, BY VOLTAGE, 2025 (USD/UNIT)
- TABLE 9 AVERAGE SELLING PRICE TREND OF SWITCHGEAR, BY REGION, 2022-2025 (USD/UNIT)
- TABLE 10 IMPORT DATA FOR HS CODE 853720-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 11 EXPORT DATA FOR HS CODE 853720-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 12 IMPORT DATA FOR HS CODE 853521-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 13 EXPORT DATA FOR HS CODE 853521-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 14 IMPORT DATA FOR HS CODE 853529-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 15 EXPORT DATA FOR HS CODE 853529-COMPLIANT PRODUCTS, BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 16 SWITCHGEAR MARKET: KEY CONFERENCES AND EVENTS
- TABLE 17 SIEMENS ENERGY DEPLOYMENT OF 8VM1 BLUE GIS FOR OFFSHORE WIND POWER GENERATION
- TABLE 18 TGOOD SUPPLIES MEDIUM VOLTAGE GIS FOR GRID CONNECTION OF WESTERN DOWNS BATTERY ENERGY STORAGE SYSTEM
- TABLE 19 GE VERNOVA STRENGTHENS RENEWABLE POWER TRANSMISSION AT KHAVDA WITH HIGH VOLTAGE GIS
- TABLE 20 US-ADJUSTED RECIPROCAL TARIFF RATES
- TABLE 21 EXPECTED CHANGE IN PRICES AND POTENTIAL IMPACT ON MARKET PLAYERS DUE TO TARIFFS
- TABLE 22 LIST OF KEY PATENTS, 2025-2026
- TABLE 23 AI-DRIVEN HYPERSCALE DATA CENTER POWER INFRASTRUCTURE
- TABLE 24 OFFSHORE WIND AND HVDC GRID INTEGRATION
- TABLE 25 GREEN HYDROGEN AND POWER-TO-X FACILITIES
- TABLE 26 VEHICLE-TO-GRID (V2G) AND BIDIRECTIONAL EV CHARGING NETWORKS
- TABLE 27 AUTONOMOUS SELF-HEALING MICROGRIDS
- TABLE 28 MAJOR USE CASES AND MARKET POTENTIAL
- TABLE 29 BEST PRACTICES FOLLOWED BY COMPANIES
- TABLE 30 CASE STUDIES RELATED TO AI/GEN AI IMPLEMENTATION
- TABLE 31 INTERCONNECTED ECOSYSTEM AND IMPACT ON SWITCHGEAR MARKET PLAYERS
- TABLE 32 GLOBAL: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 33 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 34 EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 35 ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 36 MIDDLE EAST & AFRICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 37 SOUTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 38 GLOBAL INDUSTRY STANDARDS IN SWITCHGEAR MARKET
- TABLE 39 CERTIFICATIONS, LABELING, AND ECO-STANDARDS IN SWITCHGEAR MARKET
- TABLE 40 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP THREE END USER (%)
- TABLE 41 KEY BUYING CRITERIA FOR TOP THREE END USERS
- TABLE 42 UNMET NEEDS, BY END USER
- TABLE 43 SWITCHGEAR MARKET, BY INSULATION TYPE, 2022-2025 (USD BILLION)
- TABLE 44 SWITCHGEAR MARKET, BY INSULATION TYPE, 2026-2031 (USD BILLION)
- TABLE 45 AIR-INSULATED: SWITCHGEAR MARKET, BY REGION, 2022-2025 (USD BILLION)
- TABLE 46 AIR-INSULATED: SWITCHGEAR MARKET, BY REGION, 2026-2031 (USD BILLION)
- TABLE 47 GAS-INSULATED: SWITCHGEAR MARKET, BY REGION, 2022-2025 (USD BILLION)
- TABLE 48 GAS-INSULATED: SWITCHGEAR MARKET, BY REGION, 2026-2031 (USD BILLION)
- TABLE 49 OTHER INSULATION TYPES: SWITCHGEAR MARKET, BY REGION, 2022-2025 (USD BILLION)
- TABLE 50 OTHER INSULATION TYPES: SWITCHGEAR MARKET, BY REGION, 2026-2031 (USD BILLION)
- TABLE 51 SWITCHGEAR MARKET, BY INSTALLATION, 2022-2025 (USD BILLION)
- TABLE 52 SWITCHGEAR MARKET, BY INSTALLATION, 2026-2031 (USD BILLION)
- TABLE 53 INDOOR: SWITCHGEAR MARKET, BY REGION, 2022-2025 (USD BILLION)
- TABLE 54 INDOOR: SWITCHGEAR MARKET, BY REGION, 2026-2031 (USD BILLION)
- TABLE 55 OUTDOOR: SWITCHGEAR MARKET, BY REGION, 2022-2025 (USD BILLION)
- TABLE 56 OUTDOOR: SWITCHGEAR MARKET, BY REGION, 2026-2031 (USD BILLION)
- TABLE 57 SWITCHGEAR MARKET, BY VOLTAGE, 2022-2025 (USD BILLION)
- TABLE 58 SWITCHGEAR MARKET, BY VOLTAGE, 2026-2031 (USD BILLION)
- TABLE 59 LOW (UP TO 1 KV): SWITCHGEAR MARKET, BY REGION, 2022-2025 (USD BILLION)
- TABLE 60 LOW (UP TO 1 KV): SWITCHGEAR MARKET, BY REGION, 2026-2031 (USD BILLION)
- TABLE 61 MEDIUM (2-36 KV): SWITCHGEAR MARKET, BY REGION, 2022-2025 (USD BILLION)
- TABLE 62 MEDIUM (2-36 KV): SWITCHGEAR MARKET, BY REGION, 2026-2031 (USD BILLION)
- TABLE 63 HIGH (ABOVE 36 KV): SWITCHGEAR MARKET, BY REGION, 2022-2025 (USD BILLION)
- TABLE 64 HIGH (ABOVE 36 KV): SWITCHGEAR MARKET, BY REGION, 2026-2031 (USD BILLION)
- TABLE 65 SWITCHGEAR MARKET, BY CURRENT, 2022-2025 (USD BILLION)
- TABLE 66 SWITCHGEAR MARKET, BY CURRENT, 2026-2031 (USD BILLION)
- TABLE 67 AC: SWITCHGEAR MARKET, BY REGION, 2022-2025 (USD BILLION)
- TABLE 68 AC: SWITCHGEAR MARKET, BY REGION, 2026-2031 (USD BILLION)
- TABLE 69 DC: SWITCHGEAR MARKET, BY REGION, 2022-2025 (USD BILLION)
- TABLE 70 DC: SWITCHGEAR MARKET, BY REGION, 2026-2031 (USD BILLION)
- TABLE 71 SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 72 SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 73 POWER UTILITIES: SWITCHGEAR MARKET, BY REGION, 2022-2025 (USD BILLION)
- TABLE 74 POWER UTILITIES: SWITCHGEAR MARKET, BY REGION, 2026-2031 (USD BILLION)
- TABLE 75 INDUSTRIAL: SWITCHGEAR MARKET, BY REGION, 2022-2025 (USD BILLION)
- TABLE 76 INDUSTRIAL: SWITCHGEAR MARKET, BY REGION, 2026-2031 (USD BILLION)
- TABLE 77 COMMERCIAL: SWITCHGEAR MARKET, BY REGION, 2022-2025 (USD BILLION)
- TABLE 78 COMMERCIAL: SWITCHGEAR MARKET, BY REGION, 2026-2031 (USD BILLION)
- TABLE 79 DATA CENTERS: SWITCHGEAR MARKET, BY REGION, 2022-2025 (USD BILLION)
- TABLE 80 DATA CENTERS: SWITCHGEAR MARKET, BY REGION, 2026-2031 (USD BILLION)
- TABLE 81 RENEWABLES: SWITCHGEAR MARKET, BY REGION, 2022-2025 (USD BILLION)
- TABLE 82 RENEWABLES: SWITCHGEAR MARKET, BY REGION, 2026-2031 (USD BILLION)
- TABLE 83 EV CHARGING INFRASTRUCTURE: SWITCHGEAR MARKET, BY REGION, 2022-2025 (USD BILLION)
- TABLE 84 EV CHARGING INFRASTRUCTURE: SWITCHGEAR MARKET, BY REGION, 2026-2031 (USD BILLION)
- TABLE 85 OTHER END USERS: SWITCHGEAR MARKET, BY REGION, 2022-2025 (USD BILLION)
- TABLE 86 OTHER END USERS: SWITCHGEAR MARKET, BY REGION, 2026-2031 (USD BILLION)
- TABLE 87 SWITCHGEAR MARKET, BY REGION, 2022-2025 (USD BILLION)
- TABLE 88 SWITCHGEAR MARKET, BY REGION, 2026-2031 (USD BILLION)
- TABLE 89 SWITCHGEAR MARKET, BY REGION, 2022-2025 (UNITS)
- TABLE 90 SWITCHGEAR MARKET, BY REGION, 2026-2031 (UNITS)
- TABLE 91 ASIA PACIFIC: SWITCHGEAR MARKET, BY INSULATION TYPE, 2022-2025 (USD BILLION)
- TABLE 92 ASIA PACIFIC: SWITCHGEAR MARKET, BY INSULATION TYPE, 2026-2031 (USD BILLION)
- TABLE 93 ASIA PACIFIC: SWITCHGEAR MARKET, BY INSTALLATION, 2022-2025 (USD BILLION)
- TABLE 94 ASIA PACIFIC: SWITCHGEAR MARKET, BY INSTALLATION, 2026-2031 (USD BILLION)
- TABLE 95 ASIA PACIFIC: SWITCHGEAR MARKET, BY VOLTAGE, 2022-2025 (USD BILLION)
- TABLE 96 ASIA PACIFIC: SWITCHGEAR MARKET, BY VOLTAGE, 2026-2031 (USD BILLION)
- TABLE 97 ASIA PACIFIC: SWITCHGEAR MARKET, BY CURRENT, 2022-2025 (USD BILLION)
- TABLE 98 ASIA PACIFIC: SWITCHGEAR MARKET, BY CURRENT, 2026-2031 (USD BILLION)
- TABLE 99 ASIA PACIFIC: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 100 ASIA PACIFIC: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 101 ASIA PACIFIC: SWITCHGEAR MARKET, BY COUNTRY, 2022-2025 (USD BILLION)
- TABLE 102 ASIA PACIFIC: SWITCHGEAR MARKET, BY COUNTRY, 2026-2031 (USD BILLION)
- TABLE 103 CHINA: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 104 CHINA: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 105 INDIA: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 106 INDIA: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 107 JAPAN: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 108 JAPAN: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 109 AUSTRALIA: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 110 AUSTRALIA: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 111 REST OF ASIA PACIFIC: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 112 REST OF ASIA PACIFIC: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 113 EUROPE: SWITCHGEAR MARKET, BY INSULATION TYPE, 2022-2025 (USD BILLION)
- TABLE 114 EUROPE: SWITCHGEAR MARKET, BY INSULATION TYPE, 2026-2031 (USD BILLION)
- TABLE 115 EUROPE: SWITCHGEAR MARKET, BY INSTALLATION, 2022-2025 (USD BILLION)
- TABLE 116 EUROPE: SWITCHGEAR MARKET, BY INSTALLATION, 2026-2031 (USD BILLION)
- TABLE 117 EUROPE: SWITCHGEAR MARKET, BY VOLTAGE, 2022-2025 (USD BILLION)
- TABLE 118 EUROPE: SWITCHGEAR MARKET, BY VOLTAGE, 2026-2031 (USD BILLION)
- TABLE 119 EUROPE: SWITCHGEAR MARKET, BY CURRENT, 2022-2025 (USD BILLION)
- TABLE 120 EUROPE: SWITCHGEAR MARKET, BY CURRENT, 2026-2031 (USD BILLION)
- TABLE 121 EUROPE: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 122 EUROPE: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 123 EUROPE: SWITCHGEAR MARKET, BY COUNTRY, 2022-2025 (USD BILLION)
- TABLE 124 EUROPE: SWITCHGEAR MARKET, BY COUNTRY, 2026-2031 (USD BILLION)
- TABLE 125 GERMANY: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 126 GERMANY: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 127 UK: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 128 UK: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 129 FRANCE: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 130 FRANCE: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 131 ITALY: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 132 ITALY: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 133 REST OF EUROPE: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 134 REST OF EUROPE: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 135 NORTH AMERICA: SWITCHGEAR MARKET, BY INSULATION TYPE, 2022-2025 (USD BILLION)
- TABLE 136 NORTH AMERICA: SWITCHGEAR MARKET, BY INSULATION TYPE, 2026-2031 (USD BILLION)
- TABLE 137 NORTH AMERICA: SWITCHGEAR MARKET, BY INSTALLATION, 2022-2025 (USD BILLION)
- TABLE 138 NORTH AMERICA: SWITCHGEAR MARKET, BY INSTALLATION, 2026-2031 (USD BILLION)
- TABLE 139 NORTH AMERICA: SWITCHGEAR MARKET, BY VOLTAGE, 2022-2025 (USD BILLION)
- TABLE 140 NORTH AMERICA: SWITCHGEAR MARKET, BY VOLTAGE, 2026-2031 (USD BILLION)
- TABLE 141 NORTH AMERICA: SWITCHGEAR MARKET, BY CURRENT, 2022-2025 (USD BILLION)
- TABLE 142 NORTH AMERICA: SWITCHGEAR MARKET, BY CURRENT, 2026-2031 (USD BILLION)
- TABLE 143 NORTH AMERICA: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 144 NORTH AMERICA: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 145 NORTH AMERICA: SWITCHGEAR MARKET, BY COUNTRY, 2022-2025 (USD BILLION)
- TABLE 146 NORTH AMERICA: SWITCHGEAR MARKET, BY COUNTRY, 2026-2031 (USD BILLION)
- TABLE 147 US: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 148 US: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 149 CANADA: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 150 CANADA: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 151 MEXICO: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 152 MEXICO: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 153 SOUTH AMERICA: SWITCHGEAR MARKET, BY INSULATION TYPE, 2022-2025 (USD BILLION)
- TABLE 154 SOUTH AMERICA: SWITCHGEAR MARKET, BY INSULATION TYPE, 2026-2031 (USD BILLION)
- TABLE 155 SOUTH AMERICA: SWITCHGEAR MARKET, BY INSTALLATION, 2022-2025 (USD BILLION)
- TABLE 156 SOUTH AMERICA: SWITCHGEAR MARKET, BY INSTALLATION, 2026-2031 (USD BILLION)
- TABLE 157 SOUTH AMERICA: SWITCHGEAR MARKET, BY VOLTAGE, 2022-2025 (USD BILLION)
- TABLE 158 SOUTH AMERICA: SWITCHGEAR MARKET, BY VOLTAGE, 2026-2031 (USD BILLION)
- TABLE 159 SOUTH AMERICA: SWITCHGEAR MARKET, BY CURRENT, 2022-2025 (USD BILLION)
- TABLE 160 SOUTH AMERICA: SWITCHGEAR MARKET, BY CURRENT, 2026-2031 (USD BILLION)
- TABLE 161 SOUTH AMERICA: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 162 SOUTH AMERICA: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 163 SOUTH AMERICA: SWITCHGEAR MARKET, BY COUNTRY, 2022-2025 (USD BILLION)
- TABLE 164 SOUTH AMERICA: SWITCHGEAR MARKET, BY COUNTRY, 2026-2031 (USD BILLION)
- TABLE 165 BRAZIL: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 166 BRAZIL: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 167 ARGENTINA: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 168 ARGENTINA: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 169 REST OF SOUTH AMERICA: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 170 REST OF SOUTH AMERICA: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 171 MIDDLE EAST & AFRICA: SWITCHGEAR MARKET, BY INSULATION TYPE, 2022-2025 (USD BILLION)
- TABLE 172 MIDDLE EAST & AFRICA: SWITCHGEAR MARKET, BY INSULATION TYPE, 2026-2031 (USD BILLION)
- TABLE 173 MIDDLE EAST & AFRICA: SWITCHGEAR MARKET, BY INSTALLATION, 2022-2025 (USD BILLION)
- TABLE 174 MIDDLE EAST & AFRICA: SWITCHGEAR MARKET, BY INSTALLATION, 2026-2031 (USD BILLION)
- TABLE 175 MIDDLE EAST & AFRICA: SWITCHGEAR MARKET, BY VOLTAGE, 2022-2025 (USD BILLION)
- TABLE 176 MIDDLE EAST & AFRICA: SWITCHGEAR MARKET, BY VOLTAGE, 2026-2031 (USD BILLION)
- TABLE 177 MIDDLE EAST & AFRICA: SWITCHGEAR MARKET, BY CURRENT, 2022-2025 (USD BILLION)
- TABLE 178 MIDDLE EAST & AFRICA: SWITCHGEAR MARKET, BY CURRENT, 2026-2031 (USD BILLION)
- TABLE 179 MIDDLE EAST & AFRICA: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 180 MIDDLE EAST & AFRICA: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 181 MIDDLE EAST & AFRICA: SWITCHGEAR MARKET, BY COUNTRY, 2022-2025 (USD BILLION)
- TABLE 182 MIDDLE EAST & AFRICA: SWITCHGEAR MARKET, BY COUNTRY, 2026-2031 (USD BILLION)
- TABLE 183 GCC COUNTRIES: SWITCHGEAR MARKET, BY COUNTRY, 2022-2025 (USD BILLION)
- TABLE 184 GCC COUNTRIES: SWITCHGEAR MARKET, BY COUNTRY, 2026-2031 (USD BILLION)
- TABLE 185 SAUDI ARABIA: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 186 SAUDI ARABIA: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 187 UAE: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 188 UAE: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 189 REST OF GCC COUNTRIES: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 190 REST OF GCC COUNTRIES: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 191 EGYPT: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 192 EGYPT: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 193 SOUTH AFRICA: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 194 SOUTH AFRICA: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 195 REST OF MIDDLE EAST & AFRICA: SWITCHGEAR MARKET, BY END USER, 2022-2025 (USD BILLION)
- TABLE 196 REST OF MIDDLE EAST & AFRICA: SWITCHGEAR MARKET, BY END USER, 2026-2031 (USD BILLION)
- TABLE 197 SWITCHGEAR MARKET: OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS, JANUARY 2023-AUGUST 2026
- TABLE 198 SWITCHGEAR MARKET: DEGREE OF COMPETITION, 2025
- TABLE 199 SWITCHGEAR MARKET: REGION FOOTPRINT
- TABLE 200 SWITCHGEAR MARKET: INSULATION TYPE FOOTPRINT
- TABLE 201 SWITCHGEAR MARKET: INSTALLATION FOOTPRINT
- TABLE 202 SWITCHGEAR MARKET: VOLTAGE FOOTPRINT
- TABLE 203 SWITCHGEAR MARKET: CURRENT FOOTPRINT
- TABLE 204 SWITCHGEAR MARKET: END-USER FOOTPRINT
- TABLE 205 SWITCHGEAR MARKET: DETAILED LIST OF KEY STARTUPS/SMES
- TABLE 206 SWITCHGEAR MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
- TABLE 207 SWITCHGEAR MARKET: PRODUCT LAUNCHES, JANUARY 2023-AUGUST 2026
- TABLE 208 SWITCHGEAR MARKET: DEALS, JANUARY 2023-AUGUST 2026
- TABLE 209 SWITCHGEAR MARKET: EXPANSIONS, JANUARY 2023-AUGUST 2026
- TABLE 210 SWITCHGEAR MARKET: OTHER DEVELOPMENTS, JANUARY 2023-AUGUST 2026
- TABLE 211 SCHNEIDER ELECTRIC: COMPANY OVERVIEW
- TABLE 212 SCHNEIDER ELECTRIC: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 213 SCHNEIDER ELECTRIC: PRODUCT LAUNCHES
- TABLE 214 SCHNEIDER ELECTRIC: DEALS
- TABLE 215 SCHNEIDER ELECTRIC: EXPANSIONS
- TABLE 216 SCHNEIDER ELECTRIC: OTHER DEVELOPMENTS
- TABLE 217 ABB: COMPANY OVERVIEW
- TABLE 218 ABB: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 219 ABB: PRODUCT LAUNCHES
- TABLE 220 ABB: DEALS
- TABLE 221 ABB: EXPANSIONS
- TABLE 222 ABB: OTHER DEVELOPMENTS
- TABLE 223 SIEMENS: COMPANY OVERVIEW
- TABLE 224 SIEMENS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 225 SIEMENS: PRODUCT LAUNCHES
- TABLE 226 SIEMENS: DEALS
- TABLE 227 SIEMENS: EXPANSIONS
- TABLE 228 SIEMENS: OTHER DEVELOPMENTS
- TABLE 229 GE VERNOVA: COMPANY OVERVIEW
- TABLE 230 GE VERNOVA: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 231 GE VERNOVA: PRODUCT LAUNCHES
- TABLE 232 GE VERNOVA: DEALS
- TABLE 233 GE VERNOVA: EXPANSIONS
- TABLE 234 GE VERNOVA: OTHER DEVELOPMENTS
- TABLE 235 EATON: COMPANY OVERVIEW
- TABLE 236 EATON: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 237 EATON: PRODUCT LAUNCHES
- TABLE 238 EATON: DEALS
- TABLE 239 EATON: EXPANSIONS
- TABLE 240 EATON: OTHER DEVELOPMENTS
- TABLE 241 HITACHI ENERGY LTD.: COMPANY OVERVIEW
- TABLE 242 HITACHI ENERGY LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 243 HITACHI ENERGY LTD.: OTHER DEVELOPMENTS
- TABLE 244 SIEMENS ENERGY: COMPANY OVERVIEW
- TABLE 245 SIEMENS ENERGY: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 246 SIEMENS ENERGY: DEALS
- TABLE 247 SIEMENS ENERGY: EXPANSIONS
- TABLE 248 SIEMENS ENERGY: OTHER DEVELOPMENTS
- TABLE 249 MITSUBISHI ELECTRIC CORPORATION: COMPANY OVERVIEW
- TABLE 250 MITSUBISHI ELECTRIC CORPORATION: PRODUCTS/SOLUTIONS/ SERVICES OFFERED
- TABLE 251 MITSUBISHI ELECTRIC CORPORATION: DEALS
- TABLE 252 MITSUBISHI ELECTRIC CORPORATION: EXPANSIONS
- TABLE 253 MITSUBISHI ELECTRIC CORPORATION: OTHER DEVELOPMENTS
- TABLE 254 FUJI ELECTRIC CO., LTD.: COMPANY OVERVIEW
- TABLE 255 FUJI ELECTRIC CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 256 FUJI ELECTRIC CO., LTD.: EXPANSIONS
- TABLE 257 FUJI ELECTRIC CO., LTD.: OTHER DEVELOPMENTS
- TABLE 258 HYOSUNG HEAVY INDUSTRIES: COMPANY OVERVIEW
- TABLE 259 HYOSUNG HEAVY INDUSTRIES: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 260 HYOSUNG HEAVY INDUSTRIES: OTHER DEVELOPMENTS
- TABLE 261 TOSHIBA CORPORATION: COMPANY OVERVIEW
- TABLE 262 TOSHIBA CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 263 TOSHIBA CORPORATION: EXPANSIONS
- TABLE 264 TOSHIBA CORPORATION: OTHER DEVELOPMENTS
- TABLE 265 HD HYUNDAI ELECTRIC CO., LTD.: COMPANY OVERVIEW
- TABLE 266 HD HYUNDAI ELECTRIC CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 267 HD HYUNDAI ELECTRIC CO., LTD.: OTHER DEVELOPMENTS
- TABLE 268 MEIDENSHA CORPORATION: COMPANY OVERVIEW
- TABLE 269 MEIDENSHA CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 270 MEIDENSHA CORPORATION: EXPANSIONS
- TABLE 271 CG POWER & INDUSTRIAL SOLUTIONS LTD.: COMPANY OVERVIEW
- TABLE 272 CG POWER & INDUSTRIAL SOLUTIONS LTD.: PRODUCTS/SOLUTIONS/ SERVICES OFFERED
- TABLE 273 CG POWER & INDUSTRIAL SOLUTIONS LTD.: EXPANSIONS
- TABLE 274 CG POWER & INDUSTRIAL SOLUTIONS LTD.: OTHER DEVELOPMENTS
- TABLE 275 LS ELECTRIC CO., LTD.: COMPANY OVERVIEW
- TABLE 276 LS ELECTRIC CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 277 LS ELECTRIC CO., LTD.: DEALS
- TABLE 278 LS ELECTRIC CO., LTD.: EXPANSIONS
- TABLE 279 LS ELECTRIC CO., LTD.: OTHER DEVELOPMENTS
- TABLE 280 NVENT ELECTRIC PLC: COMPANY OVERVIEW
- TABLE 281 NVENT ELECTRIC PLC: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 282 NVENT ELECTRIC PLC: DEALS
- TABLE 283 CHINT GROUP: COMPANY OVERVIEW
- TABLE 284 CHINT GROUP: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 285 WEG: COMPANY OVERVIEW
- TABLE 286 WEG: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 287 DOHO ELECTRIC: COMPANY OVERVIEW
- TABLE 288 DOHO ELECTRIC: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 289 LUCY ELECTRIC: COMPANY OVERVIEW
- TABLE 290 LUCY ELECTRIC: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 291 LUCY ELECTRIC: DEALS
- TABLE 292 TBEA CO., LTD.: COMPANY OVERVIEW
- TABLE 293 TBEA CO., LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
- TABLE 294 TBEA CO., LTD: DEALS
- TABLE 295 BHARAT HEAVY ELECTRICALS LIMITED: COMPANY OVERVIEW
- TABLE 296 CHINA XD ELECTRIC CO., LTD.: COMPANY OVERVIEW
- TABLE 297 TGOOD GLOBAL: COMPANY OVERVIEW
- TABLE 298 SIEYUAN ELECTRIC CO., LTD.: COMPANY OVERVIEW
- TABLE 299 ORMAZABAL: COMPANY OVERVIEW
- TABLE 300 S&C ELECTRIC COMPANY: COMPANY OVERVIEW
- TABLE 301 SGC SWITCHGEAR COMPANY: COMPANY OVERVIEW
- TABLE 302 MAJOR SECONDARY SOURCES
- TABLE 303 DATA CAPTURED FROM PRIMARY SOURCES
- TABLE 304 PRIMARY INTERVIEW PARTICIPANTS, BY COMPANY
- TABLE 305 SWITCHGEAR MARKET: RISK ANALYSIS
List of Figures
- FIGURE 1 SWITCHGEAR MARKET SEGMENTATION AND REGIONAL SCOPE
- FIGURE 2 SWITCHGEAR MARKET: DURATION CONSIDERED
- FIGURE 3 SWITCHGEAR MARKET SCENARIO
- FIGURE 4 GLOBAL SWITCHGEAR MARKET, 2022-2031
- FIGURE 5 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN SWITCHGEAR MARKET, 2023-2026
- FIGURE 6 DISRUPTIONS IMPACTING GROWTH OF SWITCHGEAR MARKET
- FIGURE 7 HIGH-GROWTH SEGMENTS IN SWITCHGEAR MARKET, 2026-2031
- FIGURE 8 ASIA PACIFIC TO EXHIBIT HIGHEST GROWTH RATE IN SWITCHGEAR MARKET DURING FORECAST PERIOD
- FIGURE 9 SF6 COMPLIANCE TIMELINES AND SURGING ELECTRIFICATION DEMAND ARE DRIVING GLOBAL SWITCHGEAR MARKET GROWTH
- FIGURE 10 ASIA PACIFIC TO WITNESS HIGHEST GROWTH FROM 2026 TO 2031
- FIGURE 11 INDOOR SEGMENT DOMINATED ASIA PACIFIC SWITCHGEAR MARKET IN 2025
- FIGURE 12 INDOOR SEGMENT TO CAPTURE LARGER MARKET SHARE IN 2031
- FIGURE 13 HIGH (ABOVE 36 KV) SEGMENT TO ACCOUNT FOR LARGEST MARKET SHARE IN 2031
- FIGURE 14 AIR-INSULATED SWITCHGEAR SEGMENT TO ACCOUNT FOR LARGEST MARKET SHARE IN 2031
- FIGURE 15 AC SEGMENT TO ACCOUNT FOR LARGER MARKET SHARE IN 2031
- FIGURE 16 POWER UTILITIES SEGMENT TO HOLD LARGEST MARKET SHARE IN 2031
- FIGURE 17 ASIA PACIFIC TO ACCOUNT FOR LARGEST MARKET SHARE IN 2031
- FIGURE 18 SWITCHGEAR MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 19 ELECTRICITY GENERATION, BY REGION, 2015-2025
- FIGURE 20 REGIONAL BREAKDOWN OF ELECTRICITY DEMAND, 2023-2025
- FIGURE 21 DATA CENTER ELECTRICITY CONSUMPTION, 2015-2025
- FIGURE 22 DATA CENTER POWER DEMAND, BY REGION, 2020-2025
- FIGURE 23 WORLD RENEWABLE ENERGY GENERATION, BY SOURCE, 2025
- FIGURE 24 GLOBAL INSTALLED WIND TURBINE CAPACITY, 2015-2025
- FIGURE 25 GLOBAL INVESTMENT IN ENERGY EFFICIENCY AND ELECTRIFICATION ACROSS BUILDINGS, INDUSTRY, AND TRANSPORTATION, 2016-2025
- FIGURE 26 AVERAGE COPPER AND ALUMINUM PRICE, 2023-2026 (USD/MT)
- FIGURE 27 GLOBAL ELECTRIC CAR SALES, 2020-2025
- FIGURE 28 NEW OFFSHORE WIND INSTALLATIONS, 2020-2025 (MW)
- FIGURE 29 GLOBAL ANNUAL INVESTMENT IN POWER SECTOR, 2016-2025
- FIGURE 30 PORTER'S FIVE FORCES ANALYSIS
- FIGURE 31 SWITCHGEAR MARKET: VALUE CHAIN ANALYSIS
- FIGURE 32 SWITCHGEAR MARKET ECOSYSTEM
- FIGURE 33 AVERAGE SELLING PRICE TREND OF SWITCHGEAR, BY REGION, 2022-2025
- FIGURE 34 IMPORT DATA FOR HS CODE 853720-COMPLIANT PRODUCTS FOR TOP FIVE COUNTRIES, 2021-2025
- FIGURE 35 EXPORT DATA FOR HS CODE 853720-COMPLIANT PRODUCTS FOR TOP FIVE COUNTRIES, 2021-2025
- FIGURE 36 IMPORT DATA FOR HS CODE 853521-COMPLIANT PRODUCTS FOR TOP FIVE COUNTRIES, 2021-2025
- FIGURE 37 EXPORT DATA FOR HS CODE 853521-COMPLIANT PRODUCTS FOR TOP FIVE COUNTRIES, 2021-2025
- FIGURE 38 IMPORT DATA FOR HS CODE 853529-COMPLIANT PRODUCTS FOR TOP FIVE COUNTRIES, 2021-2025
- FIGURE 39 EXPORT DATA FOR HS CODE 853529-COMPLIANT PRODUCTS FOR TOP FIVE COUNTRIES, 2021-2025
- FIGURE 40 TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS
- FIGURE 41 INVESTMENT AND FUNDING SCENARIO, 2024-2026
- FIGURE 42 PATENTS GRANTED AND APPLIED, 2017-2026
- FIGURE 43 FUTURE APPLICATIONS OF SWITCHGEAR
- FIGURE 44 SUCCESS STORIES AND REAL-WORLD APPLICATIONS OF SWITCHGEAR
- FIGURE 45 DECISION-MAKING FACTORS IN SWITCHGEAR MARKET
- FIGURE 46 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP THREE END USERS
- FIGURE 47 KEY BUYING CRITERIA FOR TOP THREE END USERS
- FIGURE 48 ADOPTION BARRIERS AND INTERNAL CHALLENGES IN SWITCHGEAR MARKET
- FIGURE 49 SWITCHGEAR MARKET SHARE, BY INSULATION TYPE, 2025
- FIGURE 50 SWITCHGEAR MARKET SHARE, BY INSTALLATION, 2025
- FIGURE 51 SWITCHGEAR MARKET SHARE, BY VOLTAGE, 2025
- FIGURE 52 SWITCHGEAR MARKET SHARE, BY CURRENT, 2025
- FIGURE 53 SWITCHGEAR MARKET SHARE, BY END USER, 2025
- FIGURE 54 ASIA PACIFIC TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 55 SWITCHGEAR MARKET SHARE, BY REGION, 2025
- FIGURE 56 ASIA PACIFIC: SWITCHGEAR MARKET SNAPSHOT
- FIGURE 57 EUROPE: SWITCHGEAR MARKET SNAPSHOT
- FIGURE 58 MARKET SHARE ANALYSIS OF COMPANIES OFFERING SWITCHGEAR, 2025
- FIGURE 59 SWITCHGEAR MARKET: SEGMENTAL REVENUE ANALYSIS OF TOP FIVE PLAYERS, 2021-2025
- FIGURE 60 SWITCHGEAR MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 61 SWITCHGEAR MARKET: COMPANY FOOTPRINT
- FIGURE 62 SWITCHGEAR MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 63 COMPANY VALUATION
- FIGURE 64 FINANCIAL METRICS (EV/EBITDA)
- FIGURE 65 BRAND COMPARISON OF KEY VENDORS
- FIGURE 66 SCHNEIDER ELECTRIC: COMPANY SNAPSHOT
- FIGURE 67 ABB: COMPANY SNAPSHOT
- FIGURE 68 SIEMENS: COMPANY SNAPSHOT
- FIGURE 69 GE VERNOVA: COMPANY SNAPSHOT
- FIGURE 70 EATON: COMPANY SNAPSHOT
- FIGURE 71 SIEMENS ENERGY: COMPANY SNAPSHOT
- FIGURE 72 MITSUBISHI ELECTRIC CORPORATION: COMPANY SNAPSHOT
- FIGURE 73 FUJI ELECTRIC CO., LTD.: COMPANY SNAPSHOT
- FIGURE 74 HYOSUNG HEAVY INDUSTRIES: COMPANY SNAPSHOT
- FIGURE 75 TOSHIBA CORPORATION: COMPANY SNAPSHOT
- FIGURE 76 HD HYUNDAI ELECTRIC CO., LTD.: COMPANY SNAPSHOT
- FIGURE 77 MEIDENSHA CORPORATION: COMPANY SNAPSHOT
- FIGURE 78 CG POWER & INDUSTRIAL SOLUTIONS LTD.: COMPANY SNAPSHOT
- FIGURE 79 LS ELECTRIC CO., LTD.: COMPANY SNAPSHOT
- FIGURE 80 NVENT ELECTRIC PLC: COMPANY SNAPSHOT
- FIGURE 81 WEG: COMPANY SNAPSHOT
- FIGURE 82 TBEA CO., LTD.: COMPANY SNAPSHOT
- FIGURE 83 SWITCHGEAR MARKET: RESEARCH DESIGN
- FIGURE 84 DATA CAPTURED FROM SECONDARY SOURCES
- FIGURE 85 CORE FINDINGS FROM INDUSTRY EXPERTS
- FIGURE 86 BREAKDOWN OF PRIMARY INTERVIEWS, BY COMPANY TYPE, DESIGNATION, AND REGION
- FIGURE 87 METRICS CONSIDERED FOR ANALYZING AND ASSESSING DEMAND FOR SWITCHGEAR
- FIGURE 88 MARKET SIZE ESTIMATION METHODOLOGY: BOTTOM-UP APPROACH
- FIGURE 89 MARKET SIZE ESTIMATION METHODOLOGY: TOP-DOWN APPROACH
- FIGURE 90 KEY STEPS CONSIDERED FOR ASSESSING SUPPLY OF SWITCHGEAR
- FIGURE 91 SWITCHGEAR MARKET: SUPPLY-SIDE ANALYSIS
- FIGURE 92 SWITCHGEAR MARKET: DATA TRIANGULATION
- FIGURE 93 SWITCHGEAR MARKET: FACTOR ANALYSIS
- FIGURE 94 SWITCHGEAR MARKET: RESEARCH ASSUMPTIONS AND LIMITATIONS
- FIGURE 95 SWITCHGEAR MARKET: INSIGHTS FROM INDUSTRY EXPERTS

