PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2132649
PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2132649
Dental Service Organization Market by Service Type (Human Resources, Marketing and Branding, Accounting, Medical Supplies Procurement, and Other Services), by End User (Oral Surgeons, Endodontists, and Other Dental Specialists) - Global Forecast to 2031
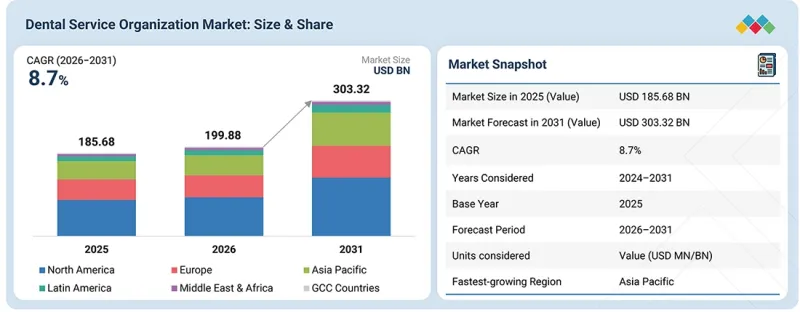
The dental service organization market is projected to reach USD 303.32 billion by 2031 from USD 199.88 billion in 2026, at a CAGR of 8.7% during the forecast period.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | By service type, end user, and region |
| Regions covered | North America, Europe, Asia Pacific, Latin America, Middle East & Africa (GCC Countries, Rest of Middle East & Africa) |
The global dental service organization market is largely driven by the growing affiliation of dentists with dental service organizations, rising administrative complexity, and staffing challenges across independent dental practices. Increasing demand for dental care, rising dental care expenditures, and the expansion of the addressable dental care market have significantly increased the need for efficient practice management and centralized business support services. Dental service organizations provide a broad range of non-clinical services, including human resources, marketing and branding, accounting, medical supplies procurement, and administrative support, enabling affiliated dentists to reduce operational burdens and focus on patient care.
Advancements in dental technology and the growing adoption of digital dentistry, artificial intelligence, cloud-based practice management systems, electronic health records, and digital imaging have further strengthened the role of dental service organizations in improving practice efficiency. These technologies enable dental service organizations to standardize administrative processes, enhance patient engagement, optimize scheduling and billing, and improve coordination among affiliated dental practices. Furthermore, the growing need for centralized procurement and economies of scale has encouraged dental practices to affiliate with dental service organizations to reduce operating costs and improve resource utilization.
Additionally, raising dentists' awareness of the benefits of affiliation, including access to administrative expertise, workforce management, technology infrastructure, marketing support, and negotiated procurement arrangements, has positively influenced market growth. The expansion of dental practice networks, the consolidation of the fragmented dental services industry, and growing investments in dental practices have further supported the adoption of dental service organization models. The combination of rising demand for dental care, increasing operational challenges, technological advancements, and the growing need for efficient practice management is driving the global expansion of the dental service organization market.
"By service type, human resources held the largest market share in the global dental service organization market in 2025".
This dominance stems from the rising staffing challenges faced by dental practices and the growing need for centralized workforce management. Human resource services provided by dental service organizations include recruitment, employee onboarding, payroll and benefits administration, workforce planning, training, and employee retention, enabling affiliated dental practices to manage their workforce efficiently while reducing administrative burdens. The growing affiliation of dentists with dental service organizations has further accelerated demand for centralized human resource services. As dental service organizations expand their networks through practice affiliations and acquisitions, the need to recruit, manage, and retain dentists, dental hygienists, dental assistants, and administrative staff across multiple locations has increased. Additionally, growing competition for qualified dental professionals and rising labor costs have encouraged dental practices to leverage the workforce management capabilities of dental service organizations. These factors, combined with the increasing administrative complexity of dental practices and the need to improve operational efficiency, have contributed to the leading position of the Human Resources segment in the global dental service organization market.
"By end user, oral surgeons held the largest share in the global dental service organization market in 2025"
The dominance of this segment is largely due to the high resource requirements of oral and maxillofacial practices, including specialized personnel, surgical facilities, equipment, and patient coordination. These practices often handle referrals for advanced dental and facial procedures, which increase operational and administrative demands. DSOs can address these needs through centralized purchasing, staffing, financial management, scheduling, and technology support. The ability to consolidate these functions across affiliated practices makes the DSO model particularly attractive to oral and maxillofacial practices.
"The US is expected to grow at the highest CAGR in the North American dental service organization market during the forecast period."
The US is expected to post the highest CAGR in the North American dental service organization market over the forecast period. This growth is driven by several key factors, including the increasing affiliation of dentists with dental service organizations, rising administrative complexity, and growing staffing challenges across dental practices. The country's large, highly developed dental care market, rising dental care expenditures, and the strong presence of established dental service organizations further support market expansion. Additionally, the growing consolidation of independent dental practices and the increasing adoption of centralized practice management, human resources, marketing, accounting, and procurement services are accelerating demand for dental service organization models across the US. Furthermore, the growing use of digital dentistry, artificial intelligence, cloud-based practice management systems, and other technology-enabled solutions is improving operational efficiency and supporting the expansion of dental service organization networks. The growing need among dentists to reduce administrative workloads, access centralized business support, achieve economies of scale, and address workforce shortages is driving increased affiliation with dental service organizations. Collectively, these factors position the US as the leading and fastest-growing market for dental service organizations in North America.
A breakdown of the primary participants (on the supply side) in the dental service organization market referenced in this report is provided below:
- By Company Type: Tier 1 (35%), Tier 2 (40%), and Tier 3 (25%)
- By Designation: C-level Executives (45%), Directors (35%), and Others (20%)
- By Region: North America (27%), Europe (25%), Asia Pacific (30%), Latin America (8%), and the Middle East & Africa (10%)
The leading players in the global dental service organization market include Heartland Dental (US), The Aspen Group - TAG (US), Q and M Dental Group (Singapore), and PDS Health (US).
Research Coverage:
The report analyzes the dental service organization market, estimating its size and future growth potential across segments by service type, end user, and region. Additionally, the report features a competitive analysis of key players in the market, including their company profiles, product offerings, recent developments, and key market strategies.
Reasons to Buy the Report
The report provides valuable insights for both market leaders and new entrants in the dental service organization market, offering the most accurate revenue estimates. It helps stakeholders understand the competitive landscape, enabling them to better position their businesses and develop effective go-to-market strategies. Additionally, the report highlights key market drivers, restraints, challenges, and opportunities, giving stakeholders a comprehensive understanding of current market trends.
This report provides insights into the following pointers:
- Analysis of key drivers (increasing affiliation of dentists with dental service organizations, rising administrative complexity and staffing challenges in dental practices, growing dental care expenditure and expansion of the addressable dental care market), restraints (regulatory restrictions and state-level variations in DSO ownership, concerns regarding clinical autonomy and dentist control), opportunities (impact of DSOs on dental industry, Increasing Adoption of AI and digital technologies creates opportunities for centralized DSO platforms), and challenges (maintaining profitability amid rising labor costs, reimbursement pressure, and practice-level margin compression)
- Market Penetration: It includes extensive information on the products offered by the major players in the global dental service organization market. The report covers segments such as service type, end user, and region.
- Product Enhancement/Innovation: Comprehensive details about new product launches and anticipated trends in the global dental service organization market
- Market Development: Thorough knowledge and analysis of the profitable rising markets by service type, end user, and region
- Market Diversification: Comprehensive information about newly launched products, expanding markets, current advancements, and investments in the global dental service organization market.
- Competitive Assessment: A comprehensive assessment of market shares, growth strategies, product offerings, and capabilities of key competitors in the global dental service organization market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.4 YEARS CONSIDERED
- 1.5 CURRENCY CONSIDERED
- 1.6 KEY STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND DEVELOPMENTS
- 2.2 DISRUPTIVE TRENDS SHAPING MARKET
- 2.3 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.4 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN DENTAL SERVICE ORGANIZATION MARKET
- 3.2 ASIA PACIFIC: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE AND COUNTRY
- 3.3 DENTAL SERVICE ORGANIZATION MARKET: GEOGRAPHIC GROWTH OPPORTUNITIES
- 3.4 REGIONAL MIX: DENTAL SERVICE ORGANIZATION MARKET (2024-2031)
- 3.5 DENTAL SERVICE ORGANIZATION MARKET: DEVELOPED VS. DEVELOPING MARKETS
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Increasing affiliation of dentists with dental service organizations
- 4.2.1.2 Rising administrative complexity and staffing challenges in dental practices
- 4.2.1.3 Growing dental care expenditure and expansion of addressable dental care market
- 4.2.2 RESTRAINTS
- 4.2.2.1 Regulatory restrictions and state-level variations in DSO ownership
- 4.2.2.2 Concerns regarding clinical autonomy and dentist control
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Impact of DSOs on dental industry
- 4.2.3.2 Increasing adoption of AI and digital technologies creates opportunities for centralized DSO platforms
- 4.2.4 CHALLENGES
- 4.2.4.1 Maintaining profitability amid rising labor costs, reimbursement pressure, and practice-level margin compression
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER- 1/2/3 PLAYERS
5 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 5.1 KEY EMERGING TECHNOLOGIES
- 5.1.1 ARTIFICIAL INTELLIGENCE (AI)-ENABLED PRACTICE MANAGEMENT & PREDICTIVE ANALYTICS
- 5.1.2 AI-ENABLED REVENUE CYCLE & ADMINISTRATIVE AUTOMATION
- 5.2 COMPLEMENTARY TECHNOLOGIES
- 5.2.1 DIGITAL IMAGING & INTRAORAL SCANNING TECHNOLOGIES
- 5.3 ADJACENT TECHNOLOGIES
- 5.3.1 3D PRINTING & DIGITAL MANUFACTURING TECHNOLOGIES
- 5.3.2 TELEDENTISTRY & REMOTE PATIENT MONITORING
- 5.4 TECHNOLOGY/PRODUCT ROADMAP
- 5.4.1 SHORT-TERM | RECENT TECHNOLOGIES | FOUNDATION & EARLY COMMERCIALIZATION
- 5.4.2 MID-TERM (2027-2030) | EXPANSION & STANDARDIZATION
- 5.4.3 LONG-TERM (2030-2035+) | MASS COMMERCIALIZATION & DISRUPTION
- 5.5 PATENT ANALYSIS
- 5.5.1 PATENT PUBLICATION TRENDS FOR DENTAL SERVICE ORGANIZATION
- 5.5.2 INSIGHTS: JURISDICTION AND TOP APPLICANT ANALYSIS
- 5.6 IMPACT OF AI/GEN AI ON DENTAL SERVICE ORGANIZATION MARKET
- 5.6.1 TOP USE CASES AND MARKET POTENTIAL
- 5.6.2 INTERCONNECTED ADJACENT ECOSYSTEMS AND IMPACT ON MARKET PLAYERS
- 5.6.3 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN DENTAL SERVICE ORGANIZATION MARKET
- 5.7 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
- 5.7.1 HEARTLAND DENTAL: AI-ENABLED CLINICAL WORKFLOW
- 5.7.2 DENTAL CARE ALLIANCE: STANDARDIZED DIGITAL PREVENTIVE CARE WORKFLOW
- 5.7.3 PDS HEALTH: SCALED DIGITAL DENTISTRY & SAME-DAY RESTORATIVE WORKFLOW
6 REGULATORY LANDSCAPE
- 6.1 REGIONAL REGULATIONS AND COMPLIANCE
- 6.1.1 US
- 6.1.2 EUROPEAN UNION
- 6.1.3 CHINA
- 6.1.4 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 6.2 SUSTAINABILITY INITIATIVES
- 6.2.1 ENVIRONMENTAL SUSTAINABILITY IN DENTAL SERVICE ORGANIZATIONS
- 6.2.2 DIGITAL-EFFICIENT DSO INFRASTRUCTURE
- 6.2.3 CIRCULAR ECONOMY AND SUSTAINABLE PROCUREMENT IN DSO OPERATIONS
- 6.2.4 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
7 INDUSTRY TRENDS
- 7.1 PORTER'S FIVE FORCES ANALYSIS
- 7.1.1 THREAT FROM NEW ENTRANTS
- 7.1.2 THREAT FROM SUBSTITUTES
- 7.1.3 BARGAINING POWER OF SUPPLIERS
- 7.1.4 BARGAINING POWER OF BUYERS
- 7.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 7.2 MACROECONOMIC OUTLOOK
- 7.2.1 INTRODUCTION
- 7.2.2 GDP TRENDS AND FORECAST
- 7.2.3 TRENDS IN DENTAL SERVICE ORGANIZATION MARKET
- 7.3 VALUE CHAIN ANALYSIS
- 7.4 ECOSYSTEM ANALYSIS
- 7.5 SUPPLY CHAIN ANALYSIS
- 7.6 PRICING ANALYSIS
- 7.6.1 AVERAGE SYSTEM COST - DENTAL SERVICE ORGANIZATION (DSO)
- 7.6.2 AVERAGE COST RANGE OF DENTAL SERVICE ORGANIZATION (DSO), BY REGION, 2023-2025 (USD)
- 7.6.3 AVERAGE SELLING PRICE OF DENTAL SERVICE ORGANIZATION, BY KEY PLAYERS, 2023-2025
- 7.7 KEY CONFERENCES & EVENTS, 2026-2027
- 7.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 7.9 INVESTMENT & FUNDING SCENARIO
- 7.10 CASE STUDY ANALYSIS
- 7.11 IMPACT OF 2025 US TARIFF - OVERVIEW
- 7.11.1 INTRODUCTION
- 7.11.2 KEY TARIFF RATES
- 7.11.3 PRICE IMPACT ANALYSIS
- 7.11.4 IMPACT ON REGION
- 7.11.4.1 US
- 7.11.4.2 Europe
- 7.11.4.3 Asia Pacific
- 7.11.5 IMPACT ON END-USE INDUSTRIES
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.2.1 INFLUENCE OF KEY STAKEHOLDERS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
9 DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE
- 9.1 INTRODUCTION
- 9.2 HUMAN RESOURCES
- 9.2.1 RISING DENTAL WORKFORCE REQUIREMENTS STRENGTHENING DEMAND FOR CENTRALIZED HUMAN RESOURCE SERVICES
- 9.3 MARKETING & BRANDING
- 9.3.1 GROWING DENTAL SERVICE SPENDING AND INCREASING COMPETITION STRENGTHENING DEMAND
- 9.4 ACCOUNTING
- 9.4.1 INCREASING FINANCIAL COMPLEXITY ACROSS DENTAL PRACTICES FUELING DEMAND FOR CENTRALIZED ACCOUNTING SERVICES
- 9.5 MEDICAL SUPPLIES PROCUREMENT
- 9.5.1 CENTRALIZED PROCUREMENT AND GROWING DENTAL SERVICE ACTIVITY STRENGTHENING DEMAND
- 9.6 OTHERS
- 9.6.1 INCREASING DIGITALIZATION AND WORKFORCE DEVELOPMENT TO SUPPORT MARKET GROWTH
- 9.7 DSO SCALE DRIVEN BY BOTH PRACTICE FOOTPRINT AND DENTIST NETWORK DEPTH
10 DENTAL SERVICE ORGANIZATION MARKET, BY END USER
- 10.1 INTRODUCTION
- 10.2 ORAL SURGEONS
- 10.2.1 GROWING DEMAND FOR COMPLEX DENTAL PROCEDURES STRENGTHENS ORAL SURGEONS' AFFILIATION WITH DSOS
- 10.3 ENDODONTISTS
- 10.3.1 RISING DEMAND FOR SPECIALIZED ROOT CANAL CARE SUPPORTING MARKET GROWTH
- 10.4 OTHER DENTAL SPECIALISTS
- 10.4.1 GROWING DEMAND FOR SPECIALIZED DENTAL CARE INCREASING DSO AFFILIATION ACROSS KEY DENTAL SPECIALTIES
11 DENTAL SERVICE ORGANIZATION MARKET, BY REGION
- 11.1 INTRODUCTION
- 11.2 EUROPE
- 11.2.1 GERMANY
- 11.2.1.1 Expanding dental practice scale and rising operating costs creating opportunities for DSO Expansion
- 11.2.2 ITALY
- 11.2.2.1 Large private dental provider base and growing healthcare expenditure to support market growth
- 11.2.3 SPAIN
- 11.2.3.1 Large private dental workforce and high out-of-pocket dental spending create opportunities for market players
- 11.2.4 FRANCE
- 11.2.4.1 High dental care spending and established private practice base to propel market growth
- 11.2.5 UK
- 11.2.5.1 Large dental workforce and rising healthcare expenditure to support growth
- 11.2.6 REST OF EUROPE
- 11.2.1 GERMANY
- 11.3 NORTH AMERICA
- 11.3.1 US
- 11.3.1.1 Dentist affiliation, workforce challenges, and rising dental spending to drive market
- 11.3.2 CANADA
- 11.3.2.1 Expanding dental coverage to drive market growth
- 11.3.1 US
- 11.4 ASIA PACIFIC
- 11.4.1 SOUTH KOREA
- 11.4.1.1 Rising dental care demand to support market growth
- 11.4.2 JAPAN
- 11.4.2.1 Rising dental care needs and workforce pressures to support market growth
- 11.4.3 CHINA
- 11.4.3.1 Expanding dental care access to propel market growth
- 11.4.4 INDIA
- 11.4.4.1 Expanding dental care access to support market expansion
- 11.4.5 AUSTRALIA
- 11.4.5.1 Rising dental care demand to drive market growth
- 11.4.6 REST OF ASIA PACIFIC
- 11.4.1 SOUTH KOREA
- 11.5 LATIN AMERICA
- 11.5.1 BRAZIL
- 11.5.1.1 Expanding oral healthcare infrastructure to favor market growth
- 11.5.2 MEXICO
- 11.5.2.1 Expanding oral healthcare access to fuel market
- 11.5.3 REST OF LATIN AMERICA
- 11.5.1 BRAZIL
- 11.6 MIDDLE EAST & AFRICA
- 11.6.1 RISING HEALTHCARE INVESTMENTS TO AID MARKET GROWTH
- 11.7 GCC COUNTRIES
- 11.7.1 PRIVATE HEALTHCARE EXPANSION TO SUPPORT MARKET GROWTH
12 COMPETITIVE LANDSCAPE
- 12.1 INTRODUCTION
- 12.2 KEY PLAYERS' STRATEGIES/RIGHT TO WIN
- 12.3 DENTAL SERVICE ORGANIZATION MARKET SHARE ANALYSIS, BY NUMBER OF PRACTICES
- 12.4 BRAND/PRODUCT COMPARISON
- 12.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 12.5.1 STARS
- 12.5.2 EMERGING LEADERS
- 12.5.3 PERVASIVE PLAYERS
- 12.5.4 PARTICIPANTS
- 12.5.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 12.5.5.1 Company footprint
- 12.5.5.2 Region footprint
- 12.5.5.3 Service type footprint
- 12.5.5.4 End user footprint
- 12.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES (2025)
- 12.6.1 PROGRESSIVE COMPANIES
- 12.6.2 RESPONSIVE COMPANIES
- 12.6.3 DYNAMIC COMPANIES
- 12.6.4 STARTING BLOCKS
- 12.6.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 12.6.5.1 Detailed list of key startups/SMEs
- 12.6.5.2 Dental service organization market: Competitive benchmarking of key startups/SMEs
- 12.7 COMPETITIVE SCENARIO
- 12.7.1 SERVICE LAUNCHES AND APPROVALS
- 12.7.2 DEALS
- 12.7.3 EXPANSIONS
13 COMPANY PROFILES
- 13.1 KEY PLAYERS
- 13.1.1 HEARTLAND DENTAL
- 13.1.1.1 Business overview
- 13.1.1.2 Services offered
- 13.1.1.3 Recent developments
- 13.1.1.3.1 Product launches & approvals
- 13.1.1.3.2 Deals
- 13.1.1.3.3 Expansions
- 13.1.1.4 MnM view
- 13.1.1.4.1 Right to win
- 13.1.1.4.2 Strategic choices
- 13.1.1.4.3 Weaknesses and competitive threats
- 13.1.2 THE ASPEN GROUP - TAG
- 13.1.2.1 Business overview
- 13.1.2.2 Services offered
- 13.1.2.3 Recent developments
- 13.1.2.3.1 Service launches & approvals
- 13.1.2.3.2 Deals
- 13.1.2.3.3 Expansions
- 13.1.2.4 MnM view
- 13.1.2.4.1 Right to win
- 13.1.2.4.2 Strategic choices
- 13.1.2.4.3 Weaknesses and competitive threats
- 13.1.3 PDS HEALTH
- 13.1.3.1 Business overview
- 13.1.3.2 Services offered
- 13.1.3.3 Recent developments
- 13.1.3.3.1 Product launches & approvals
- 13.1.3.3.2 Deals
- 13.1.3.3.3 Expansions
- 13.1.3.4 MnM view
- 13.1.3.4.1 Right to win
- 13.1.3.4.2 Strategic choices
- 13.1.3.4.3 Weaknesses and competitive threats
- 13.1.4 MB2 DENTAL
- 13.1.4.1 Business overview
- 13.1.4.2 Services offered
- 13.1.4.3 Recent developments
- 13.1.4.3.1 Service launches & approvals
- 13.1.4.3.2 Deals
- 13.1.4.4 MnM view
- 13.1.4.4.1 Right to win
- 13.1.4.4.2 Strategic choices
- 13.1.4.4.3 Weaknesses and competitive threats
- 13.1.5 SMILE BRANDS INC.
- 13.1.5.1 Business overview
- 13.1.5.2 Services offered
- 13.1.5.3 Recent developments
- 13.1.5.3.1 Deals
- 13.1.5.4 MnM view
- 13.1.5.4.1 Right to win
- 13.1.5.4.2 Strategic choices
- 13.1.5.4.3 Weaknesses and competitive threats
- 13.1.6 Q & M DENTAL GROUP
- 13.1.6.1 Business overview
- 13.1.6.2 Services offered
- 13.1.6.3 Recent developments
- 13.1.6.3.1 Service launches & approvals
- 13.1.6.3.2 Deals
- 13.1.7 COLOSSEUM DENTAL GROUP
- 13.1.7.1 Business overview
- 13.1.7.2 Products offered
- 13.1.7.3 Recent developments
- 13.1.7.3.1 Deals
- 13.1.8 AFFORDABLE CARE
- 13.1.8.1 Business overview
- 13.1.8.2 Services offered
- 13.1.8.3 Recent developments
- 13.1.8.3.1 Expansions
- 13.1.9 DENTAL CARE ALLIANCE
- 13.1.9.1 Business overview
- 13.1.9.2 Services offered
- 13.1.9.3 Recent developments
- 13.1.9.3.1 Service launches & approvals
- 13.1.9.3.2 Deals
- 13.1.9.3.3 Expansions
- 13.1.10 SGA DENTAL PARTNERS
- 13.1.10.1 Business overview
- 13.1.10.2 Services offered
- 13.1.10.3 Recent developments
- 13.1.10.3.1 Deals
- 13.1.1 HEARTLAND DENTAL
- 13.2 OTHER PLAYERS
- 13.2.1 NORTH AMERICAN DENTAL GROUP
- 13.2.2 SPECIALTY DENTAL BRANDS
- 13.2.3 U.S. ORAL SURGERY MANAGEMENT
- 13.2.4 SPECIALTY1 PARTNERS
- 13.2.5 D4C DENTAL BRANDS
- 13.2.6 GREAT EXPRESSIONS DENTAL CENTERS
- 13.2.7 SONRAVA HEALTH
- 13.2.8 SAGE DENTAL
- 13.2.9 MORTENSON DENTAL PARTNERS
- 13.2.10 DENTAL365/PREMIER CARE DENTAL MANAGEMENT
- 13.2.11 GUARDIAN DENTISTRY PARTNERS
- 13.2.12 PEPPERPOINTE PARTNERSHIPS
- 13.2.13 42 NORTH DENTAL
- 13.2.14 ROCK DENTAL BRANDS
- 13.2.15 BENEVIS
14 RESEARCH METHODOLOGY
- 14.1 RESEARCH APPROACH
- 14.1.1 SECONDARY DATA
- 14.1.1.1 Key data from secondary sources
- 14.1.2 PRIMARY DATA
- 14.1.2.1 Key data from primary sources
- 14.1.2.2 Key industry insights
- 14.1.1 SECONDARY DATA
- 14.2 MARKET SIZE ESTIMATION
- 14.3 MARKET BREAKDOWN AND DATA TRIANGULATION
- 14.4 MARKET SHARE ESTIMATION
- 14.5 ASSUMPTIONS
- 14.6 LIMITATIONS
- 14.6.1 METHODOLOGY-RELATED LIMITATIONS
- 14.6.2 SCOPE-RELATED LIMITATIONS
- 14.7 RISK ASSESSMENT
15 APPENDIX
- 15.1 DISCUSSION GUIDE
- 15.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 15.3 CUSTOMIZATION OPTIONS
- 15.4 RELATED REPORTS
- 15.5 AUTHOR DETAILS
List of Tables
- TABLE 1 STANDARD CURRENCY CONVERSION RATES, 2021-2024
- TABLE 2 LIST OF SOME RECENT DEALS BACKED BY PRIVATE EQUITY IN US, 2021-2023
- TABLE 3 DENTAL SERVICE ORGANIZATION MARKET: UNMET NEEDS
- TABLE 4 INTERCONNECTED MARKETS
- TABLE 5 STRATEGIC MOVES BY TIER- 1/2/3 PLAYERS
- TABLE 6 LIST OF PATENTS IN DENTAL SERVICE ORGANIZATION (2022-2025)
- TABLE 7 TOP USE CASES AND MARKET POTENTIAL
- TABLE 8 INTERCONNECTED ADJACENT ECOSYSTEMS AND IMPACT ON MARKET PLAYERS
- TABLE 9 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 10 EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 11 ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 12 LATIN AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 13 MIDDLE EAST & AFRICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 14 DENTAL SERVICE ORGANIZATION MARKET: IMPACT OF PORTER'S FIVE FORCES
- TABLE 15 GDP PERCENTAGE CHANGE, BY KEY COUNTRIES, 2021-2030
- TABLE 16 DENTAL SERVICE ORGANIZATION MARKET: ROLE OF COMPANIES IN ECOSYSTEM
- TABLE 17 DENTAL SERVICE ORGANIZATION MARKET: KEY CONFERENCES & EVENTS (2026-2027)
- TABLE 18 CASE STUDY 1: AI-ENABLED DENTAL DIAGNOSTICS IMPROVES PRACTICE WORKFLOW
- TABLE 19 CASE STUDY 2: SCALED DIGITAL DENTISTRY IMPROVES TREATMENT CONVENIENCE
- TABLE 20 CASE STUDY 3: STANDARDIZED TECHNOLOGY DEPLOYMENT IMPROVES PATIENT & CLINICIAN EXPERIENCE
- TABLE 21 US ADJUSTED RECIPROCAL TARIFF RATES
- TABLE 22 KEY PRODUCT-RELATED TARIFFS EFFECTIVE ON DENTAL PRODUCTS
- TABLE 23 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR DENTAL SERVICE ORGANIZATION
- TABLE 24 KEY BUYING CRITERIA FOR TOP TWO END USERS
- TABLE 25 DENTAL SERVICE ORGANIZATION MARKET: UNMET NEEDS/END USER EXPECTATIONS
- TABLE 26 DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 27 DENTAL SERVICE ORGANIZATION MARKET FOR HUMAN RESOURCES, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 28 DENTAL SERVICE ORGANIZATION MARKET FOR MARKETING & BRANDING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 29 DENTAL SERVICE ORGANIZATION MARKET FOR ACCOUNTING, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 30 DENTAL SERVICE ORGANIZATION MARKET FOR MEDICAL SUPPLIES PROCUREMENT, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 31 DENTAL SERVICE ORGANIZATION MARKET FOR OTHERS SEGMENT, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 32 DSO PRACTICE FOOTPRINT VS. DENTIST NETWORK
- TABLE 33 DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 34 DENTAL SERVICE ORGANIZATION MARKET FOR ORAL SURGEONS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 35 DENTAL SERVICE ORGANIZATION MARKET FOR ENDODONTISTS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 36 DENTAL SERVICE ORGANIZATION MARKET FOR OTHER DENTAL SPECIALISTS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 37 DENTAL SERVICE ORGANIZATION MARKET, BY REGION, 2024-2031 (USD MILLION)
- TABLE 38 EUROPE: DENTAL SERVICE ORGANIZATION MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 39 EUROPE: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE, 2024-2031 (USD MILLION)
- TABLE 40 EUROPE: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 41 GERMANY: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 42 GERMANY: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 43 ITALY: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 44 ITALY: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 45 SPAIN: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 46 SPAIN: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 47 FRANCE: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 48 FRANCE: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 49 UK: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 50 UK: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 51 REST OF EUROPE: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 52 REST OF EUROPE: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 53 NORTH AMERICA: DENTAL SERVICE ORGANIZATION MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 54 NORTH AMERICA: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 55 NORTH AMERICA: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 56 US: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 57 US: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 58 CANADA: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 59 CANADA: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 60 ASIA PACIFIC: DENTAL SERVICE ORGANIZATION MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 61 ASIA PACIFIC: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 62 ASIA PACIFIC: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 63 SOUTH KOREA: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 64 SOUTH KOREA: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 65 JAPAN: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 66 JAPAN: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 67 CHINA: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 68 CHINA: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 69 INDIA: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 70 INDIA: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 71 AUSTRALIA: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 72 AUSTRALIA: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 73 REST OF ASIA PACIFIC: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 74 REST OF ASIA PACIFIC: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 75 LATIN AMERICA: DENTAL SERVICE ORGANIZATION MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 76 LATIN AMERICA: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 77 LATIN AMERICA: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 78 BRAZIL: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 79 BRAZIL: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 80 MEXICO: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 81 MEXICO: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 82 REST OF LATIN AMERICA: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 83 REST OF LATIN AMERICA: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 84 MIDDLE EAST & AFRICA: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 85 MIDDLE EAST & AFRICA: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 86 GCC COUNTRIES: DENTAL SERVICE ORGANIZATION MARKET, BY SERVICE TYPE, 2024-2031 (USD MILLION)
- TABLE 87 GCC COUNTRIES: DENTAL SERVICE ORGANIZATION MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 88 OVERVIEW OF STRATEGIES DEPLOYED BY KEY PLAYERS IN DENTAL SERVICE ORGANIZATION MARKET, JANUARY 2022-JULY 2026
- TABLE 89 DENTAL SERVICE ORGANIZATION MARKET: REGION FOOTPRINT
- TABLE 90 DENTAL SERVICE ORGANIZATION MARKET: SERVICE TYPE FOOTPRINT
- TABLE 91 DENTAL SERVICE ORGANIZATION MARKET: END USER FOOTPRINT
- TABLE 92 DENTAL SERVICE ORGANIZATION MARKET: DETAILED LIST OF KEY STARTUPS/SMES
- TABLE 93 DENTAL SERVICE ORGANIZATION MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
- TABLE 94 DENTAL SERVICE ORGANIZATION MARKET: SERVICE LAUNCHES, JANUARY 2022-JULY 2026
- TABLE 95 DENTAL SERVICE ORGANIZATION MARKET: DEALS, JANUARY 2022-JULY 2026
- TABLE 96 DENTAL SERVICE ORGANIZATION MARKET: EXPANSIONS, JANUARY 2022-JULY 2026
- TABLE 97 HEARTLAND DENTAL: COMPANY OVERVIEW
- TABLE 98 HEARTLAND DENTAL: SERVICE OFFERED
- TABLE 99 HEARTLAND DENTAL: PRODUCT LAUNCHES & APPROVALS, JANUARY 2022-JULY 2026
- TABLE 100 HEARTLAND DENTAL: DEALS, JANUARY 2022-JULY 2026
- TABLE 101 HEARTLAND DENTAL: EXPANSIONS, JANUARY 2022-JULY 2026
- TABLE 102 THE ASPEN GROUP - TAG: COMPANY OVERVIEW
- TABLE 103 THE ASPEN GROUP: SERVICE OFFERED
- TABLE 104 THE ASPEN GROUP: SERVICE LAUNCHES & APPROVALS, JANUARY 2022-JULY 2026
- TABLE 105 THE ASPEN GROUP: DEALS, JANUARY 2022-JULY 2026
- TABLE 106 THE ASPEN GROUP: EXPANSIONS, JANUARY 2022-JULY 2026
- TABLE 107 PDS HEALTH: COMPANY OVERVIEW
- TABLE 108 PDS HEALTH: SERVICE OFFERED
- TABLE 109 PDS HEALTH: SERVICE LAUNCHES & APPROVALS, JANUARY 2022-JULY 2026
- TABLE 110 PDS HEALTH: DEALS, JANUARY 2022-JULY 2026
- TABLE 111 PDS HEALTH: EXPANSIONS, JANUARY 2022-JULY 2026
- TABLE 112 MB2 DENTAL: COMPANY OVERVIEW
- TABLE 113 MB2 DENTAL: SERVICES OFFERED
- TABLE 114 MB2 DENTAL: SERVICE LAUNCHES & APPROVALS, JANUARY 2022-JULY 2026
- TABLE 115 MB2 DENTAL: DEALS, JANUARY 2022-JULY 2026
- TABLE 116 SMILE BRANDS, INC.: COMPANY OVERVIEW
- TABLE 117 SMILE BRANDS, INC.: SERVICE OFFERED
- TABLE 118 SMILE BRANDS, INC.: DEALS, JANUARY 2022-JULY 2026
- TABLE 119 Q AND M DENTAL GROUP: COMPANY OVERVIEW
- TABLE 120 Q & M DENTAL GROUP: SERVICE OFFERED
- TABLE 121 Q & M DENTAL GROUP: SERVICE LAUNCHES & APPROVALS, JANUARY 2022-JULY 2026
- TABLE 122 Q & M DENTAL GROUP: DEALS, JANUARY 2022-JULY 2026
- TABLE 123 COLOSSEUM DENTAL GROUP: COMPANY OVERVIEW
- TABLE 124 COLOSSEUM DENTAL GROUP: SERVICE OFFERED
- TABLE 125 COLOSSEUM DENTAL GROUP: DEALS, JANUARY 2021-JULY 2026
- TABLE 126 AFFORDABLE CARE: COMPANY OVERVIEW
- TABLE 127 AFFORDABLE CARE: SERVICE OFFERED
- TABLE 128 AFFORDABLE CARE: EXPANSIONS, JANUARY 2022-JULY 2026
- TABLE 129 DENTAL CARE ALLIANCE: COMPANY OVERVIEW
- TABLE 130 DENTAL CARE ALLIANCE: SERVICE OFFERED
- TABLE 131 DENTAL CARE ALLIANCE: SERVICE LAUNCHES & APPROVALS, JANUARY 2022-JULY 2026
- TABLE 132 DENTAL CARE ALLIANCE: DEALS, JANUARY 2022-JULY 2026
- TABLE 133 DENTAL CARE ALLIANCE: EXPANSIONS, JANUARY 2022-JULY 2026
- TABLE 134 SGA DENTAL PARTNERS: COMPANY OVERVIEW
- TABLE 135 SGA DENTAL PARTNERS: SERVICE OFFERED
- TABLE 136 SGA DENTAL PARTNERS: DEALS, JANUARY 2022-JULY 2026
- TABLE 137 RISK ASSESSMENT: DENTAL SERVICE ORGANISATIONS MARKET
List of Figures
- FIGURE 1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- FIGURE 2 DENTAL SERVICE ORGANIZATION MARKET, 2024-2031
- FIGURE 3 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN DENTAL SERVICE ORGANIZATIONS MARKET
- FIGURE 4 DISRUPTIVE TRENDS IMPACTING GROWTH OF DENTAL SERVICE ORGANIZATION MARKET
- FIGURE 5 HIGH-GROWTH SEGMENTS AND EMERGING FRONTIERS IN DENTAL SERVICE ORGANIZATIONS MARKET, 2025
- FIGURE 6 ASIA PACIFIC TO REGISTER HIGHEST GROWTH DURING FORECAST PERIOD
- FIGURE 7 DSO AFFILIATION AND DENTAL PRACTICE CONSOLIDATION DRIVING MARKET GROWTH
- FIGURE 8 JAPAN ACCOUNTED FOR LARGEST SHARE OF ASIA PACIFIC MARKET IN 2025
- FIGURE 9 INDIA TO REGISTER HIGHEST GROWTH RATE DURING FORECAST PERIOD
- FIGURE 10 NORTH AMERICA TO DOMINATE DENTAL SERVICE ORGANIZATION MARKET DURING FORECAST PERIOD
- FIGURE 11 DEVELOPING MARKETS TO REGISTER HIGHER GROWTH RATES DURING FORECAST PERIOD
- FIGURE 12 DENTAL SERVICE ORGANIZATION MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 13 GLOBAL PATENT PUBLICATION TRENDS (JANUARY 2015-MARCH 2026)
- FIGURE 14 TOP APPLICANTS & OWNERS (COMPANIES/INSTITUTIONS) OF DENTAL SERVICE ORGANIZATION PATENTS (JANUARY 2015-DECEMBER 2025)
- FIGURE 15 TOP APPLICANTS OF DENTAL SERVICE ORGANIZATION, BY COUNTRY/REGION (2015-2025)
- FIGURE 16 DENTAL SERVICE ORGANIZATION MARKET: PORTER'S FIVE FORCES ANALYSIS
- FIGURE 17 DENTAL SERVICE ORGANIZATION MARKET: VALUE CHAIN ANALYSIS
- FIGURE 18 DENTAL SERVICE ORGANIZATION MARKET: ECOSYSTEM ANALYSIS
- FIGURE 19 DENTAL SERVICE ORGANIZATION MARKET: SUPPLY CHAIN ANALYSIS
- FIGURE 20 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- FIGURE 21 INVESTMENT/VENTURE CAPITAL SCENARIO IN DENTAL SERVICE ORGANIZATION MARKET, 2021-2025
- FIGURE 22 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR TOP END USERS
- FIGURE 23 KEY BUYING CRITERIA FOR TOP TWO END USERS
- FIGURE 24 INDIA TO REGISTER HIGHEST GROWTH IN DENTAL SERVICE ORGANIZATION MARKET DURING FORECAST PERIOD
- FIGURE 25 NORTH AMERICA: DENTAL SERVICE ORGANIZATION MARKET SNAPSHOT
- FIGURE 26 ASIA PACIFIC: DENTAL SERVICE ORGANIZATION MARKET SNAPSHOT
- FIGURE 27 MARKET SHARE ANALYSIS OF DENTAL SERVICE ORGANIZATION, BY NUMBER OF PRACTICES (2025)
- FIGURE 28 DENTAL SERVICE ORGANIZATION MARKET: BRAND/PRODUCT COMPARISON
- FIGURE 29 DENTAL SERVICE ORGANIZATION MARKET: COMPANY EVALUATION MATRIX, KEY PLAYERS (2025)
- FIGURE 30 DENTAL SERVICE ORGANIZATION MARKET: COMPANY FOOTPRINT
- FIGURE 31 DENTAL SERVICE ORGANIZATION MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 32 Q & M DENTAL GROUP: COMPANY SNAPSHOT (2025)
- FIGURE 33 DENTAL SERVICE ORGANIZATION MARKET: RESEARCH DESIGN
- FIGURE 34 LIST OF PRIMARY SOURCES
- FIGURE 35 BREAKDOWN OF PRIMARY INTERVIEWS: SUPPLY-SIDE AND DEMAND-SIDE PARTICIPANTS
- FIGURE 36 BREAKDOWN OF PRIMARY INTERVIEWS (SUPPLY-SIDE): BY COMPANY TYPE, DESIGNATION, AND REGION
- FIGURE 37 BREAKDOWN OF PRIMARY INTERVIEWS (DEMAND-SIDE): BY END USER, DESIGNATION, AND REGION
- FIGURE 38 MARKET SIZE ESTIMATION: REVENUE SHARE ANALYSIS
- FIGURE 39 REVENUE SHARE ANALYSIS ILLUSTRATION: HEARTLAND DENTAL (2025)
- FIGURE 40 CAGR PROJECTIONS FROM DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES ANALYSIS (2026-2031)
- FIGURE 41 CAGR PROJECTIONS: SUPPLY-SIDE ANALYSIS
- FIGURE 42 DENTAL SERVICE ORGANIZATION MARKET: DATA TRIANGULATION

