PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125663

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125663
Dental Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the dental services market size is expected to grow from USD 654.13 billion in 2025 to USD 681.46 billion in 2026 and is forecast to reach USD 852.84 billion by 2031 at 4.59% CAGR over 2026-2031.
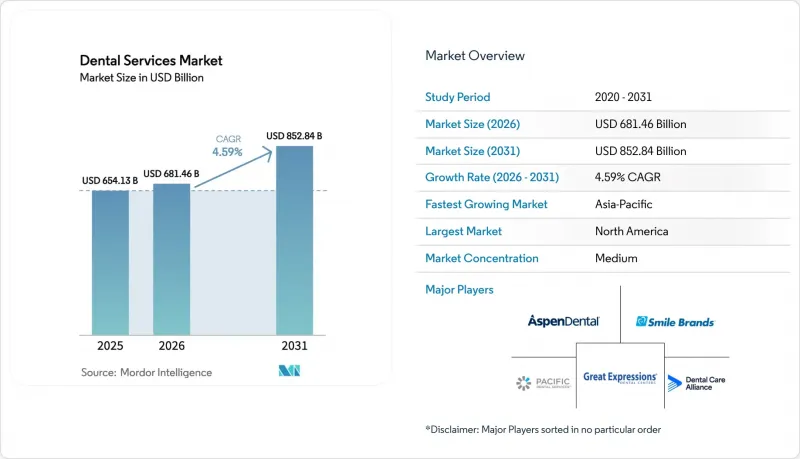
This report is Segmented by Service Type (Non-Surgical Services: Preventive, Restorative, Cosmetic; Surgical Services: Implants & Oral Surgery, and More), Patient Age Group (Upto 17, Above 17 To Upto 60, Above 60), End-User (Dental Clinics, Hospitals, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Dental Services Market Trends and Insights
Aging Population & Tooth-Loss Burden
Global life-expectancy gains are enlarging the pool of patients over 65, a cohort with elevated rates of periodontal disease and edentulism. In Japan, 25% of seniors lacked natural teeth in 2024, spurring steady demand for full-arch restorations. Singapore's health ministry reported that 60% of residents aged 60-74 had fewer than 20 natural teeth, prompting expanded implant reimbursement. Manufacturers gained U.S. FDA clearance for new zirconia implants formulated for patients with metal allergies in 2024, widening clinical options. Practices integrating geriatric sedation protocols and mini-implant systems are therefore positioned to capture premium restorative revenue.
Growing Demand for Cosmetic & Aesthetic Dentistry
Social-media exposure and ubiquitous video calls heighten patients' focus on smile aesthetics, driving double-digit growth in veneers, bonding, and chairside whitening. The teeth-whitening segment alone generated USD 6.2 billion in 2025 as consumers sought rapid, non-invasive upgrades. Align Technology disclosed that 45% of 2025 clear-aligner starts involved adults over 30, underscoring broadening acceptance of discreet orthodontics. Regulators increasingly police marketing claims; the U.K. General Dental Council mandated evidence-based before-and-after imagery in 2024. Clinics equipped with digital smile-design software and transparent consent protocols are gaining competitive traction.
Workforce Shortages & Hygienist Burnout
The U.S. faced 16,400 vacant hygienist positions in 2025, a 9% shortfall that forces practices to cap appointment slots. Burnout stems from repetitive-motion injuries and aerosol exposure, with 42% of surveyed hygienists planning to cut hours within five years. The U.K. recorded a 38% three-year attrition rate among dental nurses in 2024. Australia projects a deficit of 2,100 hygienists by 2030 unless training capacity or immigration increases. Wage inflation, U.S. hygienist pay averaged USD 42.50 per hour in 2024, squeezing smaller practices lacking DSO-level purchasing power. DSOs with in-house academies and career-ladder programs retain staff more effectively.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Dental Insurance Coverage & DSOs
- Growing Adoption of Digital Dentistry
- High Out-of-Pocket Costs in Emerging Economies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Surgical care accounted for 58.92% of 2025 revenue, as implants, orthodontics, and oral surgery command premium fees, while non-surgical segments are slated for a 7.06% CAGR to 2031. Implant costs in North America average USD 3,000-6,000 each, propelled by demand from an aging yet increasingly active population. Clear-aligner uptake continued to swell; 1.8 million of Align Technology's 4 million 2025 global starts involved adults over 21, reflecting expanded remote-monitoring capabilities. Endodontic and periodontal specialists retain pricing power amid limited provider supply, with urban U.S. root canals priced at USD 1,200-1,800 per tooth.
Preventive dentistry is carving out faster growth. State-mandated sealant programs under Medicaid's EPSDT benefits lowered caries incidence by 60% in school-age children, encouraging broader payer adoption. Cosmetic demand remains resilient; 71% of elective veneer and whitening patients used third-party financing in 2024, enabling practices to capture higher discretionary spend. Same-day CAD/CAM crowns reduce lab turnaround time from 2 weeks to 2 hours, improving acceptance rates by about 18%. Consistent FDA oversight of new restorative materials sustains patient and payer confidence.
Complete Report Scope:
- By Service Type
- Non-surgical Services
- Preventive Dentistry
- Restorative Dentistry
- Cosmetic Dentistry
- Surgical Services
- Implants & Oral Surgery
- Orthodontics
- Endodontics & Periodontics
- Non-surgical Services
- By Patient Age Group
- Upto 17
- Above 17 to Upto 60
- Above 60
- By End-User
- Dental Clinics
- Hospitals
- Dental Service Organisations (DSOs)
- Academic & Research Institutes
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained 39.28% of global revenue in 2025 on the strength of USD 385 per-capita spending and 77% insurance coverage among non-elderly adults. Canadian provinces earmarked CAD 1.2 billion to extend adult dental subsidies, while cross-border flows saw 1.2 million U.S. residents travel to Mexico for lower-cost care.
Europe contends with tighter product rules under the EU Medical Device Regulation, which trimmed the CE-marked implant roster by 12% by 2024. Germany's subsidy for implant-supported crowns cut co-pays by EUR 200-300, adding 9% implant volume. NHS-access challenges pushed 12 million U.K. adults toward private practices, where a single crown costs GBP 800-1,200.
Asia-Pacific is poised for a 10.27% CAGR, led by China and India. China approved 34 homegrown digital devices in 2024, cutting scanner acquisition costs by 25%. India welcomed 500,000 dental tourists in 2024, generating USD 320 million as clinics marketed ISO-certified facilities at deep discounts. The GCC reached a clinic density of 1 per 2,800 residents by 2024, driven by expatriate demand in Dubai.
- Abano Healthcare
- Align Technology (Invisalign)
- Apollo White Dental
- Aspen Dental Management, Inc.
- Bupa Dental Care
- Coast Dental
- Dental Care Alliance
- Great Expressions Dental Centers
- Heartland Dental
- Henry Schein One DSOs
- InterDent
- MB2 Dental Solutions
- MyDentist (IDH Group)
- Pacific Dental Services
- Q & M Dental Group
- Smile Brands Inc.
- SmileDirectClub
- Western Dental Services
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Aging Population & Tooth-Loss Burden
- 4.2.2 Growing Demand for Cosmetic & Aesthetic Dentistry
- 4.2.3 Expansion of Dental Insurance Coverage & DSOS
- 4.2.4 Growing Adoption of Digital Dentistry
- 4.2.5 Subscription-Based Preventive Wellness Plans
- 4.2.6 AI-Driven Chairside Decision Support & Triage
- 4.3 Market Restraints
- 4.3.1 Workforce Shortages & Hygienist Burnout
- 4.3.2 High Out-of-Pocket Costs in Emerging Economies
- 4.3.3 Rising Cyber-Risk & Insurance Premiums for Clinics
- 4.3.4 Volatility In Dental-Materials Supply Chains
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Service Type
- 5.1.1 Non-surgical Services
- 5.1.1.1 Preventive Dentistry
- 5.1.1.2 Restorative Dentistry
- 5.1.1.3 Cosmetic Dentistry
- 5.1.2 Surgical Services
- 5.1.2.1 Implants & Oral Surgery
- 5.1.2.2 Orthodontics
- 5.1.2.3 Endodontics & Periodontics
- 5.1.1 Non-surgical Services
- 5.2 By Patient Age Group
- 5.2.1 Upto 17
- 5.2.2 Above 17 to Upto 60
- 5.2.3 Above 60
- 5.3 By End-User
- 5.3.1 Dental Clinics
- 5.3.2 Hospitals
- 5.3.3 Dental Service Organisations (DSOs)
- 5.3.4 Academic & Research Institutes
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 Abano Healthcare
- 6.3.2 Align Technology (Invisalign)
- 6.3.3 Apollo White Dental
- 6.3.4 Aspen Dental Management, Inc.
- 6.3.5 Bupa Dental Care
- 6.3.6 Coast Dental
- 6.3.7 Dental Care Alliance
- 6.3.8 Great Expressions Dental Centers
- 6.3.9 Heartland Dental
- 6.3.10 Henry Schein One DSOs
- 6.3.11 InterDent
- 6.3.12 MB2 Dental Solutions
- 6.3.13 MyDentist (IDH Group)
- 6.3.14 Pacific Dental Services
- 6.3.15 Q & M Dental Group
- 6.3.16 Smile Brands Inc.
- 6.3.17 SmileDirectClub
- 6.3.18 Western Dental Services
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

