PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2132652
PUBLISHER: MarketsandMarkets | PRODUCT CODE: 2132652
Dental Sutures Market by Type (Absorbable, Non-absorbable), Material (Synthetic (Polyglactin 910, PGA, PTFE, Nylon), Natural), Filament Type (Monofilament, Multifilament), & End User (Dental Clinics, Hospitals & ASCs) - Global Forecast to 2031
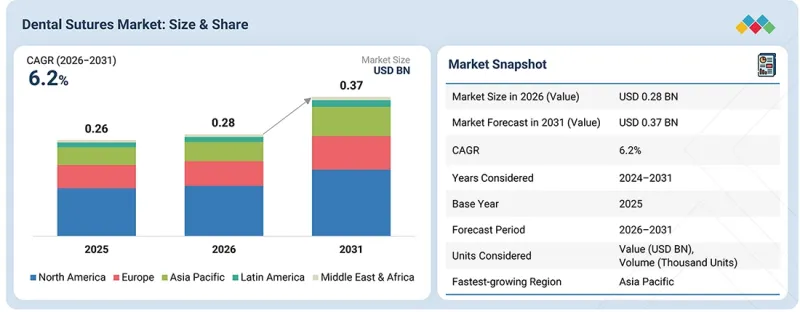
The global dental sutures market size is projected to reach USD 0.37 billion by 2031 from USD 0.28 billion in 2026, at a CAGR of 6.2%.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | By Type, Material, Filament type, End User, and Region |
| Regions covered | North America, Europe, APAC, LATAM, MEA |
Lifestyle-related factors, including poor oral hygiene, tobacco consumption, unhealthy dietary habits, and the growing prevalence of diabetes, together with an aging population, are contributing to a higher burden of periodontal diseases, tooth loss, and other oral conditions that often require surgical intervention. Consequently, the increasing number of dental procedures, including tooth extractions, periodontal surgeries, dental implant placement, bone grafting, and other oral and maxillofacial procedures, is driving the demand for dental sutures for effective wound closure and post-operative healing. The dental sutures market is further supported by the rising adoption of dental implants, increasing awareness regarding oral healthcare, growth in dental tourism, and improving access to dental treatment in emerging economies. In addition, technological advancements such as synthetic absorbable sutures, monofilament materials, antibacterial coatings, and atraumatic needle-suture combinations are improving handling, reducing tissue reaction, and supporting better clinical outcomes, thereby encouraging their adoption across dental clinics and oral surgery centers.
"The Non-absorbable dental sutures segment accounted for the largest share of the dental sutures market, by type, in 2025."
By type, the dental sutures market is categorized into absorbable and non-absorbable dental sutures. Non-absorbable dental sutures held the largest share of the market in 2025, primarily due to the greater control they provide over the duration of wound support in oral surgical procedures. Their ability to maintain tensile strength until clinical removal makes them particularly suitable for implant surgery, periodontal flap procedures, ridge augmentation, and bone grafting, where wound stabilization is critical during the initial healing period. In addition, non-absorbable sutures allow dental professionals to assess the surgical site at the time of suture removal, which can support post-operative wound monitoring. The continued preference for commonly used materials such as silk, nylon, polypropylene, and PTFE further contributes to their strong position in dental and maxillofacial procedures.
"The synthetic dental sutures segment accounted for the largest market share, by material, in 2025."
By material, the dental sutures market is divided into synthetic and natural dental sutures. Synthetic dental sutures accounted for the largest market share in 2025, supported by their controlled manufacturing characteristics, lower variability, and availability across a broad range of absorbable and non-absorbable formulations. Compared to natural materials, synthetic sutures can offer more predictable tensile-strength retention, controlled degradation characteristics, and reduced tissue reactivity, which are important considerations in procedures involving sensitive oral tissues. Materials such as PGA, polyglycolide 910, PDO, polypropylene, nylon, and PTFE are increasingly utilized across periodontal, implant, regenerative, and oral surgical procedures. The growing preference for advanced monofilament and synthetic absorbable sutures among dental surgeons is also strengthening the adoption of this segment.
"North America accounted for the largest market share, by region, in 2025."
Geographically, the dental sutures market is segmented into North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. North America accounted for the largest market share in 2025, driven by a comparatively high volume of dental implant, periodontal, extraction, and reconstructive oral procedures. The region has a large base of dentists and dental specialists, strong adoption of advanced surgical techniques, and widespread access to premium suture materials used in implantology and periodontal surgery. The increasing elderly population also supports demand, the continuing burden of periodontal disease and tooth loss, and the growing use of dental implants as a restorative treatment option. In addition, the presence of established dental product manufacturers, well-developed distribution networks, and strong adoption of technologically advanced dental consumables continues to support the position of North America in the global dental sutures market.
The break-up of the profile of primary participants in the dental sutures market:
- By Company Type: Tier 1 - 40%, Tier 2 - 30%, and Tier 3 - 30%
- By Designation: C-level Executives - 27%, Directors - 18%, and Others - 55%
- By Region: North America - 51%, Europe - 21%, Asia Pacific - 18%, Latin America - 6%, and Middle East & Africa - 4%
The major players operating in the dental sutures market include Johnson & Johnson (US), B. Braun SE (Germany), Advanced Medical Solutions Group plc (UK), DemeTECH Corporation (US), Hu-Friedy Mfg. Co., LLC (US), Envista (US), Corza Medical (US), SMI AG (Belgium), Henry Schein (US), Futura Surgicare Pvt. Ltd. (India), MANI, INC. (Japan), Young Innovations, Inc. (US), Assut Europe (Italy), KATSAN Katgut Sanayi ve Tic. A.S. (Turkey), Dogsan TIbbi Malzeme Sanayi A.S. (Turkey), HYGITECH (France), ZimVie Inc. (US), MEDIPAC SA (Greece), Lux Sutures (France), Bentley Healthcare Pvt. Ltd. (India), Boz Medical (Turkey), Golnit (Ukraine), GDT Dental Implants (Israel), DSI LTD (Israel), and Qubix Medicare Private Limited (India).
Research Coverage
This report studies the dental sutures Market based on types, filament types, materials, end users, and regions. The report also analyzes factors (such as drivers, restraints, opportunities and challenges) affecting market growth. It evaluates the opportunities and challenges in the market for stakeholders and provides details of the competitive landscape for market leaders. The report also studies micro markets concerning their growth trends, prospects, and contributions to the total dental sutures Market. The report forecasts the revenue of the market segments in five major regions.
Reasons to Buy the Report
The report will help the market leaders/new entrants in this market with information on the closest approximations of the revenue numbers for the overall dental sutures market and the subsegments. This report will help stakeholders understand the competitive landscape and gain more insights to position their businesses better and plan suitable go-to-market strategies. The report also helps stakeholders understand the pulse of the market and provides them with information on key market drivers, restraints, challenges, and opportunities.
This report provides insights into the following pointers:
- Analysis of key drivers (Increasing patient pool for dental treatments, Rising demand for advanced cosmetic dental procedures, Expanding dental care infrastructure and specialist practices), restraints (Need for post-operative removal and follow-up for non-absorbable sutures, Pricing pressure and commoditization of conventional dental sutures), challenges (Dearth of trained dental practitioners), and opportunities (Continued expansion of dental service organizations, Rising dental tourism activity) contributing to the growth of the dental sutures market.
- Product Development/Innovation: Detailed insights on upcoming trends, research & development activities, in the dental sutures market
- Market Development: Comprehensive information on the lucrative emerging markets by types, filament types, materials, end users and region
- Market Diversification: Exhaustive information about the growing geographies, recent developments, and investments in the dental sutures market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, product offerings, company evaluation quadrant, and capabilities of leading players in the global dental sutures market
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED & REGIONAL SCOPE
- 1.3.2 INCLUSIONS & EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.4 CURRENCY
- 1.5 STAKEHOLDERS
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS & MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: INSIGHTS & DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING MARKET GROWTH
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 DENTAL SUTURES MARKET OVERVIEW
- 3.2 DENTAL SUTURES MARKET, BY REGION, 2026 VS. 2031 (USD MILLION)
- 3.3 ASIA PACIFIC: DENTAL SUTURES MARKET, BY END USER AND COUNTRY, 2025 (USD MILLION)
- 3.4 GEOGRAPHIC SNAPSHOT OF DENTAL SUTURES MARKET
- 3.5 DENTAL SUTURES MARKET: EMERGING VS. DEVELOPED MARKETS
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Increasing patient pool for dental treatments
- 4.2.1.1.1 Geriatric population and edentulism
- 4.2.1.1.2 Periodontal diseases
- 4.2.1.1.3 Changing lifestyles and unhealthy food habits
- 4.2.1.2 Increasing adoption of periodontal plastic surgery and soft-tissue grafting procedures
- 4.2.1.3 Expanding dental care infrastructure and specialist practices
- 4.2.1.1 Increasing patient pool for dental treatments
- 4.2.2 RESTRAINTS
- 4.2.2.1 Need for post-operative removal and follow-up for non-absorbable sutures
- 4.2.2.2 Pricing pressure and commoditization of conventional dental sutures
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Continued growth of dental service organizations
- 4.2.3.2 Growing focus on emerging economies and rising disposable income levels
- 4.2.4 CHALLENGES
- 4.2.4.1 Shortage and uneven distribution of skilled dental professionals
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS & WHITE SPACES
- 4.3.1 UNMET NEEDS IN DENTAL SUTURES MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS & CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 INTENSITY OF COMPETITIVE RIVALRY
- 5.1.3 BARGAINING POWER OF BUYERS
- 5.1.4 BARGAINING POWER OF SUPPLIERS
- 5.1.5 THREAT OF SUBSTITUTES
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS & FORECAST
- 5.2.3 TRENDS IN SURGICAL SUTURES INDUSTRY
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE OF DENTAL SUTURE PRODUCTS, BY KEY PLAYER, 2025
- 5.5.2 AVERAGE SELLING PRICE TREND OF NON-ABSORBABLE DENTAL SUTURES, BY REGION, 2023-2025
- 5.6 TRADE ANALYSIS
- 5.6.1 IMPORT DATA FOR DENTAL SUTURES (HS CODE: 300610), 2021-2025
- 5.6.2 EXPORT DATA FOR DENTAL SUTURES (HS CODE: 300610), 2021-2025
- 5.7 KEY CONFERENCES & EVENTS, 2026-2027
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- 5.9 CASE STUDY ANALYSIS
- 5.9.1 CASE STUDY 1: STRATAFIX KNOTLESS BARBED PDS SUTURE REDUCES INTRAORAL CLOSURE TIME IN MAXILLOFACIAL SURGERY
- 5.9.2 CASE STUDY 2: B. BRAUN DAFILON(R) DEMONSTRATES SAFE AND EFFECTIVE MUCOSAL CLOSURE IN ROUTINE ORAL SURGERY.
- 5.9.3 CASE STUDY 3: SMI DACLON SHOWS LOWER BACTERIAL COLONIZATION AND MILDER TISSUE REACTION IN THIRD-MOLAR SURGERY
- 5.10 IMPACT OF 2025 US TARIFFS ON DENTAL SUTURES MARKET
- 5.10.1 INTRODUCTION
- 5.10.2 KEY TARIFF RATES
- 5.10.3 PRICE IMPACT ANALYSIS
- 5.10.4 IMPACT ON COUNTRIES/REGIONS
- 5.10.4.1 US
- 5.10.4.2 Europe
- 5.10.4.3 Asia Pacific
- 5.10.5 IMPACT ON END-USE INDUSTRIES
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, AND INNOVATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 ANTIMICROBIAL & BIOACTIVE COATING TECHNOLOGIES
- 6.3 TECHNOLOGY/PRODUCT ROADMAP
- 6.3.1 SHORT-TERM (2025-2027) | FOUNDATION & EARLY COMMERCIALIZATION
- 6.3.2 MID-TERM (2027-2030) | EXPANSION & STANDARDIZATION
- 6.3.3 LONG-TERM (2030-2035+) | MASS COMMERCIALIZATION & DISRUPTION
- 6.4 PATENT ANALYSIS
- 6.4.1 PATENT PUBLICATION TRENDS FOR DENTAL SUTURES MARKET
- 6.4.2 TOP APPLICANTS (COMPANIES) OF DENTAL SUTURE PATENTS
- 6.4.3 JURISDICTION ANALYSIS: TOP APPLICANTS (COUNTRIES) FOR PATENTS IN DENTAL SUTURES MARKET
- 6.5 IMPACT OF AI/GEN AI ON DENTAL SUTURES MARKET
- 6.5.1 TOP USE CASES & MARKET POTENTIAL
- 6.5.2 INTERCONNECTED ADJACENT ECOSYSTEMS & IMPACT ON MARKET PLAYERS
- 6.6 SUCCESS STORIES & REAL-WORLD APPLICATIONS
- 6.6.1 ENVISTA/OSTEOGENICS: CYTOPLAST PTFE SUTURES - DENTAL-SPECIFIC MONOFILAMENT CLOSURE FOR BONE GRAFTING AND IMPLANT SURGERY
- 6.6.2 JOHNSON & JOHNSON MEDTECH/ETHICON: VICRYL RAPIDE - FAST-ABSORBING CLOSURE IN ORAL AND IMPLANT SURGERY
- 6.6.3 HUFRIEDYGROUP: PERMA SHARP SUTURES - DENTAL-SPECIFIC NEEDLE-SUTURE CONFIGURATIONS FOR PRECISE SOFT-TISSUE CLOSURE
7 REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS & COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.1.2.1 North America
- 7.1.2.1.1 US
- 7.1.2.1.2 Canada
- 7.1.2.2 Europe
- 7.1.2.3 Asia Pacific
- 7.1.2.3.1 China
- 7.1.2.3.2 Japan
- 7.1.2.4 Latin America
- 7.1.2.4.1 Brazil
- 7.1.2.4.2 Mexico
- 7.1.2.5 Middle East
- 7.1.2.6 Africa
- 7.1.2.1 North America
- 7.2 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
- 7.2.1 CERTIFICATIONS, LABELING, AND ECO-STANDARDS IN DENTAL SUTURES MARKET
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 BUYER STAKEHOLDERS & BUYING EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 KEY BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS
- 8.5 MARKET PROFITABILITY
- 8.5.1 REVENUE POTENTIAL
- 8.5.2 COST DYNAMICS
- 8.5.3 MARGIN OPPORTUNITIES IN KEY APPLICATIONS
9 DENTAL SUTURES MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 ABSORBABLE DENTAL SUTURES
- 9.2.1 ELIMINATION OF POSTOPERATIVE SUTURE REMOVAL TO SUPPORT MARKET GROWTH
- 9.3 NON-ABSORBABLE DENTAL SUTURES
- 9.3.1 GROWING ADOPTION OF NON-ABSORBABLE SUTURES IN IMPLANT AND PERIODONTAL PROCEDURES TO DRIVE GROWTH
10 DENTAL SUTURES MARKET, BY MATERIAL
- 10.1 INTRODUCTION
- 10.2 SYNTHETIC DENTAL SUTURES
- 10.2.1 POLYGLACTIN 910 DENTAL SUTURES
- 10.2.1.1 Excellent handling characteristics and knot security of polyglactin 910 dental sutures to support adoption
- 10.2.2 POLYGLYCOLIC ACID (PGA) DENTAL SUTURES
- 10.2.2.1 Suitability of polyglycolic acid (PGA) dental sutures for broad range of routine and advanced dental procedures to fuel growth
- 10.2.3 POLYTETRAFLUOROETHYLENE (PTFE) DENTAL SUTURES
- 10.2.3.1 Advantages such as low bacterial retention and prolonged wound-support characteristics to drive demand for PTFE dental sutures
- 10.2.4 NYLON (POLYAMIDE) DENTAL SUTURES
- 10.2.4.1 High tensile strength and smooth tissue passage of nylon to drive demand in procedures requiring precise tissue approximation
- 10.2.5 OTHER SYNTHETIC DENTAL SUTURES
- 10.2.1 POLYGLACTIN 910 DENTAL SUTURES
- 10.3 NATURAL DENTAL SUTURES
- 10.3.1 SILK DENTAL SUTURES
- 10.3.1.1 Favorable handling characteristics, clinician familiarity, and broad availability to continue to drive demand for silk dental sutures
- 10.3.2 PLAIN GUT DENTAL SUTURES
- 10.3.2.1 Wide usage of plain gut sutures in oral mucosal closure and other short-healing procedures to support growth
- 10.3.3 CHROMIC GUT DENTAL SUTURES
- 10.3.3.1 Growing use of chromic gut dental sutures in tooth extractions and implant procedures to drive growth
- 10.3.1 SILK DENTAL SUTURES
11 DENTAL SUTURES MARKET, BY FILAMENT TYPE
- 11.1 INTRODUCTION
- 11.2 MONOFILAMENT DENTAL SUTURES
- 11.2.1 LOW CAPILLARITY AND BACTERIAL RETENTION TO DRIVE ADOPTION OF MONOFILAMENT DENTAL SUTURES
- 11.3 MULTIFILAMENT DENTAL SUTURES
- 11.3.1 FLEXIBILITY AND EASE OF HANDLING TO DRIVE USE OF MULTIFILAMENT DENTAL SUTURES
12 DENTAL SUTURES MARKET, BY APPLICATION
- 12.1 INTRODUCTION
- 12.2 ORAL SURGERY & TOOTH EXTRACTION
- 12.2.1 HIGH VOLUME OF TOOTH EXTRACTIONS PERFORMED FOR DENTAL CARIES AND OTHER DENTAL CONDITIONS TO BOOST MARKET
- 12.3 PERIODONTAL SURGERY
- 12.3.1 GROWING CLINICAL EMPHASIS ON ESTHETIC PERIODONTAL TREATMENT TO SUPPORT GROWTH
- 12.4 DENTAL IMPLANTOLOGY
- 12.4.1 GROWTH IN IMPLANT-SUPPORTED DENTAL REHABILITATION TO SUPPORT DEMAND FOR DENTAL SUTURES IN THIS APPLICATION
- 12.5 MAXILLOFACIAL SURGERY
- 12.5.1 GROWTH IN CORRECTIVE MAXILLOFACIAL PROCEDURES TO SUSTAIN DEMAND FOR SPECIALIZED SUTURES
- 12.6 OTHER APPLICATIONS
13 DENTAL SUTURES MARKET, BY END USER
- 13.1 INTRODUCTION
- 13.2 DENTAL CLINICS & SPECIALTY DENTAL CENTERS
- 13.2.1 INCREASING VOLUME OF TOOTH EXTRACTIONS, PERIODONTAL SURGERIES, AND OTHER OUTPATIENT DENTAL PROCEDURES TO DRIVE SUTURE UTILIZATION
- 13.3 HOSPITALS & AMBULATORY SURGICAL CENTERS
- 13.3.1 RISING NUMBER OF COMPLEX ORAL AND MAXILLOFACIAL SURGERIES AND HOSPITAL-BASED DENTAL PROCEDURES TO DRIVE DEMAND
- 13.4 ACADEMIC & RESEARCH INSTITUTIONS
- 13.4.1 GROWING DENTAL EDUCATION, SURGICAL TRAINING, AND RESEARCH ACTIVITIES TO SUPPORT DEMAND
14 DENTAL SUTURES MARKET, BY REGION
- 14.1 INTRODUCTION
- 14.2 EUROPE
- 14.2.1 MACROECONOMIC OUTLOOK FOR EUROPE
- 14.2.2 GERMANY
- 14.2.2.1 Favorable government policies for reimbursement to drive demand for dental sutures
- 14.2.3 UK
- 14.2.3.1 High dental procedure volumes and oral disease burden to drive market
- 14.2.4 FRANCE
- 14.2.4.1 Large dental workforce and extensive health-insurance coverage to support demand for dental surgical procedures and associated sutures
- 14.2.5 SPAIN
- 14.2.5.1 Presence of well-established dental healthcare infrastructure to propel market
- 14.2.6 ITALY
- 14.2.6.1 Predominantly private dental-care financing to support procedural base for dental sutures
- 14.2.7 REST OF EUROPE
- 14.3 NORTH AMERICA
- 14.3.1 MACROECONOMIC OUTLOOK FOR NORTH AMERICA
- 14.3.2 US
- 14.3.2.1 High per capita income and high quality of treatment to support market growth
- 14.3.3 CANADA
- 14.3.3.1 Rising healthcare expenditure to drive market
- 14.4 ASIA PACIFIC
- 14.4.1 MACROECONOMIC OUTLOOK FOR ASIA PACIFIC
- 14.4.2 JAPAN
- 14.4.2.1 Rising geriatric population and favorable reimbursement scenario to support market growth
- 14.4.3 CHINA
- 14.4.3.1 Growing prevalence of dental diseases and increasing geriatric population to drive market
- 14.4.4 INDIA
- 14.4.4.1 Growing dental tourism to support market growth
- 14.4.5 AUSTRALIA
- 14.4.5.1 Growing number of registered dental practitioners to support market growth
- 14.4.6 SOUTH KOREA
- 14.4.6.1 High senior population to support market demand
- 14.4.7 REST OF ASIA PACIFIC
- 14.5 LATIN AMERICA
- 14.5.1 MACROECONOMIC OUTLOOK FOR LATIN AMERICA
- 14.5.2 BRAZIL
- 14.5.2.1 Improving access and affordability to drive market
- 14.5.3 MEXICO
- 14.5.3.1 Focus on improving healthcare infrastructure and availability of skilled dentists to drive the market
- 14.5.4 REST OF LATIN AMERICA
- 14.6 MIDDLE EAST & AFRICA
- 14.6.1 MACROECONOMIC OUTLOOK FOR MIDDLE EAST & AFRICA
- 14.6.2 GCC COUNTRIES
- 14.6.3 REST OF MIDDLE EAST & AFRICA
15 COMPETITIVE LANDSCAPE
- 15.1 INTRODUCTION
- 15.2 KEY PLAYER STRATEGY/RIGHT TO WIN
- 15.2.1 OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS IN DENTAL SUTURES MARKET
- 15.3 REVENUE ANALYSIS, 2021-2025
- 15.4 MARKET SHARE ANALYSIS, 2025
- 15.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 15.5.1 STARS
- 15.5.2 EMERGING LEADERS
- 15.5.3 PERVASIVE PLAYERS
- 15.5.4 PARTICIPANTS
- 15.5.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 15.5.5.1 Company footprint
- 15.5.5.2 Region footprint
- 15.5.5.3 Type footprint
- 15.5.5.4 Material footprint
- 15.5.5.5 Filament type footprint
- 15.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 15.6.1 PROGRESSIVE COMPANIES
- 15.6.2 RESPONSIVE COMPANIES
- 15.6.3 DYNAMIC COMPANIES
- 15.6.4 STARTING BLOCKS
- 15.6.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 15.6.5.1 Detailed list of startups/SMEs
- 15.6.5.2 Competitive benchmarking of startups/SMEs
- 15.7 BRAND/PRODUCT COMPARISON
- 15.8 COMPANY VALUATION & FINANCIAL METRICS
- 15.8.1 FINANCIAL METRICS
- 15.8.2 COMPANY VALUATION
- 15.9 COMPETITIVE SCENARIO
- 15.9.1 DEALS
- 15.9.2 EXPANSIONS
- 15.9.3 OTHER DEVELOPMENTS
16 COMPANY PROFILES
- 16.1 KEY PLAYERS
- 16.1.1 JOHNSON & JOHNSON
- 16.1.1.1 Business overview
- 16.1.1.2 Products offered
- 16.1.1.3 Recent developments
- 16.1.1.3.1 Deals
- 16.1.1.3.2 Other developments
- 16.1.1.4 MnM view
- 16.1.1.4.1 Key strengths
- 16.1.1.4.2 Strategic choices
- 16.1.1.4.3 Weaknesses & competitive threats
- 16.1.2 B. BRAUN SE
- 16.1.2.1 Business overview
- 16.1.2.2 Products offered
- 16.1.2.3 MnM view
- 16.1.2.3.1 Key strengths
- 16.1.2.3.2 Strategic choices
- 16.1.2.3.3 Weaknesses & competitive threats
- 16.1.3 ADVANCED MEDICAL SOLUTIONS GROUP PLC
- 16.1.3.1 Business overview
- 16.1.3.2 Products offered
- 16.1.3.3 Recent developments
- 16.1.3.3.1 Deals
- 16.1.3.4 MnM view
- 16.1.3.4.1 Key strengths
- 16.1.3.4.2 Strategic choices
- 16.1.3.4.3 Weaknesses & competitive threats
- 16.1.4 DEMETECH CORPORATION
- 16.1.4.1 Business overview
- 16.1.4.2 Products offered
- 16.1.4.3 MnM view
- 16.1.4.3.1 Key strengths
- 16.1.4.3.2 Strategic choices
- 16.1.4.3.3 Weaknesses & competitive threats
- 16.1.5 HU-FRIEDY MFG. CO., LLC
- 16.1.5.1 Business overview
- 16.1.5.2 Products offered
- 16.1.5.3 Recent developments
- 16.1.5.3.1 Deals
- 16.1.5.3.2 Expansions
- 16.1.5.4 MnM view
- 16.1.5.4.1 Key strengths
- 16.1.5.4.2 Strategic choices
- 16.1.5.4.3 Weaknesses & competitive threats
- 16.1.6 ENVISTA
- 16.1.6.1 Business overview
- 16.1.6.2 Products offered
- 16.1.6.3 Recent developments
- 16.1.6.3.1 Deals
- 16.1.7 HENRY SCHEIN
- 16.1.7.1 Business overview
- 16.1.7.2 Products offered
- 16.1.7.3 Recent developments
- 16.1.7.3.1 Deals
- 16.1.7.3.2 Expansions
- 16.1.7.3.3 Other developments
- 16.1.8 FUTURA SURGICARE PVT. LTD.
- 16.1.8.1 Business overview
- 16.1.8.2 Products offered
- 16.1.8.3 Recent developments
- 16.1.8.3.1 Deals
- 16.1.9 MANI, INC.
- 16.1.9.1 Business overview
- 16.1.9.2 Products offered
- 16.1.9.3 Recent developments
- 16.1.9.3.1 Other developments
- 16.1.10 CORZA MEDICAL
- 16.1.10.1 Business overview
- 16.1.10.2 Products offered
- 16.1.10.3 Recent developments
- 16.1.10.3.1 Expansions
- 16.1.10.3.2 Other developments
- 16.1.11 SMI AG
- 16.1.11.1 Business overview
- 16.1.11.2 Products offered
- 16.1.12 YOUNG INNOVATIONS, INC.
- 16.1.12.1 Business overview
- 16.1.12.2 Products offered
- 16.1.12.3 Recent developments
- 16.1.12.3.1 Deals
- 16.1.13 ASSUT EUROPE
- 16.1.13.1 Business overview
- 16.1.13.2 Products offered
- 16.1.14 KATSAN KATGUT SANAYI VE TIC. A.S.
- 16.1.14.1 Business overview
- 16.1.14.2 Products offered
- 16.1.14.3 Recent developments
- 16.1.14.3.1 Other developments
- 16.1.15 DOGSAN TIBBI MALZEME SANAYI A.S.
- 16.1.15.1 Business overview
- 16.1.15.2 Products offered
- 16.1.15.3 Recent developments
- 16.1.15.3.1 Other developments
- 16.1.1 JOHNSON & JOHNSON
- 16.2 OTHER PLAYERS
- 16.2.1 HYGITECH
- 16.2.2 ZIMVIE INC.
- 16.2.3 MEDIPAC SA
- 16.2.4 LUX SUTURES
- 16.2.5 BENTLEY HEALTHCARE PVT. LTD.
- 16.2.6 BOZ MEDICAL
- 16.2.7 DSI LTD.
- 16.2.8 GDT DENTAL IMPLANTS
- 16.2.9 GOLNIT
- 16.2.10 QUBIX MEDICARE PRIVATE LIMITED
17 RESEARCH METHODOLOGY
- 17.1 RESEARCH DATA
- 17.1.1 SECONDARY DATA
- 17.1.1.1 Key data from secondary sources
- 17.1.2 PRIMARY DATA
- 17.1.2.1 Key data from primary sources
- 17.1.2.2 Key industry insights
- 17.1.1 SECONDARY DATA
- 17.2 MARKET SIZE ESTIMATION
- 17.2.1 BOTTOM-UP APPROACH
- 17.2.2 TOP-DOWN APPROACH
- 17.2.3 BASE NUMBER ESTIMATION
- 17.2.3.1 Supply-side Analysis (Revenue Share Analysis)
- 17.2.3.2 Company presentations & primary interviews
- 17.3 MARKET FORECAST APPROACH
- 17.4 MARKET SEGMENT ASSESSMENT (BY TYPE, MATERIAL, FILAMENT TYPE, APPLICATION, AND END USER)
- 17.5 GEOGRAPHIC MARKET ASSESSMENT (BY REGION AND COUNTRY)
- 17.6 DATA TRIANGULATION
- 17.7 MARKET SHARE ESTIMATION
- 17.8 STUDY ASSUMPTIONS
- 17.9 FACTOR ANALYSIS
- 17.10 RESEARCH LIMITATIONS
- 17.10.1 SCOPE-RELATED LIMITATIONS
- 17.10.2 METHODOLOGY-RELATED LIMITATIONS
- 17.11 RISK ASSESSMENT
18 APPENDIX
- 18.1 DISCUSSION GUIDE
- 18.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 18.3 CUSTOMIZATION OPTIONS
- 18.4 RELATED REPORTS
- 18.5 AUTHOR DETAILS
List of Tables
- TABLE 1 STANDARD CURRENCY CONVERSION RATES
- TABLE 2 PROJECTED INCREASE IN NUMBER OF PEOPLE AGED OVER 65 YEARS, BY REGION, 2019 VS. 2050 (MILLION)
- TABLE 3 DENTAL SUTURES MARKET: PORTER'S FIVE FORCES ANALYSIS
- TABLE 4 GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2021-2030
- TABLE 5 AVERAGE SELLING PRICE OF DENTAL SUTURE PRODUCTS, BY KEY PLAYER, 2025
- TABLE 6 AVERAGE SELLING PRICE TREND OF NON-ABSORBABLE DENTAL SUTURES, BY REGION, 2023-2025
- TABLE 7 IMPORT DATA FOR DENTAL SUTURES (HS CODE: 300610), BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 8 EXPORT DATA FOR DENTAL SUTURES (HS CODE: 300610), BY COUNTRY, 2021-2025 (USD THOUSAND)
- TABLE 9 DENTAL SUTURES MARKET: LIST OF KEY CONFERENCES & EVENTS, 2026-2027
- TABLE 10 CASE STUDY 1: STRATAFIX KNOTLESS BARBED PDS SUTURE REDUCES INTRAORAL CLOSURE TIME IN MAXILLOFACIAL SURGERY
- TABLE 11 CASE STUDY 2: B. BRAUN DAFILON(R) DEMONSTRATES SAFE AND EFFECTIVE MUCOSAL CLOSURE IN ROUTINE ORAL SURGERY.
- TABLE 12 CASE STUDY 3: SMI DACLON SHOWS LOWER BACTERIAL COLONIZATION AND MILDER TISSUE REACTION IN THIRD-MOLAR SURGERY
- TABLE 13 US-ADJUSTED RECIPROCAL TARIFF RATES
- TABLE 14 KEY PRODUCT-RELATED TARIFFS EFFECTIVE FOR ADHESIVE BARRIER PRODUCTS
- TABLE 15 TOP USE CASES & MARKET POTENTIAL
- TABLE 16 INTERCONNECTED ADJACENT ECOSYSTEMS & IMPACT ON MARKET PLAYERS
- TABLE 17 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 18 EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 19 ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 20 LATIN AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 21 MIDDLE EAST & AFRICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 22 INFLUENCE OF KEY STAKEHOLDERS ON BUYING PROCESS OF END USERS
- TABLE 23 KEY BUYING CRITERIA FOR END USERS
- TABLE 24 ADOPTION BARRIERS & INTERNAL CHALLENGES
- TABLE 25 DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 26 ABSORBABLE DENTAL SUTURES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 27 ABSORBABLE DENTAL SUTURES MARKET, BY REGION, 2024-2031 (THOUSANDS UNITS)
- TABLE 28 NON-ABSORBABLE DENTAL SUTURES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 29 NON-ABSORBABLE DENTAL SUTURES MARKET, BY REGION, 2024-2031 (THOUSANDS UNITS)
- TABLE 30 DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 31 SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 32 SYNTHETIC DENTAL SUTURES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 33 POLYGLACTIN 910 DENTAL SUTURES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 34 POLYGLYCOLIC ACID (PGA) DENTAL SUTURES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 35 POLYTETRAFLUOROETHYLENE (PTFE) DENTAL SUTURES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 36 NYLON (POLYAMIDE) DENTAL SUTURES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 37 OTHER SYNTHETIC DENTAL SUTURES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 38 NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 39 NATURAL DENTAL SUTURES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 40 SILK DENTAL SUTURES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 41 PLAIN GUT DENTAL SUTURES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 42 CHROMIC GUT DENTAL SUTURES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 43 DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 44 MONOFILAMENT DENTAL SUTURES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 45 MULTIFILAMENT DENTAL SUTURES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 46 DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 47 DENTAL SUTURES MARKET FOR ORAL SURGERY & TOOTH EXTRACTION, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 48 DENTAL SUTURES MARKET FOR PERIODONTAL SURGERY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 49 DENTAL SUTURES MARKET FOR DENTAL IMPLANTOLOGY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 50 DENTAL SUTURES MARKET FOR MAXILLOFACIAL SURGERY, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 51 DENTAL SUTURES MARKET FOR OTHER APPLICATIONS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 52 DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 53 DENTAL SUTURES MARKET FOR DENTAL CLINICS & SPECIALTY DENTAL CENTERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 54 DENTAL SUTURES MARKET FOR HOSPITALS & AMBULATORY SURGICAL CENTERS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 55 DENTAL SUTURES MARKET FOR ACADEMIC & RESEARCH INSTITUTIONS, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 56 DENTAL SUTURES MARKET, BY REGION, 2024-2031 (USD MILLION)
- TABLE 57 EUROPE: DENTAL SUTURES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 58 EUROPE: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 59 EUROPE: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 60 EUROPE: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 61 EUROPE: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 62 EUROPE: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 63 EUROPE: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 64 EUROPE: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 65 GERMANY: KEY MACROINDICATORS
- TABLE 66 GERMANY: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 67 GERMANY: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 68 GERMANY: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 69 GERMANY: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 70 GERMANY: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 71 GERMANY: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 72 GERMANY: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 73 UK: KEY MACROINDICATORS
- TABLE 74 UK: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 75 UK: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 76 UK: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 77 UK: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 78 UK: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 79 UK: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 80 UK: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 81 FRANCE: KEY MACROINDICATORS
- TABLE 82 FRANCE: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 83 FRANCE: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 84 FRANCE: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 85 FRANCE: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 86 FRANCE: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 87 FRANCE: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 88 FRANCE: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 89 SPAIN: KEY MACROINDICATORS
- TABLE 90 SPAIN: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 91 SPAIN: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 92 SPAIN: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 93 SPAIN: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 94 SPAIN: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 95 SPAIN: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 96 SPAIN: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 97 ITALY: KEY MACROINDICATORS
- TABLE 98 ITALY: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 99 ITALY: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 100 ITALY: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 101 ITALY: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 102 ITALY: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 103 ITALY: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 104 ITALY: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 105 REST OF EUROPE: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 106 REST OF EUROPE: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 107 REST OF EUROPE: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 108 REST OF EUROPE: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 109 REST OF EUROPE: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 110 REST OF EUROPE: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 111 REST OF EUROPE: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 112 NORTH AMERICA: DENTAL SUTURES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 113 NORTH AMERICA: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 114 NORTH AMERICA: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 115 NORTH AMERICA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 116 NORTH AMERICA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 117 NORTH AMERICA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 118 NORTH AMERICA: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 119 NORTH AMERICA: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 120 US: MACROECONOMIC INDICATORS
- TABLE 121 US: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 122 US: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 123 US: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 124 US: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 125 US: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 126 US: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 127 US: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 128 CANADA: KEY MACROINDICATORS
- TABLE 129 CANADA: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 130 CANADA: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 131 CANADA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 132 CANADA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 133 CANADA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 134 CANADA: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 135 CANADA: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 136 ASIA PACIFIC: DENTAL SUTURES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 137 ASIA PACIFIC: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 138 ASIA PACIFIC: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 139 ASIA PACIFIC: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 140 ASIA PACIFIC: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 141 ASIA PACIFIC: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 142 ASIA PACIFIC: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 143 ASIA PACIFIC: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 144 JAPAN: KEY MACROINDICATORS
- TABLE 145 JAPAN: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 146 JAPAN: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 147 JAPAN: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 148 JAPAN: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 149 JAPAN: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 150 JAPAN: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 151 JAPAN: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 152 CHINA: KEY MACROINDICATORS
- TABLE 153 CHINA: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 154 CHINA: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 155 CHINA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 156 CHINA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 157 CHINA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 158 CHINA: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 159 CHINA: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 160 INDIA: KEY MACROINDICATORS
- TABLE 161 INDIA: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 162 INDIA: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 163 INDIA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 164 INDIA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 165 INDIA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 166 INDIA: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 167 INDIA: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 168 AUSTRALIA: ORAL HEALTH STATUS OF CHILDREN AND ADULTS
- TABLE 169 AUSTRALIA: MACROECONOMIC INDICATORS
- TABLE 170 AUSTRALIA: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 171 AUSTRALIA: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 172 AUSTRALIA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 173 AUSTRALIA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 174 AUSTRALIA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 175 AUSTRALIA: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 176 AUSTRALIA: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 177 SOUTH KOREA: NUMBER OF FOREIGN PATIENTS VISITING DENTAL FACILITIES, 2017-2021
- TABLE 178 SOUTH KOREA: KEY MACROINDICATORS
- TABLE 179 SOUTH KOREA: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 180 SOUTH KOREA: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 181 SOUTH KOREA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 182 SOUTH KOREA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 183 SOUTH KOREA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 184 SOUTH KOREA: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 185 SOUTH KOREA: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 186 REST OF ASIA PACIFIC: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 187 REST OF ASIA PACIFIC: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 188 REST OF ASIA PACIFIC: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 189 REST OF ASIA PACIFIC: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 190 REST OF ASIA PACIFIC: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 191 REST OF ASIA PACIFIC: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 192 REST OF ASIA PACIFIC: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 193 LATIN AMERICA: DENTAL SUTURES MARKET, BY COUNTRY, 2024-2031 (USD MILLION)
- TABLE 194 LATIN AMERICA: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 195 LATIN AMERICA: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 196 LATIN AMERICA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 197 LATIN AMERICA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 198 LATIN AMERICA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 199 LATIN AMERICA: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 200 LATIN AMERICA: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 201 BRAZIL: KEY MACROINDICATORS
- TABLE 202 BRAZIL: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 203 BRAZIL: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 204 BRAZIL: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 205 BRAZIL: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 206 BRAZIL: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 207 BRAZIL: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 208 BRAZIL: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 209 MEXICO: KEY MACROINDICATORS
- TABLE 210 MEXICO: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 211 MEXICO: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 212 MEXICO: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 213 MEXICO: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 214 MEXICO: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 215 MEXICO: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 216 MEXICO: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 217 REST OF LATIN AMERICA: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 218 REST OF LATIN AMERICA: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 219 REST OF LATIN AMERICA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 220 REST OF LATIN AMERICA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 221 REST OF LATIN AMERICA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 222 REST OF LATIN AMERICA: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 223 REST OF LATIN AMERICA: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 224 MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY REGION, 2024-2031 (USD MILLION)
- TABLE 225 MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 226 MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 227 MIDDLE EAST & AFRICA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 228 MIDDLE EAST & AFRICA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 229 MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 230 MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 231 MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 232 GCC COUNTRIES: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 233 GCC COUNTRIES: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 234 GCC COUNTRIES: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 235 GCC COUNTRIES: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 236 GCC COUNTRIES: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 237 GCC COUNTRIES: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 238 GCC COUNTRIES: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 239 REST OF MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 240 REST OF MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY MATERIAL, 2024-2031 (USD MILLION)
- TABLE 241 REST OF MIDDLE EAST & AFRICA: SYNTHETIC DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 242 REST OF MIDDLE EAST & AFRICA: NATURAL DENTAL SUTURES MARKET, BY TYPE, 2024-2031 (USD MILLION)
- TABLE 243 REST OF MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY FILAMENT TYPE, 2024-2031 (USD MILLION)
- TABLE 244 REST OF MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY APPLICATION, 2024-2031 (USD MILLION)
- TABLE 245 REST OF MIDDLE EAST & AFRICA: DENTAL SUTURES MARKET, BY END USER, 2024-2031 (USD MILLION)
- TABLE 246 OVERVIEW OF STRATEGIES DEPLOYED BY KEY PLAYERS IN DENTAL SUTURES MARKET
- TABLE 247 DENTAL SUTURES MARKET: DEGREE OF COMPETITION
- TABLE 248 DENTAL SUTURES MARKET: REGION FOOTPRINT
- TABLE 249 DENTAL SUTURES MARKET: TYPE FOOTPRINT
- TABLE 250 DENTAL SUTURES MARKET: MATERIAL FOOTPRINT
- TABLE 251 DENTAL SUTURES MARKET: FILAMENT TYPE FOOTPRINT
- TABLE 252 DENTAL SUTURES MARKET: DETAILED LIST OF KEY STARTUPS/SMES
- TABLE 253 DENTAL SUTURES MARKET: COMPETITIVE BENCHMARKING OF STARTUPS/SMES
- TABLE 254 DENTAL SUTURES MARKET: DEALS, JANUARY 2022-JULY 2026
- TABLE 255 DENTAL SUTURES MARKET: EXPANSIONS, JANUARY 2022-JULY 2026
- TABLE 256 DENTAL SUTURES MARKET: OTHER DEVELOPMENTS, JANUARY 2022-JULY 2026
- TABLE 257 JOHNSON & JOHNSON: COMPANY OVERVIEW
- TABLE 258 JOHNSON & JOHNSON: PRODUCTS OFFERED
- TABLE 259 JOHNSON & JOHNSON: DEALS, JANUARY 2022-JULY 2026
- TABLE 260 JOHNSON & JOHNSON: OTHER DEVELOPMENTS, JANUARY 2022-JULY 2026
- TABLE 261 B. BRAUN SE: COMPANY OVERVIEW
- TABLE 262 B. BRAUN SE: PRODUCTS OFFERED
- TABLE 263 ADVANCED MEDICAL SOLUTIONS GROUP PLC: COMPANY OVERVIEW
- TABLE 264 ADVANCED MEDICAL SOLUTIONS GROUP PLC: PRODUCTS OFFERED
- TABLE 265 ADVANCED MEDICAL SOLUTIONS GROUP PLC: DEALS, JANUARY 2022-JULY 2026
- TABLE 266 DEMETECH CORPORATION: COMPANY OVERVIEW
- TABLE 267 DEMETECH CORPORATION: PRODUCTS OFFERED
- TABLE 268 HU-FRIEDY MFG. CO., LLC: COMPANY OVERVIEW
- TABLE 269 HU-FRIEDY MFG. CO., LLC: PRODUCTS OFFERED
- TABLE 270 HU-FRIEDY MFG. CO., LLC: DEALS, JANUARY 2022-JULY 2026
- TABLE 271 HU-FRIEDY MFG. CO., LLC: EXPANSIONS, JANUARY 2022-JULY 2026
- TABLE 272 ENVISTA: COMPANY OVERVIEW
- TABLE 273 ENVISTA: PRODUCTS OFFERED
- TABLE 274 ENVISTA: DEALS, JANUARY 2022-JUNE 2025
- TABLE 275 HENRY SCHEIN: COMPANY OVERVIEW
- TABLE 276 HENRY SCHEIN: PRODUCTS OFFERED
- TABLE 277 HENRY SCHEIN: DEALS, JANUARY 2022-JULY 2026
- TABLE 278 HENRY SCHEIN, INC.: EXPANSIONS, JANUARY 2022-JULY 2026
- TABLE 279 HENRY SCHEIN, INC.: OTHER DEVELOPMENTS, JANUARY 2022-JULY 2026
- TABLE 280 FUTURA SURGICARE PVT. LTD.: COMPANY OVERVIEW
- TABLE 281 FUTURA SURGICARE PVT. LTD.: PRODUCTS OFFERED
- TABLE 282 FUTURA SURGICARE PVT. LTD.: DEALS, JANUARY 2022-JULY 2026
- TABLE 283 MANI, INC.: COMPANY OVERVIEW
- TABLE 284 MANI, INC.: PRODUCTS OFFERED
- TABLE 285 MANI, INC.: OTHER DEVELOPMENTS, JANUARY 2022-JULY 2026
- TABLE 286 CORZA MEDICAL: COMPANY OVERVIEW
- TABLE 287 CORZA MEDICAL: PRODUCTS OFFERED
- TABLE 288 CORZA MEDICAL: EXPANSIONS, JANUARY 2022-JULY 2026
- TABLE 289 CORZA MEDICAL: OTHER DEVELOPMENTS, JANUARY 2022-JULY 2026
- TABLE 290 SMI AG: COMPANY OVERVIEW
- TABLE 291 SMI AG: PRODUCTS OFFERED
- TABLE 292 YOUNG INNOVATIONS, INC.: COMPANY OVERVIEW
- TABLE 293 YOUNG INNOVATIONS, INC.: PRODUCTS OFFERED
- TABLE 294 YOUNG INNOVATIONS, INC.: DEALS, JANUARY 2022-JULY 2026
- TABLE 295 ASSUT EUROPE: COMPANY OVERVIEW
- TABLE 296 ASSUT EUROPE: PRODUCTS OFFERED
- TABLE 297 KATSAN KATGUT SANAYI VE TIC. A.S.: COMPANY OVERVIEW
- TABLE 298 KATSAN KATGUT SANAYI VE TIC. A.S.: PRODUCTS OFFERED
- TABLE 299 KATSAN KATGUT SANAYI VE TIC. A.S: OTHER DEVELOPMENTS, JANUARY 2022-JULY 2026
- TABLE 300 DOGSAN TIBBI MALZEME SANAYI A.S.: COMPANY OVERVIEW
- TABLE 301 DOGSAN TIBBI MALZEME SANAYI A.S.: PRODUCTS OFFERED
- TABLE 302 DOGSAN TIBBI MALZEME SANAYI A.S.: OTHER DEVELOPMENTS, JANUARY 2022-JULY 2026
- TABLE 303 RISK ASSESSMENT: DENTAL SUTURES MARKET
List of Figures
- FIGURE 1 DENTAL SUTURES MARKET SEGMENTATION & REGIONAL SCOPE
- FIGURE 2 KEY INSIGHTS & MARKET HIGHLIGHTS
- FIGURE 3 DENTAL SUTURES MARKET, 2024-2031 (USD MILLION)
- FIGURE 4 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN DENTAL SUTURES MARKET
- FIGURE 5 DISRUPTIVE TRENDS IMPACTING GROWTH OF DENTAL SUTURES MARKET
- FIGURE 6 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS IN DENTAL SUTURES MARKET, 2025
- FIGURE 7 ASIA PACIFIC TO REGISTER HIGHEST GROWTH DURING FORECAST PERIOD
- FIGURE 8 INCREASING VOLUME OF DENTAL SURGERIES AND EXPANDING DENTAL CARE ACCESS TO DRIVE MARKET GROWTH
- FIGURE 9 ASIA PACIFIC DENTAL SUTURES MARKET TO REGISTER HIGHEST GROWTH RATE DURING STUDY PERIOD
- FIGURE 10 CHINA TO ACCOUNT FOR LARGEST MARKET SHARE IN 2025
- FIGURE 11 INDIA TO REGISTER HIGHEST CAGR FROM 2026 TO 2031
- FIGURE 12 EMERGING MARKETS TO REGISTER HIGHEST GROWTH DURING FORECAST PERIOD
- FIGURE 13 DENTAL SUTURES MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
- FIGURE 14 UK: PROJECTED NUMBER OF ADULTS 16 YEARS AND OLDER WITH DENTAL CARIES, 2020 VS. 2035 VS. 2050
- FIGURE 15 DENTAL SUTURES MARKET: PORTER'S FIVE FORCES ANALYSIS
- FIGURE 16 DENTAL SUTURES MARKET: VALUE CHAIN ANALYSIS
- FIGURE 17 DENTAL SUTURES MARKET: ECOSYSTEM ANALYSIS
- FIGURE 18 DENTAL SUTURES MARKET: TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- FIGURE 19 TOP PATENT APPLICANTS AND OWNERS (COMPANIES/INSTITUTES) IN DENTAL SUTURES MARKET (JANUARY 2015-DECEMBER 2025)
- FIGURE 20 JURISDICTION ANALYSIS: TOP APPLICANT COUNTRIES FOR DENTAL SUTURES PATENTS, 2015-2025
- FIGURE 21 INFLUENCE OF KEY STAKEHOLDERS ON BUYING PROCESS OF DENTAL SUTURES, BY END USER
- FIGURE 22 KEY BUYING CRITERIA FOR END USERS
- FIGURE 23 DENTAL SUTURES MARKET: GEOGRAPHIC GROWTH OPPORTUNITIES
- FIGURE 24 NORTH AMERICA: DENTAL SUTURES MARKET SNAPSHOT
- FIGURE 25 ASIA PACIFIC: DENTAL SUTURES MARKET SNAPSHOT
- FIGURE 26 REVENUE ANALYSIS OF KEY PLAYERS IN DENTAL SUTURES MARKET (2021-2025)
- FIGURE 27 MARKET SHARE ANALYSIS OF KEY PLAYERS IN DENTAL SUTURES MARKET (2025)
- FIGURE 28 DENTAL SUTURES MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
- FIGURE 29 DENTAL SUTURES MARKET: COMPANY FOOTPRINT
- FIGURE 30 DENTAL SUTURES MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
- FIGURE 31 DENTAL SUTURES MARKET: BRAND/PRODUCT COMPARISON
- FIGURE 32 EV/EBITDA OF KEY VENDORS
- FIGURE 33 YEAR-TO-DATE (YTD) PRICE TOTAL RETURN AND 5-YEAR STOCK BETA OF KEY VENDOR
- FIGURE 34 JOHNSON & JOHNSON: COMPANY SNAPSHOT (2025)
- FIGURE 35 B. BRAUN SE: COMPANY SNAPSHOT (2025)
- FIGURE 36 COMPANY SNAPSHOT: ADVANCED MEDICAL SOLUTIONS GROUP PLC (2025)
- FIGURE 37 ENVISTA: COMPANY SNAPSHOT (2025)
- FIGURE 38 HENRY SCHEIN: COMPANY SNAPSHOT (2025)
- FIGURE 39 MANI, INC.: COMPANY SNAPSHOT (2025)
- FIGURE 40 RESEARCH DESIGN
- FIGURE 41 PRIMARY SOURCES
- FIGURE 42 BOTTOM-UP APPROACH
- FIGURE 43 TOP-DOWN APPROACH
- FIGURE 44 DENTAL SUTURES MARKET SIZE ESTIMATION: REVENUE SHARE ANALYSIS (SUPPLY SIDE)
- FIGURE 45 REVENUE SHARE ANALYSIS ILLUSTRATION: JOHNSON & JOHNSON
- FIGURE 46 DENTAL SUTURES MARKET: SUPPLY-SIDE ANALYSIS (2025)
- FIGURE 47 CAGR PROJECTIONS: SUPPLY-SIDE ANALYSIS
- FIGURE 48 DATA TRIANGULATION METHODOLOGY

