PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2044073

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2044073
Industrial Safety - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
The Industrial Safety market size is projected to be USD 6.51 billion in 2025, USD 6.73 billion in 2026, and reach USD 8.07 billion by 2031, growing at a CAGR of 3.7% from 2026 to 2031.
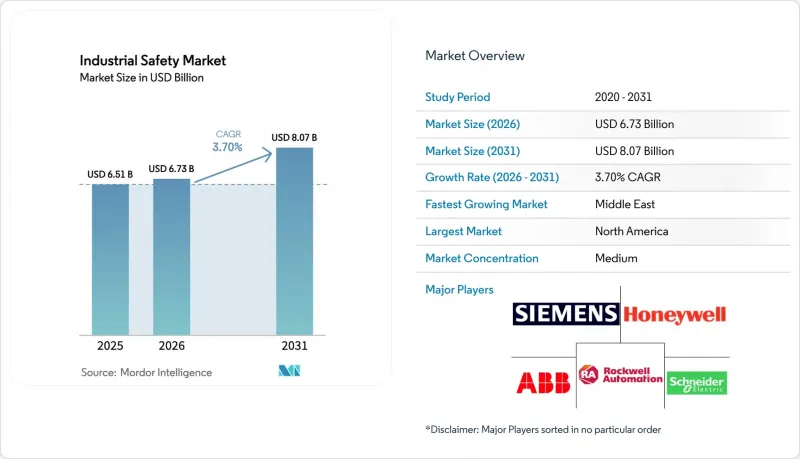
Demand is shifting from one-off hardware upgrades toward integrated safety architectures that combine cybersecurity, real-time analytics, and modular retrofits, enabling operators to satisfy tightening certification timelines and ESG disclosures EUROPEAN COMMISSION. Safety sensors still anchor the hardware stack, yet multiyear service contracts for lifecycle support now secure the strongest pricing power. Emergency Shutdown platforms dominate revenues, but High Integrity Pressure Protection Systems post the fastest unit growth as hydrogen, pharmaceutical, and deep-water producers re-engineer overpressure defenses IEC. Regionally, North America holds the largest spending base, whereas Saudi Arabia and the United Arab Emirates are scaling budgets the quickest under sovereign-fund mandates REUTERS. Vendors are responding with edge-ready controllers, cloud analytics, and plug-and-play modules that shorten brownfield commissioning cycles while lowering total installed cost.
Global Industrial Safety Market Trends and Insights
Increasing Regulatory Pressure Across High-Risk Industries
The European Union's Corporate Sustainability Reporting Directive obliges more than 50,000 firms to disclose incident data, turning functional-safety outlays into a board-level compliance metric. In the United States, twelve OSHA National Emphasis Programs launched in 2024 lifted maximum penalties to USD 161,323 per violation, accelerating capital allocation for SIL-rated Emergency Shutdown and Fire and Gas Monitoring projects. IEC 61511 Edition 2 simultaneously closed cybersecurity loopholes by mandating threat modeling for Safety Instrumented Systems, forcing brownfield operators to upgrade documentation and network segmentation IEC. Insurers have reacted by embedding functional-safety audits into policy renewals, raising premiums on non-compliant sites. Collectively, faster enforcement compresses return-on-investment horizons and elevates safety upgrades from discretionary to essential spending.
IIoT, Robotics and Advanced Automation Penetration
Honeywell's Forge platform, active across 127 process plants in 2025, combines live telemetry with machine-learning models that predict valve or actuator failure up to 14 days in advance, trimming unplanned downtime by nearly one-fifth. ABB's SafeMove2 robotics suite, certified to IEC 61508 SIL 2, enables dynamic speed and force limiting for collaborative tasks, expanding safety requirements to new automation cells ABB. While these digital layers improve reliability, they also widen the cyber-attack surface and now require ISA/IEC 62443 controls that add double-digit integration cost ISA. Enterprises that bolt IIoT onto legacy controls risk data silos that cannot drive predictive safety, weakening the underlying business case. Still, productivity benefits outweigh incremental complexity, securing a 0.9% positive lift on forecast CAGR.
High Upfront CAPEX for SIL-Rated Systems
A SIL 3 Emergency Shutdown package for a midsize refinery costs USD 4.2-6.8 million plus another USD 1.1-1.9 million for third-party verification, delivering a 3X premium over a non-SIL control upgrade. Emerging-market contractors face an added burden when local-content rules mandate uncertified valves that require redesign or import waivers. Modular, pre-certified skids can shave 20% off installed cost, yet adoption remains skewed to greenfield builds where layouts are still fluid. Capital scarcity, therefore, delays upgrades at the very assets that bear the highest process-safety risk, clipping 0.8% from the Industrial Safety market CAGR.
Other drivers and restraints analyzed in the detailed report include:
- Worker-Safety KPIs Embedded in ESG Scorecards
- Functional-Safety Certification Demand in Emerging Economies
- Complex Integration with Legacy PLC and DCS Assets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Safety sensors secured 33.37% of 2025 revenue as IEC 61511 redundancy rules tripled detector counts in SIL 3 loops IEC. Controllers and relays ranked second, spearheaded by compact, modular designs such as Pilz PSS 4000 that fit pharmaceutical suites. Valves lag as partial-stroke diagnostics extend overhaul intervals, while Asian entrants undercut Western incumbents on price for barriers, power supplies, and HMIs. Services post a 3.96% CAGR because multi-year contracts bundle proof tests, firmware updates, and spare pools, locking in predictable income streams. Honeywell reported a 19% jump in lifecycle-service bookings in 2025, driven by cross-site framework deals. Consulting and training advance at 4.02% as TUV-licensed auditors command premium day rates amid acute talent gaps.
The shift toward as-a-service engagement pulls margin from hardware into recurring revenue. Installation still holds 30.53% of service spend, although factory-pretested skids compress onsite labor by one-quarter. Maintenance and testing activities scale up because 40% of North American safety systems installed prior to 2010 are now approaching their second proof-test cycle. As brownfield portfolios age, vendors that bundle field services with analytics secure preferred-supplier status, deepening wallet share and raising switching costs across the Industrial Safety market.
Emergency Shutdown solutions generated 37.62% of 2025 revenue, underpinned by decades of regulatory entrenchment in refining and chemicals API. Fire and Gas Monitoring follows, boosted by wireless detectors that lower cabling cost and reduce false trips by 60%. ESD systems' market leadership reflects decades of installed base and regulatory entrenchment: the American Petroleum Institute's RP 14C standard, last revised in 2017, prescribes ESD logic for offshore platforms, while the European Union's Seveso III Directive mandates ESD interlocks for upper-tier establishments handling flammable or toxic substances.
HIPPS registers the strongest 4.11% CAGR as hydrogen pipelines and aseptic fill-finish suites require millisecond-level cutoffs to avert vent-to-atmosphere penalties. Burner Management gains relevance in waste-heat and hydrogen turbines tied to decarbonization projects. Other Safety Systems, encompassing High Integrity Alarm Management and Safety Instrumented Function logic solvers, are seeing niche adoption in nuclear and aerospace applications where SIL 4 certification is mandatory, but account for less than 8% of total safety-system revenue due to their specialized engineering requirements and limited vendor base.
The Industrial Safety Market Report is Segmented by Component (Safety Sensors, and More), Safety System (Emergency Shutdown, Fire and Gas Monitoring, and More), Service (Installation and Commissioning, and More), Security Level (SIL 1, and More), End-User Industry (Oil and Gas, Energy and Power, Chemicals and Petrochemicals, Metals and Mining, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Geography Analysis
North America held 33.73% of the Industrial Safety market share in 2025, thanks to a dense base of aging refineries and OSHA penalty multipliers that motivate rapid upgrades. Canada's oil sands producers invested CAD 920 million (USD 680 million) in SIL 3 interlocks for steam-assisted gravity drainage wells, extending the capture of regional spend. Mexico's opening of upstream acreage sparks new facilities designed around modular safety skids that cut commissioning by one-third.
Europe advances compliance under Seveso III and worker-safety disclosure mandates. Germany's chemical majors alone earmarked EUR 1.4 billion (USD 1.5 billion) for safety upgrades in 2025. The United Kingdom's Health and Safety Executive served 78 improvement notices to operators behind on proof testing, accelerating adoption of remote valve diagnostics. Eastern Europe faces budget friction on greenfield projects, but leverages EU grants to embed SIL-3 controllers in hydrogen hubs.
The Middle East logs the fastest 4.19% CAGR throughout 2026-2031. Saudi Arabia's Public Investment Fund devoted USD 3.2 billion to NEOM industrial clusters, while ADNOC integrates Ability System 800xA controllers and SafeMove2 robotics across 14 Ruwais trains, shaving 22% engineering cost. Africa, led by South Africa's mining and Nigeria's upstream sectors, remains nascent due to capital constraints and a shortage of TUV-certified talent. Asia Pacific displays bifurcation: China and India accelerate under hydrogen and petrochemical expansions, whereas Southeast Asian LNG megaprojects employ SIL-2 detectors to unlock export financing. South America cycles spend with commodity prices, as Petrobras and Vaca Muerta developers rely on pre-certified skids to counter engineering shortages.
- Schneider Electric SE
- Honeywell International Inc.
- Rockwell Automation Inc.
- Siemens AG
- ABB Ltd.
- Emerson Electric Co.
- Baker Hughes Company
- HIMA Paul Hildebrandt GmbH
- Yokogawa Electric Corporation
- Omron Corporation
- Johnson Controls International plc
- Balluff GmbH
- Keyence Corporation
- IDEC Corporation
- SICK AG
- Mitsubishi Electric Corporation
- Endress+Hauser AG
- Pilz GmbH & Co. KG
- Pepperl+Fuchs SE
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Regulatory Pressure Across High-Risk Industries
- 4.2.2 IIoT, Robotics And Advanced Automation Penetration
- 4.2.3 Worker-Safety Kpis Embedded In ESG Scorecards
- 4.2.4 Functional-Safety Certification Demand In Emerging Economies
- 4.2.5 Cyber-Secure Safety System Architectures
- 4.2.6 Retrofit-Friendly, Modular Safety Plug-Ins
- 4.3 Market Restraints
- 4.3.1 High Upfront CAPEX For SIL-Rated Systems
- 4.3.2 Complex Integration With Legacy PLC/DCS
- 4.3.3 Scarcity Of TUV-Certified Functional-Safety Engineers
- 4.3.4 ROI Uncertainty In Low-Incident Industries
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Safety Sensors
- 5.1.2 Safety Controllers and Relays
- 5.1.3 Safety Valves
- 5.1.4 Other Components
- 5.2 By Safety System
- 5.2.1 Emergency Shutdown (ESD)
- 5.2.2 Fire and Gas Monitoring
- 5.2.3 High Integrity Pressure Protection (HIPPS)
- 5.2.4 Burner Management Systems (BMS)
- 5.2.5 Other Safety Systems
- 5.3 By Service
- 5.3.1 Installation and Commissioning
- 5.3.2 Consulting and Training
- 5.3.3 Maintenance and Support
- 5.3.4 Testing and Inspection
- 5.4 By Security Level (SIL)
- 5.4.1 SIL 1
- 5.4.2 SIL 2
- 5.4.3 SIL 3
- 5.4.4 SIL 4
- 5.5 By End-user Industry
- 5.5.1 Bottles And Jars
- 5.5.2 Oil and Gas
- 5.5.2.1 Caps And Closures
- 5.5.3 Energy and Power
- 5.5.3.1 Bulk-Grade Products
- 5.5.4 Chemicals and Petrochemicals
- 5.5.4.1 Other Rigid Plastics Product Types
- 5.5.5 Metals and Mining
- 5.5.6 Food and Beverage
- 5.5.6.1 Pouches
- 5.5.7 Pharmaceutical and Healthcare
- 5.5.7.1 Bags
- 5.5.8 Automotive
- 5.5.8.1 Films And Wraps
- 5.5.9 Aerospace and Defense
- 5.5.9.1 Other Flexible Plastics Product Types
- 5.5.10 Other End-user Industries
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia and New Zealand
- 5.6.4.6 Southeast Asia
- 5.6.4.7 Rest of Asia Pacific
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Turkey
- 5.6.5.4 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Nigeria
- 5.6.6.3 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global-level Overview, Market-level Overview, Core Segments, Financials As Available, Strategic Information, Market Rank/Share For Key companies, Products and Services, Recent Developments)
- 6.4.1 Schneider Electric SE
- 6.4.2 Honeywell International Inc.
- 6.4.3 Rockwell Automation Inc.
- 6.4.4 Siemens AG
- 6.4.5 ABB Ltd.
- 6.4.6 Emerson Electric Co.
- 6.4.7 Baker Hughes Company
- 6.4.8 HIMA Paul Hildebrandt GmbH
- 6.4.9 Yokogawa Electric Corporation
- 6.4.10 Omron Corporation
- 6.4.11 Johnson Controls International plc
- 6.4.12 Balluff GmbH
- 6.4.13 Keyence Corporation
- 6.4.14 IDEC Corporation
- 6.4.15 SICK AG
- 6.4.16 Mitsubishi Electric Corporation
- 6.4.17 Endress+Hauser AG
- 6.4.18 Pilz GmbH & Co. KG
- 6.4.19 Pepperl+Fuchs SE
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

