PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2062027

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2062027
Nano Zinc Oxide - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the nano zinc oxide market size is projected to expand from USD 521.22 million in 2025 and USD 555.99 million in 2026 to USD 767.85 million by 2031, registering a CAGR of 6.67% between 2026 and 2031.
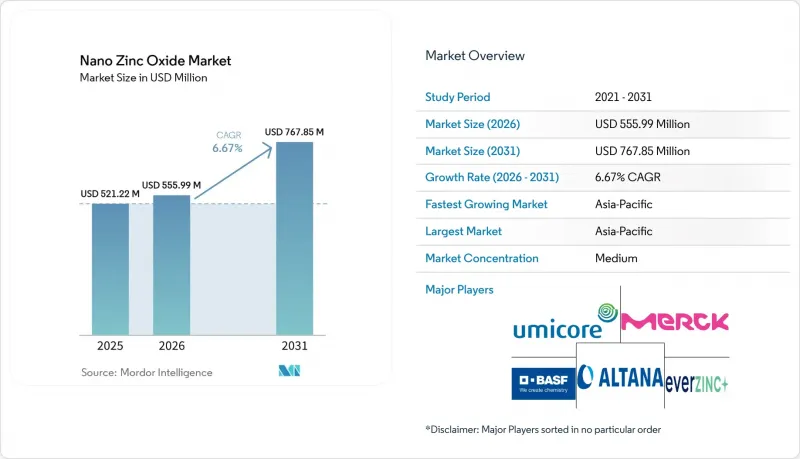
This report is Segmented by Type (Coated Nano Zinc Oxide and Uncoated Nano Zinc Oxide), Form (Powder and Dispersion/Slurry), Application (Personal Care and Cosmetics, Paints and Coatings, Electronics, Textiles, Rubber and Plastics, Pharmaceuticals, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Nano Zinc Oxide Market Trends and Insights
Regulatory Shift Toward Non-Nano TiO2 Alternatives in Sunscreens
Expanded scrutiny of titanium dioxide has redirected sunscreen innovation. The Scientific Committee on Consumer Safety (SCCS) intensified its review of nano-TiO2 during 2024, prompting formulators to prioritize zinc oxide that stays just above the 100-nm threshold, thereby avoiding nano labeling while preserving transparency. Concurrently, the US Food and Drug Administration (FDA)'s unresolved monograph leaves 12 organic filters in limbo, whereas zinc oxide retains Category I status, reinforcing its safe-harbor advantage. Suppliers such as Solesence apply aluminum-oxide and organosilane shells that deliver high SPF with minimal whitening, a capability validated by its Australian TGA site clearance. Market inquiries rose sharply after the May 2025 SCCS ban on 4-methylbenzylidene camphor, consolidating zinc oxide's position as one of the few globally harmonized UV filters. These converging regulations are forecast to keep mineral actives at the forefront of premium sun-care launches across developed economies.
Rising Use in Mini-LED/µ-LED Backplane Electronics
Display manufacturers are transitioning to aluminum- or gallium-doped zinc oxide as a cost-efficient transparent conductor. Peer-reviewed 2024 studies showed atomic-layer-deposited AZO films achieving sheet resistance below 10 Ω/sq with over 85% visible-light transmittance, meeting 4K and 8K panel specifications. Japan and South Korea integrated these films into premium televisions that shipped in excess of 2 million units in 2025. China's rapid capacity build-out for mini-LED backlights further elevates regional demand. Because zinc oxide can be solution-processed at low temperatures, the material also aligns with flexible and wearable electronics, positioning the nano zinc oxide market for continued expansion as micro-LED architectures scale commercially.
High CAPEX/OPEX for Vapor-Phase Flame-Spray Synthesis Routes
Building a 10,000 tons per year flame-spray plant requires USD 4-7 million for reactors, precipitators, and pollution controls. Operating costs of USD 800-1,200 per ton, driven by natural-gas flames and exhaust scrubbing, squeeze Western margins, especially with EU carbon allowances exceeding EUR 80 (~USD 93.20) per ton in 2025. Pilot hydrothermal projects achieved cost parity but face scalability challenges due to nucleation kinetics. Until continuous hydrothermal processing matures, Chinese producers with lower utility tariffs retain a structural cost edge, restraining price realization across the nano zinc oxide market.
Other drivers and restraints analyzed in the detailed report include:
- Antibacterial Surface Coatings for High-Touch Public Assets
- EU Micro-Plastics Ban Spurring Bio-Degradable UV-Packaging Inks
- Stricter Occupational Exposure Limits for Nano-Metals
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Coated variants secured 62.21% nano zinc oxide market share in 2025, owing to surface treatments that reduce photocatalysis and deliver an invisible finish in sunscreens. The premium added cost of USD 2-5/kg is absorbed by personal-care brands that prioritize consumer aesthetics and reef safety. Uncoated grades, though smaller, are predicted to outpace with a 6.88% CAGR as drug-delivery developers need pristine surfaces for optimal cell uptake. Pharmaceutical trials published in 2024 showed 60% bioavailability for uncoated nanoparticles versus 35-40% for coated ones. Regulatory nuance is pivotal: coated grades often require separate EU REACH (Registration, Evaluation, Authorisation and Restriction of Chemicals) dossiers, posing a hurdle for new entrants. Advance ZincTek invested early in REACH and TGA (Therapeutic Goods Administration) compliance, positioning itself for post-4-MBC demand spikes in Europe.
Second-order effects include competitive protection for firms holding coating IP portfolios. Solesence lists 10 US patents and over 100 foreign filings, leveraging exclusivity to negotiate long-term supply agreements with BASF. As consumer brands consolidate suppliers for transparency, the coated segment will remain the pricing anchor of the nano zinc oxide market, while uncoated growth taps higher-margin pharmaceutical channels.
Geography Analysis
Asia-Pacific held 48.11% of 2025 revenue, with a forecast of 7.74% CAGR during the forecast period (2026-2031), led by China's low-cost flame-spray plants and Japan's electronics demand. Chinese suppliers such as Huzheng and SAT NANO sell commodity powder at USD 1.50-2.13/kg, undercutting Western prices by up to 40%. Quality variability limits penetration in high-value pharma grades, allowing Japanese and Australian players to serve premium niches. India's cosmetics boom under the PLI scheme and Rubamin's 50,000 tons per year capacity extension reinforce South Asia's emerging influence over nano zinc oxide market dynamics.
North America's 2025 market share was buoyed by clean-beauty preferences and EV infrastructure investment. Solesence booked USD 52.3 million revenue in 2024, with finished consumer products representing 85% of sales, demonstrating value capture closer to the brand front line. The December 2025 U.S.-Korea Zinc deal to build a USD 6.7-7.4 billion smelter in Tennessee secures domestic Super Special High Grade (SHG) zinc supply by 2029, mitigating feedstock risk for regional nano zinc oxide market participants.
In Europe, REACH dossier costs and SCCS vigilance create high compliance barriers, favoring incumbents such as BASF and Merck KGaA. The May 2025 4-MBC ban catalyzed mineral UV filter demand, yet Advance ZincTek's interim report showed flat European sales at AUD 0.41 million, illustrating long formulary qualification cycles. Supply tightness persists for more than or equal to 99.99% purity zinc, prompting EU manufacturers to diversify sourcing via off-take agreements with Kazakhstan and Norway smelters.
- Advanced NanoTech Lab
- ALTANA
- American Elements
- BASF
- EverZinc
- Inframat Advanced Materials LLC
- Intelligent Materials Private Limited
- Merck KGaA
- Nanoshel LLC
- Reade
- SkySpring Nanomaterials, Inc.
- Umicore
- US Research Nanomaterials, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Regulatory shift toward non-nano TiO2 alternatives in sunscreens
- 4.2.2 Rising use in mini-LED/µ-LED backplane electronics
- 4.2.3 Antibacterial surface coatings for high-touch public assets
- 4.2.4 EU micro-plastics ban spurring bio-degradable UV-packaging inks
- 4.2.5 ZnO varistor ceramics for EV fast-charging surge protection
- 4.3 Market Restraints
- 4.3.1 High CAPEX/OPEX for vapor-phase flame-spray synthesis routes
- 4.3.2 Stricter occupational exposure limits for nano-metals
- 4.3.3 Volatile availability-pricing of more than or equal to 99.9% purity Zn feedstock
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Coated Nano Zinc Oxide
- 5.1.2 Uncoated Nano Zinc Oxide
- 5.2 By Form
- 5.2.1 Powder
- 5.2.2 Dispersion/Slurry
- 5.3 By Application
- 5.3.1 Personal Care and Cosmetics
- 5.3.2 Paints and Coatings
- 5.3.3 Electronics
- 5.3.4 Textiles
- 5.3.5 Rubber and Plastics
- 5.3.6 Pharmaceuticals
- 5.3.7 Other Applications (Textiles, Rubber, and More)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 Japan
- 5.4.1.3 India
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 NORDIC Countries
- 5.4.3.8 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Advanced NanoTech Lab
- 6.4.2 ALTANA
- 6.4.3 American Elements
- 6.4.4 BASF
- 6.4.5 EverZinc
- 6.4.6 Inframat Advanced Materials LLC
- 6.4.7 Intelligent Materials Private Limited
- 6.4.8 Merck KGaA
- 6.4.9 Nanoshel LLC
- 6.4.10 Reade
- 6.4.11 SkySpring Nanomaterials, Inc.
- 6.4.12 Umicore
- 6.4.13 US Research Nanomaterials, Inc.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment

