PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2062132

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2062132
Sodium Lauroyl Isethionate - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the sodium lauroyl isethionate market size is expected to grow from USD 123.45 million in 2025 to USD 129.76 million in 2026 and is forecast to reach USD 166.48 million by 2031 at 5.11% CAGR over 2026-2031.
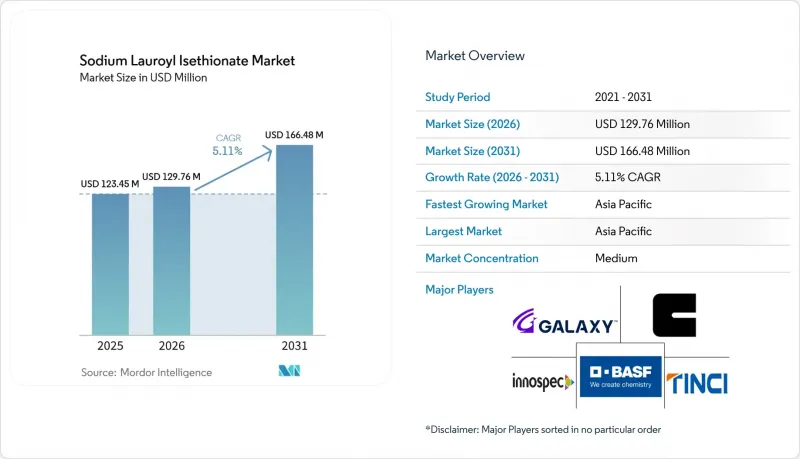
This report is Segmented by Form (Powder, Granules, and Chips/Flakes), Application (Hair-Care, Skin-Care, Cleaning Products, and More), End-Use Industry (Personal-Care and Cosmetics, Household and Institutional Cleaning, and More), and Geography (Asia-Pacific, North America, Europe, South America, and the Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Sodium Lauroyl Isethionate Market Trends and Insights
Rising Penetration in Personal-Care and Cosmetics
Solid shampoos, body-wash bars, and facial cleansers are migrating from niche to mainstream retail shelves, and the surfactant's 40-60% active loading capacity allows brands to press compact bars without brittleness. Premium outlets such as Sephora and Ulta stock syndet bars priced USD 12-18, versus USD 8-12 for bottled equivalents, reinforcing value expansion. Clariant's CHF 80 million (USD 100.91 million) Daya Bay expansion in November 2025 specifically targets mild-surfactant supply for solid-format beauty. These developments confirm that the sodium lauroyl isethionate market is riding durable sustainability and premiumization waves rather than a passing trend.
Rapid Adoption in Baby-Care Cleansing Bars
Dermatologists increasingly direct parents toward sulfate-free cleansers, making mild solid bars the default for infant care across China, India, and the United States. Hard-water regions in Asia favor sodium lauroyl isethionate for its dense foam and easy rinse, attributes that cocoyl isethionate cannot fully match. Kao's Bio IOS launch positions the firm to capture zero-dioxane baby shampoos, aligning with emerging Food and Drug Administration (FDA) modernization efforts. Short product-development cycles in baby-care accelerate this driver's impact on the overall sodium lauroyl isethionate market.
Tight Supply of High-Purity Fatty-Acid Feedstocks
Coconut and RSPO-certified palm kernel oil face weather disruptions and competing biodiesel demand. Galaxy Surfactants highlighted fatty-alcohol inflation in its FY2026 results, a signal of near-term margin pressure. Chinese capacity expansions from Guangzhou Tinci will ease constraints, yet plantation lead times of 5-7 years imply that volatility persists.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Water-Less "Solid Beauty" Formats
- Premium Pet-Grooming Formulations Uptake
- Foaming and Viscosity Limitations in High-pH Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Chips/flakes captured 48.12% of the Sodium Lauroyl Isethionate market share in 2025 because they dissolve quickly and compress cleanly into bars without dusting. Syndet manufacturers value low-moisture, uniform particle size to reduce bar cracking during storage, reinforcing chips/flakes as the dominant form. Powder demand is improving inside dry shampoo bases, where micronized grades mix with starches for rinse-free scalp refreshment. Pilot Chemical is debottlenecking U.S. sulfonation to supply flexible particle-size grades, indicating producer responsiveness.
Granules, while currently smaller, are projected to post the highest 5.66% CAGR during the forecast period (2026-2031) as beauty brands launch refill powders that consumers rehydrate at home, leveraging granules' flowability in automated filling lines. The Sodium Lauroyl Isethionate market thus shifts toward formats that balance processing ease with downstream consumer experience. Clariant's acquisition of Lucas Meyer Cosmetics in 2024 accelerates the development of granule-compatible emulsifier systems, showing how form factor strategy has become a competitive lever.
Geography Analysis
Asia-Pacific generated 43.45% of 2025 revenue and will rise at a 5.86% CAGR through 2031. Chinese producers benefit from cost-effective lauric-acid chains and captive ethylene oxide, while India scales alkoxylate capacity to serve both domestic and export markets. Guangzhou Tinci recorded a 181.4% profit surge in 2025, underscoring regional momentum. Japan and South Korea push early adoption of bio-based isethionates, encouraged by Kao's Bio IOS platform that eliminates dioxane and cuts carbon footprint.
North America is the regulatory bellwether. New York's 1 ppm dioxane cap and the U.S. EPA's PFAS restrictions propel surfactant reformulation, directing formulators to isethionate's inherently low contaminant profile. The U.S. home and laundry sector is on track to reach USD 60.9 billion by 2030, and solid formats are taking an outsized slice as retailers rearrange shelf space. Pilot Chemical's Middletown expansion, which more than doubles AOS output, shows how U.S. suppliers hedge with multiple sulfate-free chemistries.
Europe follows strict REACH and RSPO-linked procurement. German, French, and U.K. beauty houses require full-supply-chain traceability, favoring producers with COSMOS certification. Clariant's Daya Bay lines meet these criteria and ship annular quantities to European brands. South America and the Middle East and Africa remain smaller but attractive; Brazilian oleochemical projects and Saudi incentives for downstream surfactants promise incremental opportunities for the sodium lauroyl isethionate market.
- BASF
- Clariant
- Galaxy
- Guangzhou Tinci Materials Technology Co., Ltd.
- Innospec
- Jilin Aegis Chemical Co., Ltd.
- Taiwan NJC Corp.
- Kao Corporation
- Indroma Ventures
- Lamberti S.p.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising penetration in personal-care and cosmetics
- 4.2.2 Rapid adoption in baby-care cleansing bars
- 4.2.3 Shift toward water-less "solid beauty" formats
- 4.2.4 Premium pet-grooming formulations uptake
- 4.2.5 Bio-based isethionate synthesis lowering carbon footprint
- 4.3 Market Restraints
- 4.3.1 Tight supply of high-purity fatty-acid feedstocks
- 4.3.2 Foaming and viscosity limitations in high-pH systems
- 4.3.3 Potential re-classification risk under micro-plastics rules
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Form
- 5.1.1 Powder
- 5.1.2 Granules
- 5.1.3 Chips/Flakes
- 5.2 By Application
- 5.2.1 Hair-Care
- 5.2.2 Skin-Care
- 5.2.3 Cleaning Products
- 5.2.4 Other Applications (Baby Care, Pet Grooming, and More)
- 5.3 By End-use Industry
- 5.3.1 Personal-Care and Cosmetics
- 5.3.2 Household and Institutional Cleaning
- 5.3.3 Other End-user Industries (Healthcare and Pharmaceuticals, and More)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 Japan
- 5.4.1.3 India
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 BASF
- 6.4.2 Clariant
- 6.4.3 Galaxy
- 6.4.4 Guangzhou Tinci Materials Technology Co., Ltd.
- 6.4.5 Innospec
- 6.4.6 Jilin Aegis Chemical Co., Ltd.
- 6.4.7 Taiwan NJC Corp.
- 6.4.8 Kao Corporation
- 6.4.9 Indroma Ventures
- 6.4.10 Lamberti S.p.A.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

