PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2063573

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2063573
Microsurgery Robot - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the microsurgery robot market size is projected to expand from USD 1.8 billion in 2025 and USD 2.10 billion in 2026 to USD 4.10 billion by 2031, registering a CAGR of 14.29% between 2026 to 2031.
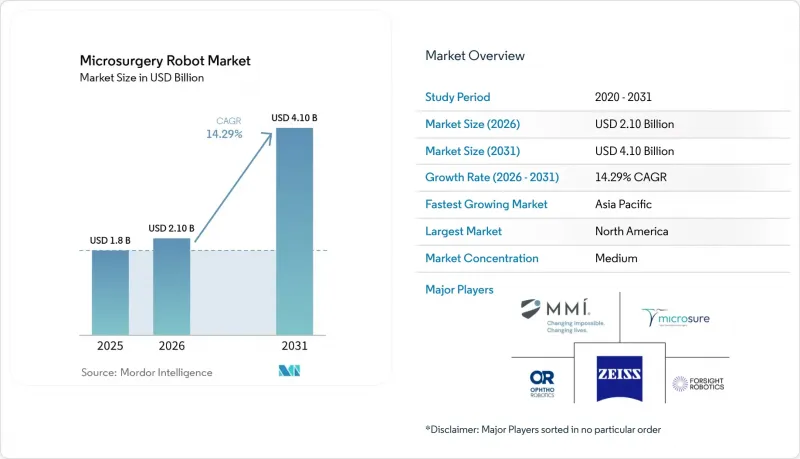
This report is Segmented by Clinical Application (Oncology, Reconstructive, Ophthalmology, ENT, Other), Technology (Teleoperated, Co-Manipulated, Semi-Autonomous), End-User (Academic Centers, Specialty Hospitals, Ascs, Community Hospitals), and Geography (North America, Europe, Asia-Pacific, MEA, South America). Market Forecasts are Provided in Value (USD).
Global Microsurgery Robot Market Trends and Insights
Rising Lymphedema Burden and Demand for Lymphatic and Microvascular Reconstruction
Lymphedema affects 250 million people worldwide, including 10 million in the United States . Lymphovenous anastomosis reduces limb volume by 14.26% at one year and lets nearly half of the patients taper compression garments. Robots that scale hand motion 10:1 or 20:1 permit general plastic surgeons to match fellowship-trained outcomes, and proficiency arrives in 15 robotic cases versus 40 manual cases. Demand is reinforced by the incidence of breast cancer-related lymphedema as survivorship lengthens.
CE-Marked Purpose-Built Microsurgery Robots Enabling Motion Scaling and Tremor Filtration in Sub-Millimeter Anastomoses
European centers gained a three-year head start after Symani and MUSA secured CE marks in 2021-2022, logging more than 900 clinical cases by 2025. Motion scaling converts a 10-mm hand move into a 1-mm instrument motion, and Kalman filters delete tremor frequencies above 8 Hz, cutting positional variance by up to 90% . Classifying these robots as assistive rather than autonomous devices eased reimbursement talks with European payers.
High Capital Cost, Setup Time, and Uncertain Reimbursement Pathways in Early-Stage Indications
Systems list from USD 500,000 to USD 2.5 million, excluding yearly service contracts that approach USD 100,000. Symani setup consumes up to one hour, cutting a daily block by one case and diluting ASC economics. CPT codes cover lymphatic work yet offer no uplift for robotic technique, so hospitals self-fund the delta while ENT and neurovascular indications lack any code.
Other drivers and restraints analyzed in the detailed report include:
- Clinical Validation in Ophthalmic and ENT Microsurgery Expanding Addressable Procedures
- Digitization of Open Microsurgery Workflows
- Regulatory Stringency and Need for Large-Scale, Multi-Center Outcomes Evidence
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Oncology procedures held 23.18% of the 2025 microsurgery robot market share, reflecting complex free-flap reconstruction that demands multiple supermicrosurgical anastomoses. Reconstructive work is forecast to expand at a 16.56% CAGR, lifting the microsurgery robot market size for this segment as lymphedema cases climb.
Hospitals view reconstructive indications as a volume engine because each breast cancer survivor represents a long-term candidate for lymphovenous bypass. Meanwhile, ophthalmology adoption is accelerating through gene-therapy delivery, the first ophthalmic use case to prove clear clinical benefit. Cardiovascular and gastrointestinal adoption remains muted because their vessel diameters do not require sub-millimeter accuracy.
Geography Analysis
North America held 45.18% of 2025 revenue. Early CPT coding and the April 2024 FDA clearance of Symani created commercial momentum, and private insurers now approve lymphovenous anastomosis when performed robotically on a case-by-case basis. Canada's single-payer system moves more slowly because capital budgets are locked years ahead, while Mexico's private hospitals lure U.S. patients at 40% lower procedure cost.
Asia-Pacific is forecast to expand at the fastest 17.77% CAGR as Chinese tertiary hospitals bought 74 units in the first half of 2025, worth more than 700 million RMB or about USD 96 million. Japan shows strong academic use, with 162 robotic pancreatoduodenectomy cases by mid-2025, but national reimbursement remains under review. South Korea and Australia provide targeted subsidies and recent regulatory clearances that open niche demand, although rural dispersion limits utilization outside major cities.
Europe contributed a significant share of the 2025 turnover after CE marks allowed earlier adoption. Germany, the United Kingdom, and France account for a notable share of regional installs, yet decentralized hospital governance and NHS budget tightening moderate growth. Post-market surveillance under MDR raises the cost of entry for smaller firms, though Germany's reimbursement parity between robotic and manual lymphatic surgery smooths hospital economics. Adoption in the Middle East, Africa, and South America remains less percentage due to limited reimbursement frameworks.
- AcuSurgical
- Bionaut Labs
- Brain Lab
- Carl Zeiss
- CASCINATION AG
- Collin Medical
- ForSight Robotics
- High Tech Campus Eindhoven
- iotaMotion
- Keranova
- LENSAR Inc.
- Medical Microinstruments, Inc.
- MicroSure B.V.
- NDR Medical Technology
- Ophthorobotics AG
- XACT Robotics
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Lymphedema Burden and Demand for Lymphatic and Microvascular Reconstruction
- 4.2.2 CE-Marked Purpose-Built Microsurgery Robots Enabling Motion Scaling and Tremor Filtration in Sub-Millimeter Anastomoses
- 4.2.3 Clinical Validation in Ophthalmic and ENT Microsurgery, Expanding Addressable Procedures
- 4.2.4 Digitization Of Open Microsurgery Workflows
- 4.2.5 Surgeons' Skill Bottleneck in Super microsurgery Accelerating Hospitals' Shift to Robotic Platforms
- 4.2.6 Gene/Cell Therapy Delivery Use-Cases Requiring Robotic Precision
- 4.3 Market Restraints
- 4.3.1 High Capital Cost, Setup Time, And Uncertain Reimbursement Pathways in Early-Stage Indications
- 4.3.2 Regulatory Stringency and Need for Large-Scale, Multi-Center Outcomes Evidence
- 4.3.3 Limited Instrument Ecosystems and Cross-Specialty Workflow Integration
- 4.3.4 Credentialing/Training Standardization Gaps Slow Multi-Site Scale-Up
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Clinical Application
- 5.1.1 Oncology surgery
- 5.1.2 Urology surgery
- 5.1.3 Obstetrics and gynecology surgery
- 5.1.4 Micro anastomosis
- 5.1.5 Reconstructive surgery
- 5.1.6 ENT surgery
- 5.1.7 Gastrointestinal surgery
- 5.1.8 Cardiovascular surgery
- 5.1.9 Neurovascular surgery
- 5.1.10 Ophthalmology surgery
- 5.1.11 Other applications
- 5.2 By Technology
- 5.2.1 Teleoperated multi-arm microsurgical systems
- 5.2.2 Co-manipulated/handheld robotic assist systems
- 5.2.3 Semi-autonomous image-guided micro-robots
- 5.3 By End-user
- 5.3.1 Academic medical centers
- 5.3.2 Specialty hospitals
- 5.3.3 Ambulatory surgical centers
- 5.3.4 Community / General hospitals
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 AcuSurgical
- 6.3.2 Bionaut Labs
- 6.3.3 Brainlab
- 6.3.4 Carl Zeiss Meditec AG
- 6.3.5 CASCINATION AG
- 6.3.6 Collin Medical
- 6.3.7 ForSight Robotics
- 6.3.8 High Tech Campus Eindhoven
- 6.3.9 iotaMotion Inc.
- 6.3.10 Keranova
- 6.3.11 LENSAR Inc.
- 6.3.12 Medical Microinstruments, Inc.
- 6.3.13 MicroSure B.V.
- 6.3.14 NDR Medical Technology
- 6.3.15 Ophthorobotics AG
- 6.3.16 XACT Robotics
7 Market Opportunities & Future Outlook
- 7.1 White-space & unmet-need assessment

