PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2065575

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2065575
GitOps And Infrastructure As-a-Code (IaC) Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the gitOps and Infrastructure as Code software market size is expected to increase from USD 1.96 billion in 2025 to USD 2.39 billion in 2026 and reach USD 6.40 billion by 2031, growing at a CAGR of 21.8% over 2026-2031.
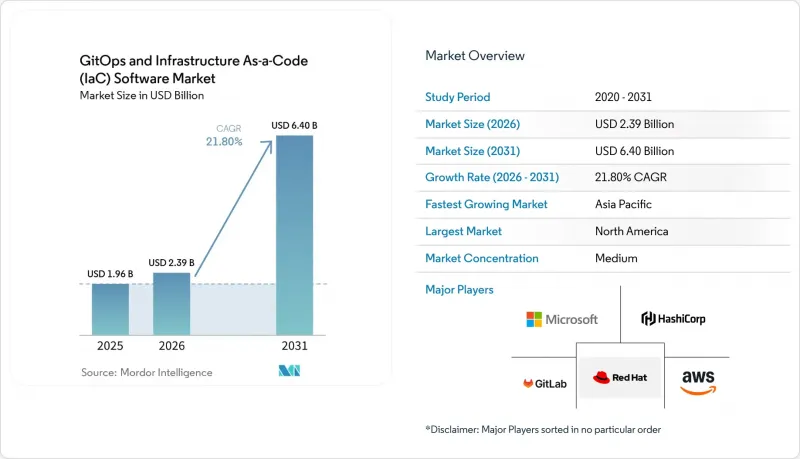
This report is Segmented by Deployment Model (SaaS, Self-Hosted, and More), Organization Size (Small and Medium Enterprises, and Large Enterprises), End-User Industry (IT and Telecommunications, Healthcare and Life Sciences, Manufacturing, and More), Cloud Environment (Public Cloud, and Private Cloud), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global GitOps And Infrastructure As-a-Code (IaC) Software Market Trends and Insights
Cloud-Native Adoption by Enterprises
Kubernetes reached production adoption in 82% of cloud-native organizations by 2025, anchoring GitOps as the de facto delivery mechanism for containerized workloads. Financial institutions exemplify this shift: Morgan Stanley runs Flux across more than 500 clusters, embedding GitOps directly into core trading infrastructure. In telecommunications, NTT DOCOMO cut 5G core build time by 80% by pairing GitOps with AI-driven automation on AWS. Graduation of ArgoCD and Flux from the CNCF imparted enterprise-grade trust through extensive security audits and scalability tests. Consequently, 97% of ArgoCD users now operate the tool in production, and 42% manage more than 500 applications per instance.
Shift Toward DevSecOps Pipelines
Regulated enterprises are moving security checks inside declarative pipelines, reducing manual review cycles. Pulumi's December 2025 release added unified state management for Terraform and OpenTofu, enabling consolidated policy-as-code enforcement. GitLab version 18.7 introduced secret validity scanning, detecting expired credentials before deployment. European banks accelerated adoption to satisfy DORA requirements, with Intesa Sanpaolo reporting a 70% cut in audit prep time using Cisco's GitOps-backed fabric controller. PCI-DSS automation blueprints have emerged, codifying payment-card controls as immutable infrastructure. Secrets management still lags because many teams rely on manual key rotation, highlighting the need for integrated vault solutions.
Skills Gap in Git-Centric Workflows
A 2024 U.K. task-force survey showed 41% of SMEs deem DevOps too complex and 35% lack adequate talent.Even organizations already using GitOps struggle: environment promotion emerged as the top operational headache in the July 2025 CNCF survey, with many teams scripting ad-hoc workflows. Managed ArgoCD on EKS, launched November 2025, cuts installation and upgrade toil, narrowing the skill gap for SMEs. Platform engineering teams further reduce friction by exposing self-service deployment portals that hide Git concepts, though this approach demands dedicated engineers and initial investment. Universities are now embedding Kubernetes and GitOps into curricula, suggesting the constraint will ease over the next two to three years.
Other drivers and restraints analyzed in the detailed report include:
- Rise of Multi-Cloud and Hybrid-Cloud Strategies
- Growing Compliance Automation Needs in Regulated Industries
- Security Concerns Over Pipeline Secrets Management
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hybrid patterns address the dual need for SaaS agility and on-premises control. Solutions captured 46.2% of 2025 revenue, illustrating a preference for integrated toolchains that wrap GitOps controllers with policy engines. The hybrid segment is forecast to register a 24.2% CAGR, outpacing pure SaaS, as regulated entities deploy SaaS control planes while running execution agents inside air-gapped virtual private clouds to protect classified data. FedRAMP clearance for Spacelift and the managed ArgoCD add-on from AWS exemplify how vendors are productizing this architecture. Large banks still favor self-hosted control planes to meet zero-trust mandates, but rising operating costs steer them toward partially hosted dashboards that offload upgrades and patches. The GitOps and Infrastructure as Code software market size for hybrid deployments is projected to expand in tandem with confidential computing trends that mandate in-country processing while permitting centralized governance.
Second-generation platforms now bundle compliance packs, drift detection, and policy-as-code templates, making them appealing to aerospace and defense contractors. In the public sector, procurement rules increasingly require proof that SaaS providers support privatized execution modes, propelling hybrid demand. Across manufacturing, edge clusters running Flux benefit from thin-footprint agents but still connect to central policy hubs, confirming that an endpoint-agnostic control plane is crucial. As a result, the GitOps and Infrastructure as Code software market continues to blur the once-rigid lines between deployment categories, leaving flexibility, not location, as the prime buying criterion.
Public cloud deployments represented 71.8% of 2025 revenue and are forecast to progress at a 23.6% CAGR. Native integrations drive momentum: AWS offers a one-click ArgoCD add-on, Azure bundles Flux into AKS, and Google ships Anthos Config Management. Private clouds remain prominent in finance and healthcare, where data residency pushes workloads onto self-hosted OpenShift clusters. Hybrid control planes now straddle both worlds, with Alibaba Cloud's ACK One orchestrating on-premises clusters in the same GitOps workflow as public cloud resources.
Flux's microcontroller architecture suits resource-constrained edge nodes, signaling that the GitOps and Infrastructure as Code software market share for on-premises deployments will not evaporate but will reposition toward edge and sovereign-cloud projects. Cross-plane reconciles multi-cloud state as custom Kubernetes resources, trimming the overhead of writing provider-specific IaC scripts. As public clouds commoditize managed GitOps, differentiation shifts to compliance features, latency-sensitive edge support, and AI-assisted rollout strategies.
Geography Analysis
North America controlled 33.6% of global revenue in 2025, buoyed by hyperscale cloud penetration and stringent DevSecOps mandates across banking and healthcare. FedRAMP-cleared SaaS platforms such as Spacelift widened federal uptake, and Harness leveraged its December 2025 USD 240 million funding to accelerate go-to-market across Fortune 500 accounts. Early adopters like Morgan Stanley and Capital One now treat GitOps as core infrastructure, validating enterprise maturity. Canada mirrors U.S. trends, while Mexican telecoms pilot GitOps for 5G roll-outs.
Asia-Pacific is the fastest-growing region, projected at a 25.8% CAGR. Japan's Tokyo Gas achieved a 30% cost reduction by combining ArgoCD with service mesh for hybrid workloads. Chinese state-owned enterprises deploy Flux in sovereign clouds to honor data localization laws, and Alibaba Cloud embeds GitOps in ACK One to manage multi-cluster estates. India's fintech community capitalizes on multi-cloud arbitrage, shifting workloads between AWS and Azure for pricing efficiency. Australia and New Zealand exhibit strong uptake in banking and government digitization projects.
Europe demonstrates robust growth driven by regulatory compliance. For instance, Intesa Sanpaolo achieved a 70% reduction in audit times by implementing automation aligned with the Digital Operational Resilience Act (DORA). This success is motivating other financial institutions across Germany and France to adopt similar strategies. The Middle East and Africa, along with South America, are emerging markets showing significant potential. These regions are witnessing growing interest as hyperscale cloud providers establish local data centers. The presence of these data centers not only reduces latency but also addresses compliance challenges, enabling businesses to operate more effectively within local regulatory frameworks. This development is expected to drive further adoption of advanced technologies and foster growth in these regions.
- HashiCorp Inc
- GitLab Inc
- Weaveworks Limited
- Red Hat Inc
- Amazon Web Services Inc
- Microsoft Corporation
- Google LLC
- Perforce Software Inc Puppet
- Chef Software Inc
- CloudBees Inc
- Circle Internet Services Inc
- Atlassian Corporation Plc
- GitHub Inc
- SUSE LLC
- Mirantis Inc
- Pulumi Corporation
- Spacelift Inc
- Harness Inc
- Humanitec GmbH
- JFrog Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cloud-native adoption by enterprises
- 4.2.2 Shift toward DevSecOps pipelines
- 4.2.3 Rise of multi-cloud and hybrid-cloud strategies
- 4.2.4 Growing compliance automation needs in regulated industries
- 4.2.5 Open-source community acceleration around GitOps controllers
- 4.2.6 Demand for immutable infrastructure in edge computing
- 4.3 Market Restraints
- 4.3.1 Skills gap in Git-centric workflows
- 4.3.2 Security concerns over pipeline secrets management
- 4.3.3 Toolchain fragmentation and interoperability issues
- 4.3.4 Limited ROI visibility for large legacy environments
- 4.4 Industry Value Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porters Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment Model
- 5.1.1 SaaS
- 5.1.2 Self Hosted
- 5.1.3 Hybrid
- 5.2 By Organization Size
- 5.2.1 Small and Medium Enterprises SMEs
- 5.2.2 Large Enterprises
- 5.3 By End User Industry
- 5.3.1 IT and Telecommunications
- 5.3.2 Banking Financial Services and Insurance BFSI
- 5.3.3 Healthcare and Life Sciences
- 5.3.4 Retail and E Commerce
- 5.3.5 Manufacturing
- 5.3.6 Government and Public Sector
- 5.3.7 Other End User Industries
- 5.4 By Cloud Environment
- 5.4.1 Public Cloud
- 5.4.2 Private Cloud
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Egypt
- 5.5.6.3 Nigeria
- 5.5.6.4 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles includes Global Level Overview Market Level Overview Core Segments Financials as available Strategic Information Market Rank Share Products and Services Recent Developments
- 6.4.1 HashiCorp Inc
- 6.4.2 GitLab Inc
- 6.4.3 Weaveworks Limited
- 6.4.4 Red Hat Inc
- 6.4.5 Amazon Web Services Inc
- 6.4.6 Microsoft Corporation
- 6.4.7 Google LLC
- 6.4.8 Perforce Software Inc Puppet
- 6.4.9 Chef Software Inc
- 6.4.10 CloudBees Inc
- 6.4.11 Circle Internet Services Inc
- 6.4.12 Atlassian Corporation Plc
- 6.4.13 GitHub Inc
- 6.4.14 SUSE LLC
- 6.4.15 Mirantis Inc
- 6.4.16 Pulumi Corporation
- 6.4.17 Spacelift Inc
- 6.4.18 Harness Inc
- 6.4.19 Humanitec GmbH
- 6.4.20 JFrog Ltd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White Space and Unmet Need Assessment

