PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2065589

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2065589
Hybrid Work Hardware - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the hybrid work hardware market size is expected to increase from USD 28.50 billion in 2025 to USD 31.80 billion in 2026 and reach USD 52.40 billion by 2031, growing at a CAGR of 10.50% over 2026-2031.
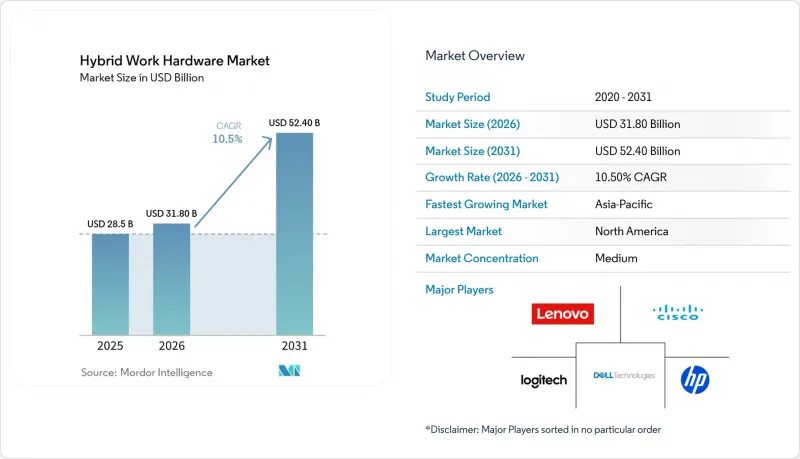
This report is Segmented by Product Type (Computing Devices, Peripherals and Accessories, Collaboration Hardware, and More), Organization Size (Large Enterprises, and Small and Medium-Sized Enterprises), End-User Industry (IT and Telecommunication, BFSI, and More), Distribution Channel (Offline, and Online), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Hybrid Work Hardware Market Trends and Insights
Proliferation of Bring Your Own Meeting Policies
BYOM policies shorten hardware refresh cycles because employees can connect personal laptops to USB speakerphones and auto-framing cameras without proprietary codecs, bypassing complex IT provisioning. Owl Labs reported that 63% of hybrid workers in 2025 favored BYOM layouts that mirror familiar desktop interfaces. The preference aligns with the 12.8% CAGR expected for conference-room systems as firms replace fixed boxes with software-agnostic soundbars. Samsung, Cisco, and Logitech countered the trend in February 2026 by unveiling pre-integrated bundles that promise zero-touch deployment, an ecosystem play that trades openness for administrative simplicity. Organizations embracing modular BYOM still gain leverage when renegotiating SaaS contracts because hardware remains decoupled from licensing terms, preserving optionality in the 2028-2030 refresh window.
Surge in Video Conferencing Adoption Post Pandemic
Although webcam penetration peaked by 2024, spending persists as first-wave endpoints reach end of life and users demand 4K optics, neural noise suppression, and edge-based analytics. Logitech's Rally AI cameras, launched in January 2026, embed dedicated processors that execute speaker tracking locally, mitigating cloud round-trip latency and satisfying data-sovereignty mandates in healthcare and finance. University lecture-hall retrofits costing USD 8,000-15,000 per room underpin education's double-digit CAGR, with ceiling-mounted arrays enabling asynchronous playback for students in distant time zones. Appliance-style offerings, like Crestron's Collab Compute, package compute, touch control, and licensing into one SKU, reducing bill-of-materials complexity and accelerating deployment CRESTRON.COM.
Cybersecurity and Data Privacy Concerns in Collaborative Devices
Always-on cameras and microphones expand the attack surface that malicious actors exploit through firmware implants and man-in-the-middle attacks. AVIXA's 2024 survey indicated 58% of IT leaders delayed hardware rollouts until vendors proved ISO 27001-certified manufacturing and secure boot chains. Enterprises now specify Trusted Platform Modules and auto-patch utilities, adding USD 100-200 per endpoint yet averting potential GDPR fines equal to 4% of annual turnover. The trend elevates incumbent brands that publish CVE disclosures and fund bug-bounty programs, while penalizing white-box entrants with opaque supply chains.
Other drivers and restraints analyzed in the detailed report include:
- Upgrades to Conference Rooms for Hybrid Collaboration
- Rising Demand for AI-Powered Meeting Equity Features
- Budget Constraints for Small and Medium Businesses
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hybrid Work Hardware market size leadership in 2025 rested with computing devices, which held a 32.25% share, yet video conferencing systems are poised for faster expansion at a 12.8% CAGR through 2031. Computing endpoints have commoditized, with average business-laptop prices dropping 8% in 2025 as component spec sheets homogenized. Peripherals bridge the gap, exemplified by Jabra PanaCast's on-device DSPs that reduce cloud latency, while networking and connectivity hardware, such as Wi-Fi 6E routers, ensure bandwidth symmetry for multi-stream meetings. Collaboration boards and interactive whiteboards are ascending in education and healthcare, where touch-enabled annotation brings remote cohorts into room-based workflows. Ancillary categories like ergonomic lighting kits grow more slowly but round out holistic hybrid-work bundles.
Across the forecast horizon, enterprises will redirect capital from refreshed notebooks toward conference-room modernization, a shift accelerated by BYOM, as one smart bar can serve an entire team rather than multiple laptops per employee. Hybrid Work Hardware market share is therefore poised to rebalance toward shared-space infrastructure, especially as vendors collapse compute, control, and connectivity into single SKUs such as Crestron's Collab Compute. The greater margin resident in integrated room solutions grants vendors budget to embed neural accelerators, effectively raising the technology bar for late-comer competitors.
The hybrid Work Hardware market size is skewed toward large enterprises, with 68.46% in 2025, leveraging global contracts, bulk discounts, and in-house AV teams. Small and medium-sized enterprises, while resource-constrained, are projected to post a 12.24% CAGR, gradually narrowing the gap through 2031. The inflection stems from USB-based bars that require no specialist integrators, allowing office managers to install endpoints in under an hour. Financing models also level the playing field with HP, Dell, and Lenovo, which are now pricing laptops, monitors, and peripherals as monthly subscriptions, aligning with SMB cash-flow realities.
Large enterprises will continue controlling the premium tier, negotiating bundles of hardware, SaaS licenses, and five-year managed-services addenda. However, many have begun adopting flexible procurement practices that mirror consumer e-commerce, demanding transparent SKU-level pricing and next-day delivery, similar to what SMBs enjoy. As BYOM proliferates, the support burden falls from centralized IT to employees, reducing the staffing advantage historically enjoyed by large firms, although governance requirements such as zero-trust device posture still favor well-resourced organizations.
Geography Analysis
North America accounted for 36.46% of the Hybrid Work Hardware market revenue in 2025, underpinned by Fortune 500 refresh cycles and tax deductions for home-office equipment. The region benefits from mature fiber backbones and pervasive Wi-Fi 6E rollouts, ensuring that full-resolution 4K streams rarely downgrade. State and provincial grants further subsidize equipment for public-sector employees, broadening addressable demand beyond corporate headquarters. Yet cybersecurity regulations, such as the California Privacy Rights Act, increase compliance costs, nudging buyers toward established brands with documented vulnerability disclosure programs.
Asia-Pacific is on course for a 12.62% CAGR, the fastest worldwide. Government-funded 5G expansion in Singapore, India, and Japan removes latency bottlenecks and supports real-time, multi-participant whiteboarding. India's Production-Linked Incentive scheme for electronics attracts contract manufacturing from Logitech and Yealink, lowering import duties and shortening logistical lead times. Japanese employers, facing demographic labor shortages, embrace hybrid work models to tap non-urban talent pools; this shift drives high demand for compact, apartment-friendly conferencing bars rather than large-format displays prevalent in U.S. home offices. Simultaneously, local brands leverage linguistic localization and culturally specific UI cues to edge out Western incumbents.
Europe's growth lags because environmental mandates increase compliance costs. The November 2025 sunset of the RoHS exemption for cadmium-based quantum dots forced vendors to invest USD 50-100 per display in re-qualification testing. Middle Eastern buyers shift toward hardware-encrypted drives to meet national data-sovereignty laws, a behavior Kingston flagged in its November 2025 regional storage report. Africa remains nascent due to patchy broadband, yet pilot programs in South Africa and Kenya prove that solar-powered conference kits can function on sub-5 Mbps links, hinting at latent upside once infrastructure matures. South American adoption fluctuates with currency volatility; Brazil's hybrid-work incentives spur demand in bull cycles, whereas import restrictions in Argentina create gray-market channels for refurbished gear.
- Logitech International S.A.
- Cisco Systems, Inc.
- HP Inc.
- Lenovo Group Limited
- Dell Technologies Inc.
- Microsoft Corporation
- Apple Inc.
- Crestron Electronics, Inc.
- Barco NV
- GN Audio A/S (Jabra)
- AVer Information Inc.
- AVerMedia Technologies, Inc.
- Konftel AB
- Vaddio (Legrand AV Inc.)
- Shure Incorporated
- EPOS Audio A/S
- Bose Corporation
- DTEN, Inc.
- Yealink Network Technology Co., Ltd.
- Maxhub (Guangzhou Shiyuan Electronic Technology Company Limited)
- ClearOne Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of Bring Your Own Meeting (BYOM) Policies Among Enterprises
- 4.2.2 Surge in Video Conferencing Adoption Post Pandemic
- 4.2.3 Upgrades to Conference Rooms for Hybrid Collaboration
- 4.2.4 Expansion of High-Speed Broadband and 5G Networks
- 4.2.5 Rising Demand for AI-Powered Meeting Equity Features
- 4.2.6 Tax Incentives for Remote Work Equipment in Select Countries
- 4.3 Market Restraints
- 4.3.1 Cybersecurity and Data Privacy Concerns in Collaborative Devices
- 4.3.2 Budget Constraints for Small and Medium Businesses
- 4.3.3 Environmental Regulations Limiting Use of Certain Display Materials
- 4.3.4 Component Shortages in Audio Chipsets Affecting Lead Times
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Industry Attractiveness - Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Computing Devices
- 5.1.2 Peripherals and Accessories
- 5.1.3 Collaboration Hardware
- 5.1.4 Video Conferencing and Meeting Room Systems
- 5.1.5 Networking and Connectivity Hardware
- 5.1.6 Other Product Types
- 5.2 By Organization Size
- 5.2.1 Large Enterprises
- 5.2.2 Small and Medium-Sized Enterprises
- 5.3 By End-user Industry
- 5.3.1 IT and Telecommunication
- 5.3.2 BFSI
- 5.3.3 Healthcare and Lifesciences
- 5.3.4 Retail and Consumer Goods
- 5.3.5 Education
- 5.3.6 Government and Public Sector
- 5.3.7 Manufacturing
- 5.3.8 Media and Entertainment
- 5.3.9 Other Industry Verticals
- 5.4 By Distribution Channel
- 5.4.1 Offline
- 5.4.2 Online
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Kenya
- 5.5.6.4 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Logitech International S.A.
- 6.4.2 Cisco Systems, Inc.
- 6.4.3 HP Inc.
- 6.4.4 Lenovo Group Limited
- 6.4.5 Dell Technologies Inc.
- 6.4.6 Microsoft Corporation
- 6.4.7 Apple Inc.
- 6.4.8 Crestron Electronics, Inc.
- 6.4.9 Barco NV
- 6.4.10 GN Audio A/S (Jabra)
- 6.4.11 AVer Information Inc.
- 6.4.12 AVerMedia Technologies, Inc.
- 6.4.13 Konftel AB
- 6.4.14 Vaddio (Legrand AV Inc.)
- 6.4.15 Shure Incorporated
- 6.4.16 EPOS Audio A/S
- 6.4.17 Bose Corporation
- 6.4.18 DTEN, Inc.
- 6.4.19 Yealink Network Technology Co., Ltd.
- 6.4.20 Maxhub (Guangzhou Shiyuan Electronic Technology Company Limited)
- 6.4.21 ClearOne Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

