PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2072451

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2072451
Orthodontic Supplies - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the orthodontic supplies market size is estimated at USD 11.85 billion in 2026, and is expected to reach USD 19.16 billion by 2031, at a CAGR of 10.08% during the forecast period (2026-2031).
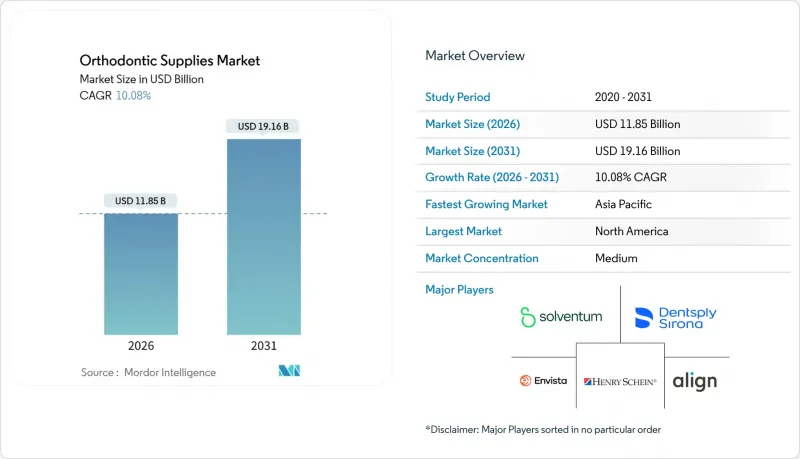
This report is Segmented by Product Type (Brackets, Archwires, Bands & Buccal Tubes, Ligatures, Anchorage Appliances, Clear Aligners, Retainers, Adhesives, Others), Material (Metal, Ceramic, and More), Patient Group (Children, and More), End-User (Hospitals, Dental Clinics, and More), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Orthodontic Supplies Market Trends and Insights
Growing Prevalence of Malocclusions
WHO data frame malocclusion as a silent public-health burden, yet access barriers limit treatment uptake. Dental associations in India and Indonesia now run education drives that shorten diagnosis-to-treatment timelines, translating latent need into active case starts. Vendors with tiered portfolios-low-cost metal brackets for mass markets and premium ceramic options for affluent consumers-capture the resulting volume. Early intervention guidelines for children aged 7-9 extend therapeutic windows, raising lifetime spend per patient. No jurisdiction mandates population-level screening, so private-sector efforts remain central to demand creation.
Technological Advances in Clear Aligners
Innovation has shifted from materials to software. Align Technology's AI CADe tool, cleared in 2025, auto-plots radiographic landmarks and cuts planning time 40%. Self-ligating brackets reduce friction and trim appointment frequency, resonating with DSOs that maximize chair utilization. Regulatory bodies have opened clear-aligner indications to complex pediatric expansion, displacing brackets in a former stronghold. Vendors lacking integrated digital workflows face commodity pricing as orthodontists adopt platforms that save labor.
High Treatment Cost and Limited Insurance Cover
Typical U.S. dental plans cap orthodontic benefits near USD 2,000, leaving households to finance the remaining USD 3,000-5,000. The American Association of Orthodontists noted rising default rates on payment plans as inflation erodes budgets. In India and Brazil, therapy can equal several months of income, restricting uptake to urban elites. DTC aligner brands undercut clinic prices by up to 50%, yet regulator crackdowns on supervision gaps may reduce their edge.
Other drivers and restraints analyzed in the detailed report include:
- AI-Powered Chair-Side Customization
- Expansion of Dental Service Organizations
- Regulatory Scrutiny of Direct-to-Consumer Aligners
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Brackets retained 33.52% of orthodontic supplies market in 2025, favored for severe biomechanical movements that aligners still find challenging. Clear aligners, however, are growing at a 14.25% CAGR as adults prioritize aesthetics and chair-side 3D printing supports on-demand trays. Archwires and ligatures remain high-volume consumables but face price pressure as alloy recipes standardize. Retainers produce steady annuity revenue after active treatment, and newer thermoplastic versions improve comfort. Adhesive bond failures triggered 2024 recalls, prompting clinics to favor suppliers with robust quality-assurance data.
Digital ecosystems tilt revenue toward software subscriptions bundled with aligner deliveries. Practices that integrate scanners, AI-planning, and remote monitoring become locked into vendor platforms, raising switching costs. Specialty appliances such as temporary anchorage devices maintain high margins despite lower volume because they solve complex cases. Suppliers covering the full treatment continuum-from early interceptive devices to long-term retention-are positioned to cross-sell and defend share.
Stainless steel held 44.63% of orthodontic supplies market size in 2025 because of durability and affordability. Ceramic brackets advance at a 13.51% CAGR as patients pay premiums for tooth-colored fixtures that resist staining. Nickel-titanium superelastic wires remain indispensable, yet 60-70% of global production is concentrated in China, driving supply-chain risk. Polymer blends dominate clear aligners, with proprietary films tuned for force delivery and comfort. Bio-resorbable composites developed in Europe eliminate removal appointments and enhance sustainability credentials.
Asian suppliers invest heavily in advanced ceramics and polymers, narrowing technology gaps with Western incumbents. Nonetheless, navigating FDA and CE clearances still favors companies with established regulatory infrastructure and ISO 13485-certified plants.
Complete Report Scope:
- By Product Type
- Brackets
- Archwires
- Bands & Buccal Tubes
- Ligatures
- Anchorage Appliances
- Clear Aligners
- Retainers
- Adhesives
- Others
- By Material
- Metal
- Ceramic
- Nickel-Titanium
- Stainless Steel
- Polymer/Plastics
- Bio-resorbable Materials
- By Patient Group (Age)
- Children (<=12 yrs)
- Teenagers (13-19 yrs)
- Adults (20-40 yrs)
- Older Adults (>40 yrs)
- By End-User
- Hospitals
- Dental Clinics
- Orthodontic & Dentofacial Orthopedic Clinics
- Academic & Research Institutes
- Direct-to-Consumer / At-home
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America produced 36.44% of global revenue in 2025. High insurance penetration offsets a portion of orthodontic costs, and DSOs accelerate consolidation. Vendors compete on service-level performance, volume rebates, and integrated digital platforms tailored to large practice networks. Europe is mature but stable, with Germany, France, and the United Kingdom advancing bio-resorbable materials in line with sustainability goals. Medical Device Regulation compliance raises operating cost yet ensures product safety, favoring well-capitalized suppliers.
Asia-Pacific is the growth engine, forecast at a 13.01% CAGR through 2031. China benefits from healthcare investment in Tier-2 and Tier-3 cities and rising disposable income that supports clear-aligner uptake. India's urban clinics adopt aligners aggressively, although rural affordability gaps persist. Japan and South Korea showcase mature digital dentistry ecosystems, where AI planning and remote monitoring are routine. Australia aligns regulatory frameworks with FDA norms, simplifying trans-Pacific platform transfers. Suppliers succeed by pairing local manufacturing or distribution partners with cloud-based treatment planning that bypasses infrastructure constraints.
The Middle East and Africa remain nascent. Demand concentrates in Gulf Cooperation Council states-United Arab Emirates and Saudi Arabia-where medical tourism and expatriate populations support premium care. South Africa leads sub-Saharan adoption, yet income disparity restrains wider market growth. Latin America shows cyclical demand driven by macroeconomic volatility; Brazil and Argentina deliver sizable volumes but require localized pricing strategies to navigate currency swings. Vendors mitigate regional risks through flexible payment options and modular product configurations.
- Align Technology
- American Orthodontics
- Angelalign Technology
- DB Orthodontics
- Dentaurum
- Dentsply Sirona
- Envista Holdings
- Forestadent
- G&H Orthodontics
- Geniova
- Great Lakes Dental Technologies
- Henry Schein Orthodontics
- Modern Orthodontics
- Rocky Mountain Orthodontics
- SCHEU-DENTAL
- Shenzhen Smartee Denti-Technology
- Solventum
- Straumann Group
- TP Orthodontics
- Ultradent Products
- Zhejiang Protect Orthodontic Appliance
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Prevalence of Malocclusions
- 4.2.2 Rising Disposable Income & Demand for Aesthetics
- 4.2.3 Technological Advances in Clear Aligners/Self-Ligating Braces
- 4.2.4 Expansion Of Dental Service Organizations
- 4.2.5 AI-Powered Digital Chair-Side Customization
- 4.2.6 Eco-Friendly Bio-Resorbable Materials
- 4.3 Market Restraints
- 4.3.1 High Treatment Cost & Limited Insurance Cover
- 4.3.2 Product Recalls & Adverse Effects
- 4.3.3 Supply-Chain Reliance on Niche Alloy Suppliers
- 4.3.4 Regulatory Scrutiny of Direct-To-Consumer Aligners
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Product Type
- 5.1.1 Brackets
- 5.1.2 Archwires
- 5.1.3 Bands & Buccal Tubes
- 5.1.4 Ligatures
- 5.1.5 Anchorage Appliances
- 5.1.6 Clear Aligners
- 5.1.7 Retainers
- 5.1.8 Adhesives
- 5.1.9 Others
- 5.2 By Material
- 5.2.1 Metal
- 5.2.2 Ceramic
- 5.2.3 Nickel-Titanium
- 5.2.4 Stainless Steel
- 5.2.5 Polymer/Plastics
- 5.2.6 Bio-resorbable Materials
- 5.3 By Patient Group (Age)
- 5.3.1 Children (<=12 yrs)
- 5.3.2 Teenagers (13-19 yrs)
- 5.3.3 Adults (20-40 yrs)
- 5.3.4 Older Adults (>40 yrs)
- 5.4 By End-User
- 5.4.1 Hospitals
- 5.4.2 Dental Clinics
- 5.4.3 Orthodontic & Dentofacial Orthopedic Clinics
- 5.4.4 Academic & Research Institutes
- 5.4.5 Direct-to-Consumer / At-home
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 France
- 5.5.2.3 United Kingdom
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Align Technology
- 6.3.2 American Orthodontics
- 6.3.3 Angelalign Technology
- 6.3.4 DB Orthodontics
- 6.3.5 Dentaurum
- 6.3.6 Dentsply Sirona
- 6.3.7 Envista Holdings
- 6.3.8 Forestadent
- 6.3.9 G&H Orthodontics
- 6.3.10 Geniova
- 6.3.11 Great Lakes Dental Technologies
- 6.3.12 Henry Schein Orthodontics
- 6.3.13 Modern Orthodontics
- 6.3.14 Rocky Mountain Orthodontics
- 6.3.15 SCHEU-DENTAL
- 6.3.16 Shenzhen Smartee Denti-Technology
- 6.3.17 Solventum
- 6.3.18 Straumann Group
- 6.3.19 TP Orthodontics
- 6.3.20 Ultradent Products
- 6.3.21 Zhejiang Protect Orthodontic Appliance
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

