PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2072570

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2072570
Herbal Medicinal Products - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the herbal medicinal products market size is estimated at USD 263.84 billion in 2026, and is expected to reach USD 396.07 billion by 2031, at a CAGR of 8.46% during the forecast period (2026-2031).
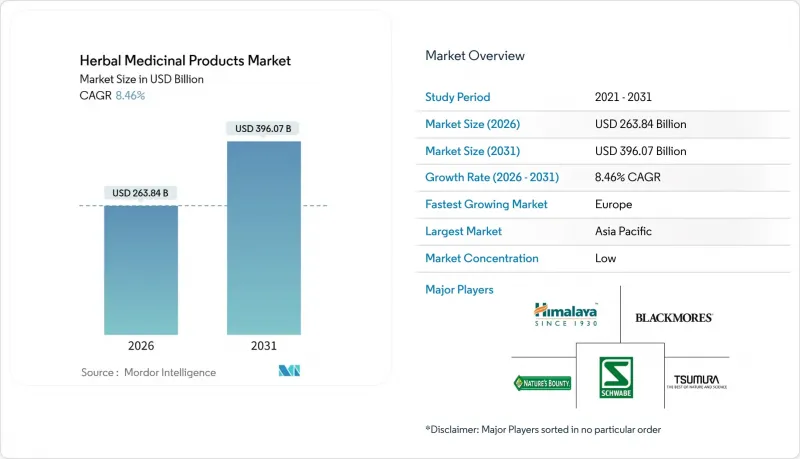
This report is Segmented by Product Type (Herbal Pharmaceuticals, Herbal Dietary Supplements, and More), Source (Leaves, Roots & Rhizomes, and More), Form (Tablets & Capsules, Powders & Granules, and More), Distribution Channel (Hospital & Retail Pharmacies, and More), Medicinal Plant Type (Aloe Vera, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Herbal Medicinal Products Market Trends and Insights
Consumers worldwide have shifted toward natural, plant-based OTC remedies
Global sales data from 2023 showed resilient growth for botanical supplements, even amid economic uncertainty, highlighting sustained demand across age groups seeking preventive wellness. Expanding scientific validation of ingredients such as psyllium and beetroot reinforces purchase confidence. European consumer behavior mirrors this trend as regulatory structures encourage evidence-based claims without restricting traditional knowledge. The ongoing behavioral pivot underpins steady expansion of the herbal medicinal products market.
Progressive regulators are shortening launch timelines
Revised New Dietary Ingredient Notification guidance in 2024 allows companies to reference Master Files, cutting development cycles by up to two years. China's Traditional Chinese Medicine Regulatory Science initiative employs AI for faster dossier evaluation, broadening opportunities for small innovators. While resource constraints at the FDA could slow inspections, overall regulatory clarity continues to buoy the herbal medicinal products market.
Raw-material adulteration & supply shocks
Economic adulteration of bilberry, cranberry, and saw palmetto undermines brand reputation and compels investment in DNA barcoding to confirm authenticity. Climate volatility further disrupts harvests, creating price spikes that compress margins across the herbal medicinal products market.
Other drivers and restraints analyzed in the detailed report include:
- Rapid penetration of e-commerce and direct-to-consumer nutraceutical brands
- AI-driven platforms are mining phytochemical databases and predicting herb-drug interactions
- Fragmented global regulatory frameworks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Herbal dietary supplements captured 22.56% of the herbal medicinal products market share in 2025, reflecting mature consumer trust in capsules and tablets. Functional foods and beverages are charting a 8.29% CAGR to 2031 as shoppers fold botanicals into daily eating rituals rather than separate pill regimens. Sports-nutrition brands now blend ashwagandha, cordyceps, and rhodiola into hydration drinks to replace synthetic stimulants. This shift expands usage occasions and nudges retailers to allocate more shelf space to ready-to-consume formats.
Fermentation and precision-extraction technologies stabilize bioactive content, allowing manufacturers to promise consistent dosing in palatable products. These advances also mitigate raw-material shortages by producing key compounds such as artepillin C in yeast, boosting supply security. Higher margin potential fuels marketing spend that widens consumer reach, reinforcing functional foods' role as the primary engine of future herbal medicinal products market expansion.
Leaves generated 20.93% of the herbal medicinal products market size in 2025 thanks to entrenched green-tea and ginkgo pipelines. Flowers and bark now deliver the highest 7.38% CAGR because they contain dense anthocyanins, salicins, and proanthocyanidins prized for targeted benefits. Limited harvest windows and specialized processing underpin premium pricing that lifts revenue even on moderate volumes.
Enhanced extraction hardware unlocks delicate floral and woody matrices, while sustainability certifications reassure buyers about ethical sourcing. Brands highlight terroir and seasonal narratives to justify higher ticket sizes. As consumers seek niche bioactives, demand migrates toward these once-secondary plant parts, diversifying supply chains and elevating average selling prices in the herbal medicinal products market.
Complete Report Scope:
- By Product Type
- Herbal Pharmaceuticals
- Herbal Dietary Supplements
- Herbal Functional Foods & Beverages
- Herbal Cosmetics & Personal Care
- By Source (Plant Part)
- Leaves
- Roots & Rhizomes
- Whole Plant
- Fruits & Seeds
- Flowers & Bark
- By Form
- Tablets & Capsules
- Powders & Granules
- Liquid Extracts & Syrups
- Teas & Infusions
- Softgels & Gummies
- Topicals & Ointments
- By Distribution Channel
- Hospital & Retail Pharmacies
- Online / E-commerce
- Specialty Stores
- Hypermarkets & Supermarkets
- By Medicinal Plant Type
- Aloe vera
- Echinacea
- Turmeric (Curcuma longa)
- Ginseng
- Ginger
- Garlic
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 28.94% of 2025 revenue for the herbal medicinal products market, benefiting from transparent regulatory frameworks and high discretionary spending. Updated FDA guidance cuts bureaucratic friction, enticing innovation. Consumers increasingly choose evidence-based botanicals such as beetroot, whose sales climbed 108% in 2023.
Asia-Pacific achieves the fastest 7.90% CAGR through 2031, propelled by government initiatives that integrate traditional medicine into national healthcare systems. China's ethnic-medicine policy and India's expanded nutraceutical rules create fertile ground for startups and multinationals alike. India active pharmaceutical ingredients from botanical sources are emerging as key differentiators in the global herbal medicine supply chain. Japan's demographic aging intensifies demand for cognitive and joint-support formulations, while Southeast Asian biodiversity supports raw-material sourcing.
Europe sustains steady growth under Directive 2004/24/EC, which balances traditional use with safety documentation. Germany's naturopathic culture anchors regional demand, and the UK maintains relevance despite post-Brexit realignment. Emerging markets in the Middle East and Africa show potential but face infrastructure and regulatory gaps that must be bridged to unlock fuller participation in the herbal medicinal products market.
- Beijing Tong Ren Tang Chinese Medicine Co. Ltd.
- Bio-Botanica Inc.
- Bionorica SE
- Blackmores Ltd.
- Dabur India Ltd.
- Dermapharm Holding SE (Arkopharma SA)
- Dr. Willmar Schwabe GmbH & Co. KG (Schwabe Group)
- Gaia Herbs
- Herb Pharm
- Herbalife International, Inc.
- Himalaya Global Holdings
- Naturalin Bio-Resources Co., Ltd.
- Nature's Way Brands, LLC
- Nestle Health Science (Nature's Bounty)
- Otsuka Holdings (Pharmavite LLC)
- Ricola AG
- Tsumura & Co.
- Viatris Inc. (Rottapharm Madaus)
- Vytalogy Wellness (Jarrow Formulas, Inc.)
- Weleda
- Zand Immunity
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Consumers Worldwide Have Shifted Toward Natural, Plant-Based OTC Remedies
- 4.2.2 Progressive Regulators Are Shortening Launch Timelines
- 4.2.3 Rapid Penetration Of E-Commerce And Direct-To-Consumer Nutraceutical Brands
- 4.2.4 AI-Driven Platforms Are Mining Phytochemical Databases And Predicting Herb-Drug Interactions
- 4.2.5 Sports-Nutrition And Functional-Food Companies Are Incorporating Adaptogens In Performance Beverages
- 4.2.6 Fermentation-Based Biomanufacturing Now Yields Consistent, Pharma-Grade Phytochemicals
- 4.3 Market Restraints
- 4.3.1 Raw-Material Adulteration & Supply Shocks
- 4.3.2 Fragmented Global Regulatory Frameworks
- 4.3.3 Climate-Driven Loss Of Wild Medicinal Plant Species
- 4.3.4 Emerging Synthetic-Biology Platforms Can Produce Bio-Identical Botanical Actives In Microbial Cell Factories
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technology Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value-USD)
- 5.1 By Product Type
- 5.1.1 Herbal Pharmaceuticals
- 5.1.2 Herbal Dietary Supplements
- 5.1.3 Herbal Functional Foods & Beverages
- 5.1.4 Herbal Cosmetics & Personal Care
- 5.2 By Source (Plant Part)
- 5.2.1 Leaves
- 5.2.2 Roots & Rhizomes
- 5.2.3 Whole Plant
- 5.2.4 Fruits & Seeds
- 5.2.5 Flowers & Bark
- 5.3 By Form
- 5.3.1 Tablets & Capsules
- 5.3.2 Powders & Granules
- 5.3.3 Liquid Extracts & Syrups
- 5.3.4 Teas & Infusions
- 5.3.5 Softgels & Gummies
- 5.3.6 Topicals & Ointments
- 5.4 By Distribution Channel
- 5.4.1 Hospital & Retail Pharmacies
- 5.4.2 Online / E-commerce
- 5.4.3 Specialty Stores
- 5.4.4 Hypermarkets & Supermarkets
- 5.5 By Medicinal Plant Type
- 5.5.1 Aloe vera
- 5.5.2 Echinacea
- 5.5.3 Turmeric (Curcuma longa)
- 5.5.4 Ginseng
- 5.5.5 Ginger
- 5.5.6 Garlic
- 5.5.7 Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Beijing Tong Ren Tang Chinese Medicine Co. Ltd.
- 6.3.2 Bio-Botanica Inc.
- 6.3.3 Bionorica SE
- 6.3.4 Blackmores Ltd.
- 6.3.5 Dabur India Ltd.
- 6.3.6 Dermapharm Holding SE (Arkopharma SA)
- 6.3.7 Dr. Willmar Schwabe GmbH & Co. KG (Schwabe Group)
- 6.3.8 Gaia Herbs
- 6.3.9 Herb Pharm
- 6.3.10 Herbalife International, Inc.
- 6.3.11 Himalaya Global Holdings
- 6.3.12 Naturalin Bio-Resources Co., Ltd.
- 6.3.13 Nature's Way Brands, LLC
- 6.3.14 Nestle Health Science (Nature's Bounty)
- 6.3.15 Otsuka Holdings (Pharmavite LLC)
- 6.3.16 Ricola AG
- 6.3.17 Tsumura & Co.
- 6.3.18 Viatris Inc. (Rottapharm Madaus)
- 6.3.19 Vytalogy Wellness (Jarrow Formulas, Inc.)
- 6.3.20 Weleda
- 6.3.21 Zand Immunity
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

