PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2099405

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2099405
Military Aircraft Collision Avoidance Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the military aircraft collision avoidance systems market size in 2026 is estimated at USD 856.68 million, up from the 2025 value of USD 790 million, with projections to USD 1.28 billion in 2031, growing at an 8.28% CAGR over 2026-2031.
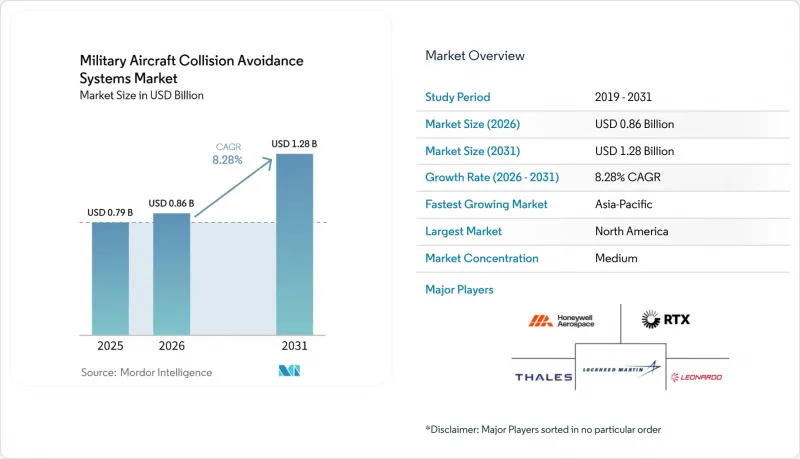
This report is Segmented by System Type (Radars, Traffic Alert and Collision Avoidance System, and More), Platform (Manned Aircraft and Unmanned Aerial Vehicles), Component (Processors, Mode 5 Transponders, Antennas and Sensors, and More), End User (OEM and Aftermarket), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Military Aircraft Collision Avoidance Systems Market Trends and Insights
Rising Defense Spending and New Aircraft Procurement
Escalating global defense outlays shape the primary demand curve for the military aircraft collision avoidance systems market. The US Indo-Pacific Command allocates substantial funding to new tactical air platforms that integrate avoidance capability at the design stage, reducing retrofit complexity later. India's 114-fighter tender embeds collision avoidance as a baseline avionics requirement, cementing supplier pipelines for processors, sensors, and secure transponders. High-value procurement contracts bundle collision-avoidance upgrades with open-systems architectures, enabling continued capability insertion throughout the fleet life cycle. The spending uptrend, spanning fighters, transports, and special-mission aircraft, tilts revenue growth toward suppliers capable of quickly certifying modular, multi-function packages. Procurement agencies also emphasize commonality to reduce training and sustainment costs, thereby creating follow-on opportunities for software-defined upgrades after initial delivery.
Mandatory Compliance with TCAS II v7.1 and ACAS-X Standards
Regulatory obligations convert avoidance upgrades from discretionary to non-negotiable investments. TCAS II v7.1 requires new threat-resolution logic and Mode S surveillance performance, often forcing complete line-replaceable unit swaps rather than firmware patches. Rotary-wing fleets need altitude-inhibition waivers or specialized low-altitude variants, adding complexity and certification fees. NATO STANAG 4193 interoperability mandates encrypted Mode 5 identification that tightly couples IFF transponders with collision-avoidance computations. Certification bottlenecks concentrate demand among a handful of approved suppliers, heightening price pressure yet reinforcing long-term aftermarket revenue as fleets queue for installation slots. Operators unable to meet 2027 compliance cut-offs risk grounding, underscoring the short-term acceleration in contract awards.
High Retrofit and Certification Costs for Legacy Military Fleets
Aging aircraft often lack spare weight, power, and space margins, so installing next-generation processors or antenna suites demands structural rewiring, rack redesign, and extensive ground-test cycles. Certification authorities require flight-safety evidence for each airframe-unique installation, prolonging test campaigns and inflating the cost per tail. Budget-constrained operators delay upgrades, stretching compliance grace periods and dampening near-term demand curves. Suppliers respond with plug-and-play kits that fit existing avionics bays, but unit pricing remains high due to one-off engineering and limited production volumes. The retrofit burden tempers overall market velocity even as it guarantees a longer revenue tail in technical services and spares.
Other drivers and restraints analyzed in the detailed report include:
- Surge in UAV Acquisitions Requiring Detect-and-Avoid Capabilities
- Advancements in Miniaturized 4D AESA Radar and AI-Based Sensor Fusion
- Radio Frequency Spectrum Congestion Affecting Cooperative Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The TCAS segment accounted for 41.05% of the military aircraft collision avoidance systems market in 2025 and is projected to grow at a 9.03% CAGR through 2031. Mandatory v7.1 upgrades drive complete hardware refreshes, lifting demand for processors with larger computational margins. TAWS remains relevant for low-altitude helicopter operations, while synthetic vision systems blend multiple sensor feeds into 3D cockpit displays that enhance pilots' situational awareness beyond simple alerting.
Replacement cycles gain momentum because operators find that installing advanced processors and Mode 5-capable transponders deliver cost synergies when bundled with broader avionics modernization. Cooperative logic within TCAS now integrates with onboard electronic warfare self-protection suites, enabling real-time deconfliction between mission maneuvers and collision avoidance. Manufacturers that certify such integrated packages capture higher-margin streams as customers prioritize holistic upgrades that ensure compliance without compromising combat capability.
Manned aircraft platforms accounted for 78.92% of the military aircraft collision avoidance systems market share in 2025, but UAVs are expected to deliver the fastest 9.31% CAGR to 2031. Fighter programs embed collision-avoidance logic within mission computers to minimize cockpit workload during high-G maneuvers, whereas large transports emphasize system reliability and integration with flight-management computers.
Unmanned platforms force suppliers to adopt edge AI processors that run avoidance logic locally, eliminating latency in datalink-dependent decision loops. MUM-T concepts require standardized threat-data schemas so that piloted aircraft and UAVs share situational awareness without saturating communications bandwidth. The focus on the MUM-T concept drives the development of compressed data formats and standard application programming interfaces, creating a niche for software vendors specializing in middleware bridging legacy avionics and next-generation autonomous cores.
Complete Report Scope:
- By System Type
- Radars
- Traffic Alert and Collision Avoidance System (TCAS)
- Terrain Awareness and Warning System (TAWS)
- Collision Warning System (CWS)
- Obstacle Collision Avoidance System (OCAS)
- Synthetic Vision Systems
- By Platform
- Manned Aircraft
- Combat Aircraft
- Transport Aircraft
- Special Mission Aircraft
- Helicopters
- Unmanned Aerial Vehicles (UAVs)
- Manned Aircraft
- By Component
- Processors
- Mode 5 Transponders
- Antennas and Sensors
- Display/Warning Units
- By End-User
- Original Equipment Manufacturer (OEM)
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America dominated the military aircraft collision avoidance systems market in 2025 with 40.78% revenue share. The US Department of Defense (DoD) modernization budgets fund large-scale upgrades to fighters, rotorcraft, and tankers, each of which requires compliant avoidance subsystems. Canada's Future Fighter Capability Project similarly stipulates Mode 5 identification and collision-avoidance alignment at initial delivery, reinforcing demand for integrated solutions.
Europe maintains balanced growth as NATO standardization initiatives push members toward identical avoidance logic and encrypted transponders. Collaborative programs such as the Eurodrone and the Future Combat Air System (FCAS) embed collision-avoidance requirements, sustaining a steady backlog for prime contractors. Spectrum congestion concerns drive regional interest in passive radar technology, and suppliers partnering with air navigation service providers accelerate certification for dual-civil-military use cases.
Asia-Pacific is the fastest-growing region, with a 9.76% CAGR, driven by substantial aircraft procurement in India, South Korea, Japan, and Australia. Due to export-control barriers, China's domestic demand remains significant but inward-focused, prompting indigenous sensor development. ASEAN nations invest in ground-based beyond-visual-line-of-sight (BVLOS) networks that complement airborne systems, extending collision-avoidance coverage over dispersed archipelagic territories. These factors collectively expand the region's military aircraft collision-avoidance systems market footprint, attracting Western and local suppliers to enter joint ventures to navigate offset requirements and technology-transfer rules.
- Honeywell Aerospace Inc.
- L3Harris Technologies, Inc.
- Collins Aerospace (RTX Corporation)
- Leonardo S.p.A.
- Thales Group
- Avidyne Corporation
- Lockheed Martin Corporation
- BAE Systems plc
- Saab AB
- Elbit Systems Ltd.
- Sagetech Avionics, Inc.
- Iris Automation Inc.
- uAvionix Corporation
- General Atomics Aeronautical Systems Inc. (General Atomics)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising defense spending and new aircraft procurement
- 4.2.2 Mandatory compliance with TCAS II v7.1 and ACAS-X standards
- 4.2.3 Surge in UAV acquisitions requiring detect-and-avoid capabilities
- 4.2.4 Advancements in miniaturized 4D AESA radar and AI-based sensor fusion
- 4.2.5 Increasing need for manned-unmanned teaming (MUM-T) interoperability
- 4.2.6 Deployment of ground-based BVLOS sense-and-avoid (SAA) networks
- 4.3 Market Restraints
- 4.3.1 High retrofit and certification costs for legacy military fleets
- 4.3.2 Radio frequency spectrum congestion affecting cooperative systems
- 4.3.3 Risk of GNSS jamming disrupting collision avoidance algorithms
- 4.3.4 Supply chain limitations for GaN-based RF devices
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By System Type
- 5.1.1 Radars
- 5.1.2 Traffic Alert and Collision Avoidance System (TCAS)
- 5.1.3 Terrain Awareness and Warning System (TAWS)
- 5.1.4 Collision Warning System (CWS)
- 5.1.5 Obstacle Collision Avoidance System (OCAS)
- 5.1.6 Synthetic Vision Systems
- 5.2 By Platform
- 5.2.1 Manned Aircraft
- 5.2.1.1 Combat Aircraft
- 5.2.1.2 Transport Aircraft
- 5.2.1.3 Special Mission Aircraft
- 5.2.1.4 Helicopters
- 5.2.2 Unmanned Aerial Vehicles (UAVs)
- 5.2.1 Manned Aircraft
- 5.3 By Component
- 5.3.1 Processors
- 5.3.2 Mode 5 Transponders
- 5.3.3 Antennas and Sensors
- 5.3.4 Display/Warning Units
- 5.4 By End-User
- 5.4.1 Original Equipment Manufacturer (OEM)
- 5.4.2 Aftermarket
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Honeywell Aerospace Inc.
- 6.4.2 L3Harris Technologies, Inc.
- 6.4.3 Collins Aerospace (RTX Corporation)
- 6.4.4 Leonardo S.p.A.
- 6.4.5 Thales Group
- 6.4.6 Avidyne Corporation
- 6.4.7 Lockheed Martin Corporation
- 6.4.8 BAE Systems plc
- 6.4.9 Saab AB
- 6.4.10 Elbit Systems Ltd.
- 6.4.11 Sagetech Avionics, Inc.
- 6.4.12 Iris Automation Inc.
- 6.4.13 uAvionix Corporation
- 6.4.14 General Atomics Aeronautical Systems Inc. (General Atomics)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

