PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2113390

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2113390
Asia-Pacific Life And Annuity Insurance - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Asia-Pacific life and annuity insurance market size in terms of gross written premiums value is projected to expand from USD 287.01 billion in 2025 and USD 300.24 billion in 2026 to USD 376.10 billion by 2031, registering a CAGR of 4.61% between 2026 to 2031.
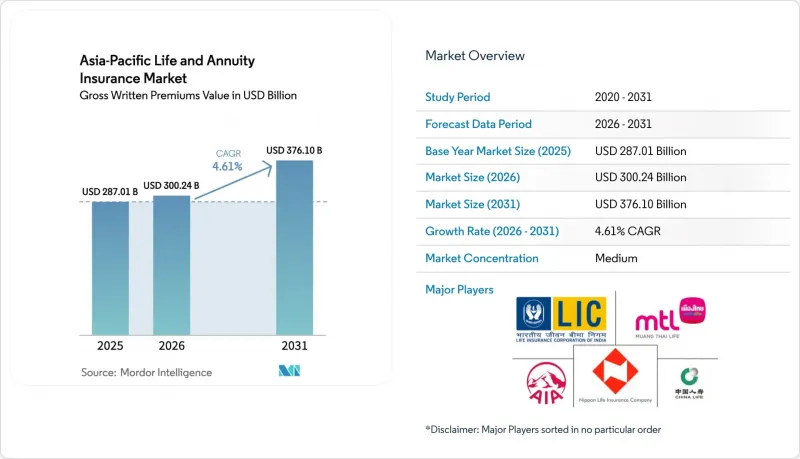
This report is Segmented by Insurance Type (Life Insurance, Annuity Insurance), Distribution Channel (Brokers/Agents, Banks, Direct Sales, Other Channels), and Geography (China, India, Japan, Singapore, Australia, Rest of APAC). The Market Forecasts are Provided in Terms of Value (USD).
Asia-Pacific Life And Annuity Insurance Market Trends and Insights
Demographic Aging and Retirement Security Demand
Asia-Pacific is experiencing unprecedented population aging, which is driving a significant shift in demand for retirement and health-linked insurance products. As of 2023, the Asia-Pacific region has approximately 697 million people aged 60 and over (14.8 % of the total population), including 489 million aged 65+ and 89 million aged 80+. The older population is projected to rise rapidly to 885 million by 2030 and 1.34 billion by 2050, with the 60+ share increasing to 25.9 %. This demographic transformation is fueled by declining fertility rates (1.9 births per woman) and rising life expectancy of 74.9 years, resulting in a growing cohort of longer-living seniors. The accelerated aging trend is increasing demand for retirement income solutions, annuities, and health-linked protection, as individuals face longer post-retirement periods and rising pressure on public pension systems. Governments are emphasizing policies that support healthy aging and extended working lives, such as China's goal to increase average life expectancy to around 80 years by 2030, which aligns with expanding retirement security needs.
Rising Disposable Incomes in Emerging APAC Economies
Rising household incomes across emerging Asia are expanding the pool of first-time buyers and deepening demand for both protection and savings-linked products. In India, the insurance sector has benefited directly from this trend: the market has grown at a ~17 % CAGR over the past two decades and is projected to reach ₹19,30,290 crore (USD 222 billion) by FY26, driven by higher premiums, growing middle-class participation, and rising per capita premium levels, reflecting higher disposable income and affordability. Nationwide inclusion goals and digital platforms are broadening access, channeling new middle-class purchasing power into formal insurance, while modest penetration relative to population size means that even small increases in awareness and income can translate into significant premium growth. Consumer surveys indicate strong demand for flexible solutions combining life and health features, particularly among younger buyers entering the market who seek bundled benefits rather than single-purpose coverage. Emerging cities and smaller towns are becoming increasingly important sources of new business, as distribution expands beyond metropolitan centers and digital engagement complements traditional advice-led sales.
Low Financial Literacy and Trust Deficits
Awareness gaps and trust barriers slow conversion from interest to purchase in many communities across emerging Asia. Penetration remains modest in large markets where significant shares of the population still rely on informal mechanisms and short planning horizons for financial security. Consumer research indicates a clear preference for bundled life and health propositions rather than pure life policies, which means traditional single-purpose protection products can underperform against customer expectations. The shortfall in long-term planning is visible in protection gap measures that show both mortality and health shortfalls, with a high concentration in emerging markets where advice and guidance are limited. Efforts to close these gaps rely on trusted advice, simple product narratives, and transparent servicing that reinforce confidence at the point of need. The Asia-Pacific life and annuity insurance market continues to see positive outcomes when consumer education, distribution quality, and product relevance improve together.
Other drivers and restraints analyzed in the detailed report include:
- Digitalization of Insurance and Investment Products
- Regulatory and Government-Led Financial Inclusion Initiatives
- High Cost Perception and Affordability Constraints
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Life insurance commanded a 63.5% share in 2025 and is projected to expand at a 7.82% CAGR through 2031, setting the pace among product categories in the Asia-Pacific life and annuity insurance market. This momentum reflects a deliberate shift in product mix toward risk-focused offerings with income features that help policyholders manage longevity risk and sequence-of-returns risk in retirement. As populations age, lifetime income options and care-linked features become central to household planning, and customer surveys show a strong tilt toward integrated solutions over standalone protection. Leading carriers are also weaving care and service ecosystems into annuity-linked propositions to support aging at home, faster claims, and personalized service. With retirement security rising as a primary goal for more households, the Asia-Pacific life and annuity insurance industry is repositioning product architecture around reliable income, transparent guarantees, and service quality that holds up over time.
The depth of the retirement income need is visible in longevity gap indicators, and in the way senior-focused products are now positioned at the center of advisory conversations. Income features that blend guaranteed payouts with measured exposure to growth assets are emphasized in wealth planning for the region's mass affluent and high-net-worth customers. Product innovation highlights include flexible income start dates, inflation-aware payout options, and healthcare riders that adapt coverage as medical needs evolve with age. Global groups in Asia are building broader platforms to serve decumulation, estate planning, and cross-border financial goals, tying insurance with asset management capabilities. This evolution supports stable growth for the Asia-Pacific life and annuity insurance market as more households convert savings to sustainable income streams with built-in protection.
Complete Report Scope:
- By Insurance Type
- Life Insurance
- Annuity Insurance
- By Distribution Channel
- Brokers/Agents
- Banks
- Direct Sales
- Other Channels
- By Country
- China
- India
- Japan
- Singapore
- Australia
- Rest of APAC
List of Companies Covered in this Report:
- AIA Group
- Nippon Life Group
- Life Insurance Corporation of India (LIC)
- China Life Insurance Group
- Muang Thai Life Assurance Group
- Prudential plc
- Manulife Financial Group
- Dai-ichi Life Group
- Meiji Yasuda Life Group
- Tokio Marine Group
- MS&AD Insurance Group
- Samsung Life Insurance Group
- HDFC Life Group
- Sun Life Financial Group
- HSBC Life Group
- Aviva Group
- TAL Group
- AMP Group
- Ping An Insurance Group
- Hong Leong Financial Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Demographic Aging and Retirement Security Demand
- 4.2.2 Rising Disposable Incomes in Emerging APAC Economies
- 4.2.3 Improving Financial Literacy and Retirement Awareness
- 4.2.4 Increasing Life Expectancy and Longevity Risk
- 4.2.5 Digitalization of Insurance and Investment Products
- 4.2.6 Regulatory and Government-Led Financial Inclusion Initiatives
- 4.3 Market Restraints
- 4.3.1 Aging Population and Retirement Needs
- 4.3.2 Income Growth in Emerging Markets
- 4.3.3 Financial Literacy and Awareness
- 4.3.4 Longevity and Post-Retirement Sustainability
- 4.4 Macroeconomic & Industry Indicators Impacting the Market
- 4.5 Technology Analysis
- 4.6 Industry Value Chain Analysis
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Insurance Type
- 5.1.1 Life Insurance
- 5.1.2 Annuity Insurance
- 5.2 By Distribution Channel
- 5.2.1 Brokers/Agents
- 5.2.2 Banks
- 5.2.3 Direct Sales
- 5.2.4 Other Channels
- 5.3 By Country
- 5.3.1 China
- 5.3.2 India
- 5.3.3 Japan
- 5.3.4 Singapore
- 5.3.5 Australia
- 5.3.6 Rest of APAC
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 AIA Group
- 6.4.2 Nippon Life Group
- 6.4.3 Life Insurance Corporation of India (LIC)
- 6.4.4 China Life Insurance Group
- 6.4.5 Muang Thai Life Assurance Group
- 6.4.6 Prudential plc
- 6.4.7 Manulife Financial Group
- 6.4.8 Dai-ichi Life Group
- 6.4.9 Meiji Yasuda Life Group
- 6.4.10 Tokio Marine Group
- 6.4.11 MS&AD Insurance Group
- 6.4.12 Samsung Life Insurance Group
- 6.4.13 HDFC Life Group
- 6.4.14 Sun Life Financial Group
- 6.4.15 HSBC Life Group
- 6.4.16 Aviva Group
- 6.4.17 TAL Group
- 6.4.18 AMP Group
- 6.4.19 Ping An Insurance Group
- 6.4.20 Hong Leong Financial Group
7 Market Opportunities & Future Outlook
- 7.1 Growing Aging Population and Rising Retirement Planning Needs
- 7.2 Product Innovation and Customization by Insurers

