PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2113403

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2113403
Purified Terephthalic Acid - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the purified terephthalic acid market size is estimated at 98.53 Million tons in 2026, and is expected to reach 128.41 Million tons by 2031, at a CAGR of 5.44% during the forecast period (2026-2031).
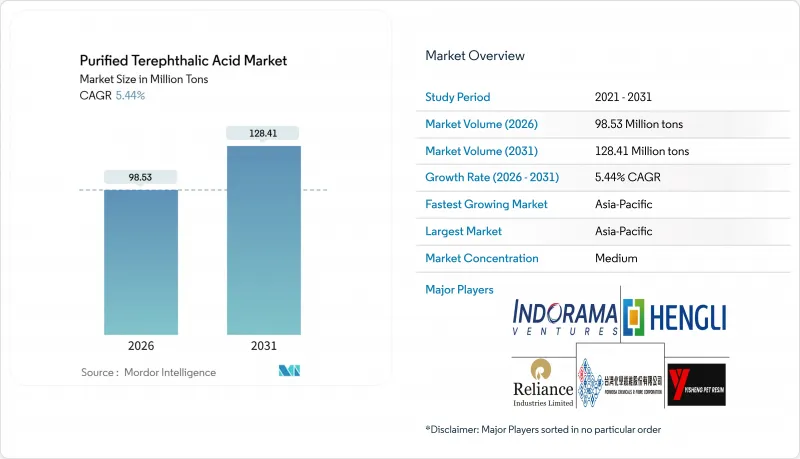
This report is Segmented by Derivative (Polyethylene Terephthalate (PET), Polybutylene Terephthalate (PBT), Polytrimethylene Terephthalate (PTT), and Dimethyl Terephthalate (DMT)), Technology (PX Oxidation (Conventional), Bio-Based PTA, and Chemical Recycling-Based PTA), Application (Packaging, Fibers, Paints and Coatings, and More), and Geography (Asia-Pacific, North America, Europe, and More).
Global Purified Terephthalic Acid Market Trends and Insights
Strong PET-Packaging Demand from E-Commerce
The steady rise of online grocery and meal-kit delivery boosts demand for lightweight, shatter-resistant PET containers that withstand complex fulfillment chains. Brazil recycled 410,000 tons of PET in 2024 yet still operated at 23% idleness, underscoring feedstock shortages even as a new decree forces a 32% recovery rate in 2026 and 50% by 2040. Brand owners must fund roughly USD 2 billion a year for collection and recycling capacity, while virgin PTA producers weigh backward-integration strategies to secure rPET supply.
Polyester-Fiber Capacity Additions in Asia
Chinese and Indian producers brought 4.2 million tons of new polyester-fiber capacity online between 2024 and 2025. Reliance Industries alone generated 2.59 million tons of PTA during FY 2024-25 to feed its captive yarn lines. Overcapacity suppresses Zhengzhou PTA futures but favors large integrated firms that wield paraxylene advantages and withstand price troughs better than merchant players.
Toxicological Concerns Around PTA Dust Exposure
OSHA maintains a 5 mg/m3 TWA for terephthalic acid dust, compelling retrofit investments of USD 10-15 million for older 500,000-ton units. INEOS shuttered a Belgian plant in 2023 over compliance costs, and Mitsubishi Chemical divested Indonesian assets, illustrating tightening regulatory economics for sub-scale producers.
Other drivers and restraints analyzed in the detailed report include:
- Automakers' Shift to Lightweight PET Composites
- Recycled-PET Closed-Loop Mandates
- Paraxylene and Crude-Oil Price Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyethylene Terephthalate (PET) absorbed 64.35% of purified terephthalic acid market share in 2025 and is forecast to grow at 6.51% CAGR through 2031, reinforcing its central role in packaging and textiles. PBT retains a lower market share, serving high-temperature automotive connectors, while PTT remains niche in carpets and specialty textiles. DMT's role has dwindled as direct esterification prevails, yet Koch Technology Solutions' PolyVolve process renews interest by integrating recycled streams and cutting energy consumption 9%.
The derivative mix tilts further toward PET over the outlook as e-commerce orders and rPET mandates accumulate. However, achieving recycled-content goals hinges on sufficient post-consumer supply, a variable that could temper PET's growth advantage. Producers increasingly deploy continuous-polymerization lines compatible with depolymerized monomers, enhancing circularity credentials for the purified terephthalic acid market.
Complete Report Scope:
- By Derivative
- Polyethylene Terephthalate (PET)
- Polybutylene Terephthalate (PBT)
- Polytrimethylene Terephthalate (PTT)
- Dimethyl Terephthalate (DMT)
- By Technology
- PX Oxidation (Conventional)
- Bio-based PTA
- Chemical Recycling-based PTA
- By Application
- Packaging
- Fibers
- Paints and Coatings
- Adhesives
- Other Applications (Engineering Plastics, Pharmaceuticals and Intermediates, etc.)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 53.75% of 2025 consumption and is tracking a 7.12% CAGR, the purified terephthalic acid market's fastest regional pace. New PTA lines in China's Jiujiang and India's Maharashtra add more than 8 million tons by 2027, underpinning vertically integrated polyester chains. India's Reliance plans an additional 3 million-ton module at Dahej by 2027, while Adani-Indorama's USD 3 billion JV fast-tracks a 3.2 million-ton plant using port proximity to slash freight costs.
In North America, Alpek's 1.2 million-ton Mexican unit supplies U.S. converters, yet Chinese imports cap pricing. Eastman's depolymerization plant in France will export recycled PTA to North American brand owners, offering premium feedstock for closed-loop bottles.
Europe lags growth as high energy prices restrain new builds. INEOS's 2023 closure highlights compliance burden under REACH, driving investment into chemical recycling rather than virgin capacity. South America contributes 6% led by Brazil, which must quadruple selective collection by 2040 to meet new decrees, generating opportunities for recycling ventures. Middle-East and Africa collectively command lower share; SABIC channels capital into Chinese downstream assets rather than local PTA, focusing on capturing value in end-use growth hubs.
- Alpek S.A.B. de C.V.
- BP p.l.c.
- China Petroleum & Chemical Corporation
- Eastman Chemical Company
- FCFC
- HENGLI PETROCHEMICAL ( DALIAN ) CHEMICAL CO., LTD.
- Indian Oil Corporation Ltd
- Indorama Ventures Public Company Limited
- INEOS
- JBF Industries Limited
- LOTTE Chemical Corporation
- Mitsubishi Chemical Corporation
- Oriental Petrochemical (Taiwan) Co., Ltd.
- PetroChina Company Limited
- Reliance Industries Limited
- SABIC
- Samnam Petrochemical Co.,Ltd.
- Yisheng Pet Resin
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Strong PET-Packaging Demand from E-Commerce
- 4.2.2 Polyester-Fibre Capacity Additions in Asia
- 4.2.3 Automakers' Shift to Lightweight PET Composites
- 4.2.4 Recycled-PET (rPET) Closed-Loop Mandates
- 4.2.5 Battery-Separator-Grade PTA Uptake
- 4.3 Market Restraints
- 4.3.1 Toxicological Concerns Around PTA Dust Exposure
- 4.3.2 Paraxylene and Crude-Oil Price Volatility
- 4.3.3 Bio-Based PEF and Other Polymer Substitutions
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Derivative
- 5.1.1 Polyethylene Terephthalate (PET)
- 5.1.2 Polybutylene Terephthalate (PBT)
- 5.1.3 Polytrimethylene Terephthalate (PTT)
- 5.1.4 Dimethyl Terephthalate (DMT)
- 5.2 By Technology
- 5.2.1 PX Oxidation (Conventional)
- 5.2.2 Bio-based PTA
- 5.2.3 Chemical Recycling-based PTA
- 5.3 By Application
- 5.3.1 Packaging
- 5.3.2 Fibers
- 5.3.3 Paints and Coatings
- 5.3.4 Adhesives
- 5.3.5 Other Applications (Engineering Plastics, Pharmaceuticals and Intermediates, etc.)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 Italy
- 5.4.3.4 France
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Alpek S.A.B. de C.V.
- 6.4.2 BP p.l.c.
- 6.4.3 China Petroleum & Chemical Corporation
- 6.4.4 Eastman Chemical Company
- 6.4.5 FCFC
- 6.4.6 HENGLI PETROCHEMICAL ( DALIAN ) CHEMICAL CO., LTD.
- 6.4.7 Indian Oil Corporation Ltd
- 6.4.8 Indorama Ventures Public Company Limited
- 6.4.9 INEOS
- 6.4.10 JBF Industries Limited
- 6.4.11 LOTTE Chemical Corporation
- 6.4.12 Mitsubishi Chemical Corporation
- 6.4.13 Oriental Petrochemical (Taiwan) Co., Ltd.
- 6.4.14 PetroChina Company Limited
- 6.4.15 Reliance Industries Limited
- 6.4.16 SABIC
- 6.4.17 Samnam Petrochemical Co.,Ltd.
- 6.4.18 Yisheng Pet Resin
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
- 7.2 Advancement in Production Technology

