PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2113404

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2113404
South America Thermoplastic Elastomer (TPE) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
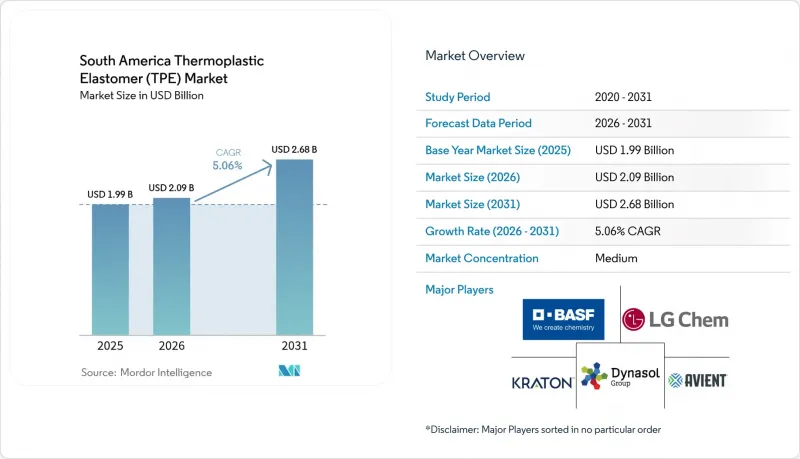
According to Mordor Intelligence, South America thermoplastic elastomer (TPE) market size in 2026 is estimated at USD 2.09 billion, growing from 2025 value of USD 1.99 billion with 2031 projections showing USD 2.68 billion, growing at 5.06% CAGR over 2026-2031.
This report is Segmented by Product Type (Styrenic Block Copolymer, Thermoplastic Olefin, Elastomeric Alloy, and More), Application (Automotive and Transportation, Building and Construction, Footwear and Sporting Goods, Electrical and Electronics, Medical, and More), and Geography (Brazil, Argentina, and Rest of South America). Market Forecasts are Provided in Terms of Value (USD).
South America Thermoplastic Elastomer (TPE) Market Trends and Insights
Automotive Lightweighting and EV Production Surge
Stellantis, Volkswagen, and General Motors committed more than USD 22 billion in hybrid and battery-electric projects under Brazil's Mover incentive scheme, prompting widespread substitution of EPDM with thermoplastic vulcanizates that deliver 30% weight savings and 40% faster cycle times. Halogen-free thermoplastic polyurethane now dominates high-voltage cable jackets because Lubrizol's Estane grades meet IEC 62893 flammability and withstand continuous 125 °C exposure. Argentina's EV registrations increased sharply between 2022 and 2023 as charging corridors expanded in Buenos Aires and Cordoba. Yet regional suppliers still lack in-line degassing and low-VOC compounding, forcing importation of pre-colored pellets and lengthening lead times to as much as 12 weeks.
Infrastructure Rehabilitation and Green Public Works Spend
Argentina secured USD 1 billion from the Inter-American Development Bank for the Parana River bridge and USD 816 million from China Machinery Engineering Corporation for rail upgrades, anchoring a USD 452 billion public-works roadmap through 2040. Provincial tenders specify thermoplastic-olefin combinations that resist ozone cracking and remain elastic below -20 °C. Grades with 9-35% post-consumer recycled content now meet the ASTM C1401 adhesion standard and help contractors earn green-building credits. Long payback horizons mean specifiers favor premium copolyester and polyamide elastomers that resist hydrolysis in coastal humidity, even when acquisition costs are higher.
Volatile Styrene and Petro-Feedstock Pricing
Brazilian crackers ran at 60% utilization in 2024, and natural-gas prices near USD 15 per million Btu inflated ethylene and propylene costs, pushing styrene spot quotes between USD 1,100 and USD 1,450 per ton during unplanned outages at Braskem's Triunfo complex. Argentina's Bahia Blanca hub suffered storm damage in 2023, and although feedstock output rebounded 37.1% in December 2024, downstream plastics demand fell 5.1%. Compounders now carry up to 90 days of inventory, and quarterly surcharges erode the cost advantage that thermoplastic elastomers hold over thermoset rubber. Brazil's Presiq program, valued at R$4.0 billion per year starting in 2027, aims to stabilize raw material prices, but its execution hinges on congressional budget approvals.
Other drivers and restraints analyzed in the detailed report include:
- Accelerated Medical-Device Manufacturing and Reshoring
- Footwear Sector Pivot to Bio-Based TPE Soles
- Limited Regional Compounding and Masterbatch Capacity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Styrenic block copolymers generated 38.92% of 2025 revenue, delivering transparency, a soft-touch feel, and adhesion to polypropylene for footwear soles and consumer overmolding applications. Their density below 1.0 g/cm3 supports automakers' mass-reduction strategies, while the segment also underpins the use of hot-melt adhesives by packaging converters. Thermoplastic olefins are used in exterior trim and under-hood air-duct applications because they resist chemicals and ultraviolet exposure. Elastomeric alloys, such as thermoplastic vulcanizates, are displacing EPDM door seals, reducing vehicle weight by 30% and compressing assembly cycles. Copolyester and polyamide elastomers withstand continuous service at 130 °C in exhaust hangers and transmission mounts, justifying premium pricing in powertrain components.
Thermoplastic polyurethane will post the fastest 5.49% CAGR through 2031, fueled by mining conversions where TPU replaces cast polyurethane in slurry pumps, raising service life by 20-50% and cutting downtime. Halogen-free polyether-based TPU also anchors high-voltage EV cable jackets that must withstand continuous duty at 125 °C and cold starts at -40°C. Bio-attributed TPU derived from castor oil polyols enables footwear brands to claim up to 30% renewable content without compromising Shore A hardness or rebound. Raw-material pressure remains a concern because Middle Eastern polyol suppliers diverted capacity to specialty chemicals, lifting polyol prices 12-18% in 2024.
Complete Report Scope:
- By Product Type
- Styrenic Block Copolymer (TPE-S)
- Thermoplastic Olefin (TPE-O)
- Elastomeric Alloy (TPE-V / TPV)
- Thermoplastic Polyurethane (TPU)
- Thermoplastic Copolyester
- Thermoplastic Polyamide
- By Application
- Automotive and Transportation
- Building and Construction
- Footwear and Sporting Goods
- Electrical and Electronics
- Medical
- Household Appliances
- HVAC
- Adhesives, Sealants and Coatings
- Others
- By Geography
- Brazil
- Argentina
- Rest of South America
List of Companies Covered in this Report:
- Arkema
- Avient Corporation
- BASF
- DuPont
- Dynasol Group
- Evonik Industries AG
- Huntsman International LLC
- INEOS
- KRATON CORPORATION
- KURARAY CO., LTD.
- LG Chem
- Lubrizol Corporation
- LyondellBasell Industries Holdings B.V.
- Mitsubishi Chemical Corporation
- Mitsui Chemicals, Inc.
- RTP Company
- SABIC
- Wanhua
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Automotive lightweighting and EV production surge
- 4.2.2 Infrastructure rehabilitation and green public-works spend
- 4.2.3 Accelerated medical-device manufacturing and reshoring
- 4.2.4 Footwear sector's pivot to bio-based TPE soles
- 4.2.5 Mining and energy uptake of abrasion-resistant TPE parts
- 4.3 Market Restraints
- 4.3.1 Volatile styrene and petro-feedstock pricing
- 4.3.2 Limited regional compounding/masterbatch capacity
- 4.3.3 Tightening phthalate and VOC regulations
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products and Services
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Styrenic Block Copolymer (TPE-S)
- 5.1.2 Thermoplastic Olefin (TPE-O)
- 5.1.3 Elastomeric Alloy (TPE-V / TPV)
- 5.1.4 Thermoplastic Polyurethane (TPU)
- 5.1.5 Thermoplastic Copolyester
- 5.1.6 Thermoplastic Polyamide
- 5.2 By Application
- 5.2.1 Automotive and Transportation
- 5.2.2 Building and Construction
- 5.2.3 Footwear and Sporting Goods
- 5.2.4 Electrical and Electronics
- 5.2.5 Medical
- 5.2.6 Household Appliances
- 5.2.7 HVAC
- 5.2.8 Adhesives, Sealants and Coatings
- 5.2.9 Others
- 5.3 By Geography
- 5.3.1 Brazil
- 5.3.2 Argentina
- 5.3.3 Rest of South America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Arkema
- 6.4.2 Avient Corporation
- 6.4.3 BASF
- 6.4.4 DuPont
- 6.4.5 Dynasol Group
- 6.4.6 Evonik Industries AG
- 6.4.7 Huntsman International LLC
- 6.4.8 INEOS
- 6.4.9 KRATON CORPORATION
- 6.4.10 KURARAY CO., LTD.
- 6.4.11 LG Chem
- 6.4.12 Lubrizol Corporation
- 6.4.13 LyondellBasell Industries Holdings B.V.
- 6.4.14 Mitsubishi Chemical Corporation
- 6.4.15 Mitsui Chemicals, Inc.
- 6.4.16 RTP Company
- 6.4.17 SABIC
- 6.4.18 Wanhua
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

