PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114101

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114101
Building Integrated Photovoltaic (BIPV) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the building integrated photovoltaic market size is projected to be USD 13.45 billion in 2025, USD 16.66 billion in 2026, and reach USD 47.02 billion by 2031, growing at a CAGR of 23.06% from 2026 to 2031.
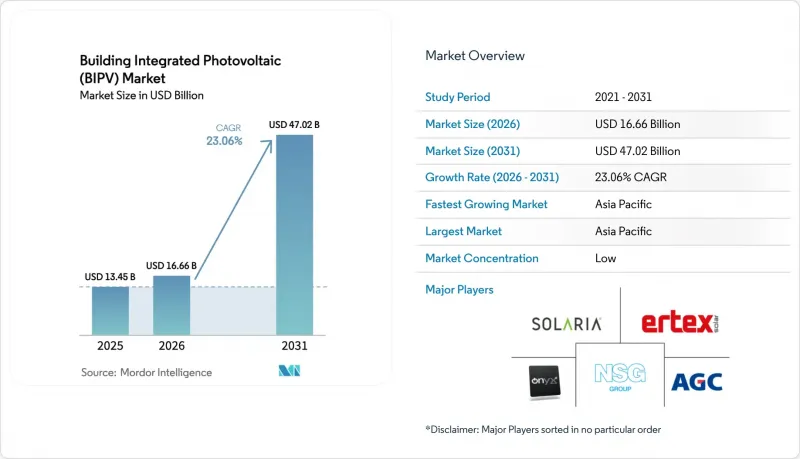
This report is Segmented by Technology (Crystalline Silicon, Thin-Film, and Emerging), End-User (Residential, Commercial, Industrial, and Institutional and Public Buildings), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Building Integrated Photovoltaic (BIPV) Market Trends and Insights
Supportive Policy Incentives & Zero-Carbon Building Mandates
Europe's Energy Performance of Buildings Directive 2024/1275 requires solar-ready roofs on all new structures by 2030, and phased retrofits for public buildings above 250 square meters now begin in 2027. Germany's KfW 442 program earmarked EUR 500 million in 2025 to subsidize 10-30% of installed costs, while France extended MaPrimeRenov grants up to EUR 11,000 for integrated facades. China's whole-county solar mandate, covering 676 counties by late 2025, obliges new industrial rooftops to host on-site generation or purchase renewable certificates, effectively guaranteeing a pipeline for the Building Integrated Photovoltaic (BIPV) market. These rules shorten permitting cycles, train specialist installers, and shift BIPV from a discretionary upgrade to a code requirement. As more jurisdictions transpose similar directives, developers front-load solar envelopes into schematic designs to avoid costly redesigns later in the approval process.
Declining PV & Balance-of-System Costs
Monocrystalline PERC modules dropped to USD 0.12 per watt in mid-2025, and competitive pressure among inverter suppliers trimmed electronics pricing by 18% year-on-year. Standardized curtain-wall kits released by AGC and NSG/Pilkington cut on-site labor by 25% by integrating junction boxes and weather seals at the factory. Transparent PV glass still costs 20-40% more than low-E glazing, but high-rent developers recoup premiums by monetizing electricity and reducing mechanical-penthouse congestion. In the Gulf, the levelized cost of BIPV electricity fell below retail tariffs in 2025, enabling subsidy-free adoption where irradiance tops 2,200 kWh/m2/yr. As BOS manufacturers scale, the Building Integrated Photovoltaic (BIPV) market enjoys price elasticity that opens mid-tier commercial projects previously priced out of integrated solar facades.
High Initial Installation & Design Complexity
BIPV requires tight coordination among structural, electrical, and facade teams, yet few general contractors offer that integrated workflow. New York and California demand separate approvals for structural load, interconnection, and fire egress, pushing soft costs 12-18% above rooftop arrays and stretching timelines by up to six months. Custom curtain-wall integration can add EUR 550-850/m2 to budgets, nudging cost-conscious developers toward cheaper carports. Insurers levy 5-15% premiums until inspectors confirm UL 1703 and IEC 61730 compliance, reflecting caution over water ingress and rapid-shutdown reliability. A talent bottleneck compounds risks: fewer than 2,000 certified installers operate in North America, leading developers to import European crews at USD 800/day, which erodes project margins until local training accelerates.
Other drivers and restraints analyzed in the detailed report include:
- Rising Demand for Net-Zero / Smart-City Developments
- Growth of Facade-Integrated Transparent PV Glass
- Structural / Fire-Safety Code Barriers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Crystalline silicon commanded 87.5% of 2025 volume, equating to the largest Building Integrated Photovoltaic (BIPV) market share, yet perovskite-silicon tandems are set to erode that lead with a 27.5% CAGR to 2031. LONGi's Hi-MO 9 hit 24.92% efficiency, reinforcing silicon's high-wattage advantage, while First Solar's Series 7 CdTe maintained output in high-temperature warehouses. Still, laboratory tandem cells at 29.1% efficiency have spurred pilot facades across Europe, indicating looming parity. Early field data from Heliatek's organic films suggest 25-year durability is attainable, undermining the perception that flexible modules are short-life novelties. The Building Integrated Photovoltaic (BIPV) market now offers architects a spectrum from rigid, high-density panels to light organic rolls, allowing project teams to match substrate, weight, and aesthetics. Supply-chain nuances matter: low-iron glass shortages can stall crystalline projects, whereas polymer-substrate tandems bypass that constraint. Once IEC 61215 certification reaches perovskite modules in 2027, financing barriers will fall, and crystalline players may confront accelerated share loss.
Second-generation thin films occupy a middle ground. CdTe, CIGS, and amorphous silicon demonstrate lower temperature coefficients, which protects yield in desert climates, yet their energy density still trails top-tier mono-PERC. As module prices slide, thin films pivot to niche value, curved skylights, heritage facades, and ultra-light tensile roofs, rather than head-to-head wattage battles. OEMs are investing in hybrid lines that laminate perovskite coatings onto crystalline wafers, chasing efficiency gains without radical factory retools. The outcome will decide whether silicon defends incumbency or concedes premium architectural projects to newer chemistries within the Building Integrated Photovoltaic (BIPV) market.
Complete Report Scope:
- By Technology
- Crystalline Silicon (Monocrystalline, Polycrystalline)
- Thin-Film (CdTe, CIGS, a-Si)
- Emerging (Perovskite, Organic PV, Tandem)
- By End-User
- Residential
- Commercial
- Industrial
- Institutional and Public Buildings
- By Building Element (Qualitative Analysis)
- Roofs
- Facades/Curtain Walls
- Windows and Transparent Glazing
- Skylights and Atriums
- Shading Devices (Louvers, Balconies)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Spain
- Italy
- NORDIC Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- Australia and New Zealand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Nigeria
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific controlled 40.7% of global volume in 2025 and is forecast to grow 23.8% annually through 2031, protecting its leadership in the Building Integrated Photovoltaic (BIPV) market. China's 676-county solar mandate guarantees continuous demand, while Japan's feed-in tariff revision rewards self-consumption, lifting rooftop economics. Shenzhen obliges commercial buildings above 5,000 m2 to install BIPV skins, funneling orders to domestic giants LONGi, Trina, and Risen. India sets 300 GW solar by 2030 with a carved-out BIPV target for government facilities, but heterogeneous state codes and a shortage of facade engineers slow roll-out. ASEAN pilots, led by Singapore's Tengah district, mandate solar-ready roofs on 42,000 homes, showing scalability once policy clarity arrives.
Europe ranks second, propelled by the Energy Performance of Buildings Directive. Germany, France, and Spain underwrite 30-50% of project costs, while Sweden's carbon tax above EUR 100/tCO2 steers lifecycle economics toward integrated solar. The United Kingdom's Future Homes Standard pushes residential developers to adopt BIPV from 2025, though post-Brexit labor shortages inflated installer wages 12-15% after 2024. Nordic daylight fluctuations complicate annual yield but spur interest in high-efficiency tandem panels that offset seasonal lows. Altogether, supportive incentives anchor a predictable pipeline that multinationals use to trial cross-border procurement strategies within the Building Integrated Photovoltaic (BIPV) market.
North America's expansion clusters in California, New York, and parts of Canada, where updated net-metering and 30% federal ITC compress payback to 8-10 years. California's Title 24 extends solar mandates to commercial buildings over 10,000 ft2, triggering facade retrofits on older stock. New York's Climate Act compels municipal property managers to offset 70% of electricity with renewables by 2030, driving state contracts toward BIPV facades. The Middle East and Africa remain nascent yet promising, with NEOM and Masdar City embedding solar skins in master plans that target 100% renewable supply. High irradiance above 2,200 kWh/m2/yr offers sub-6-year payback even without subsidies, positioning the region as the next growth pole for the Building Integrated Photovoltaic (BIPV) market.
- Onyx Solar Energy SL
- AGC Inc.
- Nippon Sheet Glass (Pilkington)
- Ertex Solartechnik GmbH
- Solaria Corporation
- Sunovation GmbH
- Mitrex Inc.
- Changzhou Almaden Co. Ltd.
- NanoPV Solar Inc.
- Tesla Inc.
- First Solar Inc.
- Sharp Corporation
- Hanwha Q-Cells
- Canadian Solar Inc.
- LONGi Green Energy
- Trina Solar Ltd.
- Risen Energy Co. Ltd.
- Waaree Energies Ltd.
- Heliatek GmbH
- Ascent Solar Technologies
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Supportive policy incentives & zero-carbon building mandates
- 4.2.2 Declining PV & balance-of-system costs
- 4.2.3 Rising demand for net-zero/smart-city developments
- 4.2.4 Growth of facade-integrated transparent PV glass
- 4.2.5 Corporate ESG & green-building certification pressures
- 4.2.6 5G-ready rooftop infrastructure synergy
- 4.3 Market Restraints
- 4.3.1 High initial installation & design complexity
- 4.3.2 Structural / fire-safety code barriers
- 4.3.3 Limited skilled installers & facade-engineering know-how
- 4.3.4 Supply-chain constraints for specialty BIPV glass
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Investment & Funding Analysis
5 Market Size & Growth Forecasts
- 5.1 By Technology
- 5.1.1 Crystalline Silicon (Monocrystalline, Polycrystalline)
- 5.1.2 Thin-Film (CdTe, CIGS, a-Si)
- 5.1.3 Emerging (Perovskite, Organic PV, Tandem)
- 5.2 By End-User
- 5.2.1 Residential
- 5.2.2 Commercial
- 5.2.3 Industrial
- 5.2.4 Institutional and Public Buildings
- 5.3 By Building Element (Qualitative Analysis)
- 5.3.1 Roofs
- 5.3.2 Facades/Curtain Walls
- 5.3.3 Windows and Transparent Glazing
- 5.3.4 Skylights and Atriums
- 5.3.5 Shading Devices (Louvers, Balconies)
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 France
- 5.4.2.3 United Kingdom
- 5.4.2.4 Spain
- 5.4.2.5 Italy
- 5.4.2.6 NORDIC Countries
- 5.4.2.7 Russia
- 5.4.2.8 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 South Korea
- 5.4.3.5 ASEAN Countries
- 5.4.3.6 Australia and New Zealand
- 5.4.3.7 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Colombia
- 5.4.4.4 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 South Africa
- 5.4.5.4 Nigeria
- 5.4.5.5 Egypt
- 5.4.5.6 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration Analysis
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Onyx Solar Energy SL
- 6.4.2 AGC Inc.
- 6.4.3 Nippon Sheet Glass (Pilkington)
- 6.4.4 Ertex Solartechnik GmbH
- 6.4.5 Solaria Corporation
- 6.4.6 Sunovation GmbH
- 6.4.7 Mitrex Inc.
- 6.4.8 Changzhou Almaden Co. Ltd.
- 6.4.9 NanoPV Solar Inc.
- 6.4.10 Tesla Inc.
- 6.4.11 First Solar Inc.
- 6.4.12 Sharp Corporation
- 6.4.13 Hanwha Q-Cells
- 6.4.14 Canadian Solar Inc.
- 6.4.15 LONGi Green Energy
- 6.4.16 Trina Solar Ltd.
- 6.4.17 Risen Energy Co. Ltd.
- 6.4.18 Waaree Energies Ltd.
- 6.4.19 Heliatek GmbH
- 6.4.20 Ascent Solar Technologies
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

