PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114335

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114335
Blockchain In Telecom - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the blockchain in telecom market size reached USD 2.67 billion in 2026 and is projected to climb to USD 7.74 billion by 2031, advancing at a 23.72% CAGR during the forecast period.
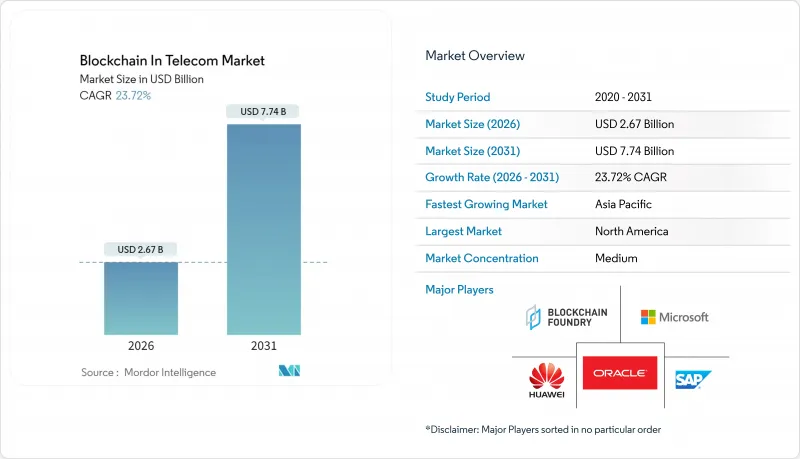
This report is Segmented by Application (Identity Management, Payment and Billing, Smart Contract, and More), Component (Platform, Services, and More), Blockchain Type (Public, Private, Consortium, and Hybrid), Deployment Type (On-Premises, and Cloud-Based), Organization Size (Small and Medium Enterprises, and Large Enterprises), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Blockchain In Telecom Market Trends and Insights
Focus on Telecom Fraud Mitigation
Global fraud losses touched USD 39.89 billion in 2024, pushing operators to adopt immutable ledgers that record call-detail data at source and block SIM-box bypass in real time. The United States STIR/SHAKEN rules require cryptographic caller-ID signatures, and several Tier-1 carriers now trial blockchain registries because centralized databases invite credential-stuffing attacks. Ericsson's pilot with Batelco cut roaming fraud 34% within six months, proving ledger-based shared intelligence delivers measurable gains. Fraud-mitigation needs favor consortium designs that let rivals share risk data without exposing proprietary subscriber records.
Rising Demand for Secure 5G Network Slicing
Network-slice contracts guarantee latency and bandwidth for autonomous vehicles or remote surgery. ITU-T standard Y.3087 sets distributed-ledger hooks for slice life-cycle logs, cementing blockchain as the trust layer for multi-operator SLAs. South Korea's 2025 rule makes ledger logging compulsory in public-sector slices, accelerating adoption by SK Telecom and KT Corporation. Smart contracts also automate penalty payments once performance drifts, eliminating multi-week reconciliation cycles that eroded operator margins.
Lack of Industry-wide Interoperability Standards
Only three of TM Forum's 58 Open APIs cover blockchain, forcing carriers to bankroll bespoke middleware that translates transactions between Hyperledger Fabric and Ethereum sidechains. MEF's orchestration spec defers ledger bindings until at least 2027, making early adopters fear stranded assets. IEEE's interoperability project is still a draft, so operators hedge bets with parallel integrations that inflate operating costs and curb ROI.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Roaming-settlement Efficiency Initiatives
- Regulatory Push for SIM and Device-identity Protection
- Scalability and Energy-efficiency Concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Payment and Billing led revenue with a 36.63% share in 2025, but Smart Contract workflows are on track for a 25.81% CAGR as operators embed SLA logic directly into Solidity code in the blockchain in telecom market. The shift reflects recognition that blockchain's advantage lies in automating roaming and spectrum-sharing agreements rather than mirroring legacy payment rails. Identity-management projects align with ETSI's eSIM rules, and caller-ID registries anchored in blockchain deliver STIR/SHAKEN compliance, trimming fraud without central honeypots.
Emerging Connectivity Provisioning ledgers now port numbers in under 10 minutes in South Korea, versus 48 hours under legacy HLR systems. Network-slicing orchestration follows ITU-T Y.3087 guidance, logging every parameter change for legal defensibility. Oracle's pre-built templates slash integration from nine months to six weeks, accelerating uptake among mid-tier carriers that lack deep OSS teams.
Ledger platforms dominated 57.33% of 2025 revenue as operators sought architectural control in the blockchain in telecom market. However, Services are projected to post a 24.55% CAGR because fewer than 2,000 engineers combine telecom domain mastery and blockchain skills worldwide. Guardtime recorded a 340% jump in audit mandates, signaling that contract-security validation is becoming non-negotiable. Hardware nodes remain the smallest slice yet are indispensable for 5G edge scenarios needing sub-20-millisecond validation latency.
Consultancies and hyperscalers are filling the talent void. IBM and Accenture launched certification tracks in 2025, while AWS, Azure, and Google Cloud embed telecom governance packs that let carriers comply with GDPR, China's Data Security Law, and other mandates straight out of the box. This feature set propels cloud platforms to grow 1.5 percentage points faster than on-premises builds.
Complete Report Scope:
- By Application
- Identity Management
- Payment and Billing
- Smart Contract
- Connectivity Provisioning
- Fraud Management and Authentication
- Network Management and Slicing Orchestration
- By Component
- Platform
- Services
- Hardware Nodes and Gateways
- By Blockchain Type
- Public Blockchain
- Private Blockchain
- Consortium Blockchain
- Hybrid Blockchain
- By Deployment Type
- On-premises
- Cloud-based
- By Organization Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America led with 37.12% revenue in 2025 after FCC caller-authentication rules compelled U.S. carriers to deploy ledger-based registries that cut robocalls by 28% within a year. Canada drafted parallel guidelines in 2025, and Mexico mandated blockchain number portability in 2024, trimming porting windows from 48 hours to six hours.
Asia-Pacific will record the fastest 28.17% CAGR through 2031. Reliance Jio integrated blockchain into nationwide 5G slices, while South Korea's compulsory ledger logging for public projects accelerates uptake. China issued 1,847 blockchain service licenses to telecom firms by late-2025, equating distributed ledgers with essential infrastructure. Japan's Rakuten Mobile uses blockchain to timestamp spectrum-sharing events with incumbents, shortening dispute cycles from six weeks to three days.
Europe held 28.5% share in 2025, propelled by GDPR-aligned eSIM ledger standards from ETSI that Vodafone, Orange, and Deutsche Telekom embraced. Middle East and Africa posted a 25.3% CAGR, with South Africa's blockchain SIM-registration mandate slashing fraudulent activations 41% in nine months. South America's growth centers on Brazil, where Anatel's portability reforms whittled transfer time to four hours.
- Huawei Technologies Co., Ltd.
- Microsoft Corporation
- Oracle Corporation
- SAP SE
- Blockchain Foundry Inc.
- Ping Identity Holding Corp. (ShoCard)
- Telefonaktiebolaget LM Ericsson
- Nokia Corporation
- International Business Machines Corporation
- Deutsche Telekom AG
- AT&T Inc.
- Verizon Communications Inc.
- Vodafone Group Plc
- Orange S.A.
- Telefonica, S.A.
- T-Mobile US, Inc.
- SoftBank Group Corp.
- Swisscom AG
- Reliance Jio Infocomm Limited
- BT Group plc
- Koninklijke KPN N.V.
- Guardtime OU
- Clear Projects Ltd.
- Syntropy Technologies Ltd.
- America Movil, S.A.B. de C.V. (Claro)
- Rakuten Group, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Focus on Telecom Fraud Mitigation
- 4.2.2 Rising Demand for Secure 5G Network Slicing
- 4.2.3 Increasing Roaming-settlement Efficiency Initiatives
- 4.2.4 Regulatory Push for SIM and Device-identity Protection
- 4.2.5 Emergence of Telco-focused Blockchain-as-a-service (BaaS)
- 4.2.6 Monetization of Carrier, Edge Nodes via Blockchain Marketplaces
- 4.3 Market Restraints
- 4.3.1 Lack of Industry-wide Interoperability Standards
- 4.3.2 Scalability and Energy-efficiency Concerns
- 4.3.3 High Integration Costs with Legacy OSS/BSS
- 4.3.4 Limited Telco-grade Smart-contract Audit Expertise
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Application
- 5.1.1 Identity Management
- 5.1.2 Payment and Billing
- 5.1.3 Smart Contract
- 5.1.4 Connectivity Provisioning
- 5.1.5 Fraud Management and Authentication
- 5.1.6 Network Management and Slicing Orchestration
- 5.2 By Component
- 5.2.1 Platform
- 5.2.2 Services
- 5.2.3 Hardware Nodes and Gateways
- 5.3 By Blockchain Type
- 5.3.1 Public Blockchain
- 5.3.2 Private Blockchain
- 5.3.3 Consortium Blockchain
- 5.3.4 Hybrid Blockchain
- 5.4 By Deployment Type
- 5.4.1 On-premises
- 5.4.2 Cloud-based
- 5.5 By Organization Size
- 5.5.1 Small and Medium Enterprises (SMEs)
- 5.5.2 Large Enterprises
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 ASEAN
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Nigeria
- 5.6.6.3 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Huawei Technologies Co., Ltd.
- 6.4.2 Microsoft Corporation
- 6.4.3 Oracle Corporation
- 6.4.4 SAP SE
- 6.4.5 Blockchain Foundry Inc.
- 6.4.6 Ping Identity Holding Corp. (ShoCard)
- 6.4.7 Telefonaktiebolaget LM Ericsson
- 6.4.8 Nokia Corporation
- 6.4.9 International Business Machines Corporation
- 6.4.10 Deutsche Telekom AG
- 6.4.11 AT&T Inc.
- 6.4.12 Verizon Communications Inc.
- 6.4.13 Vodafone Group Plc
- 6.4.14 Orange S.A.
- 6.4.15 Telefonica, S.A.
- 6.4.16 T-Mobile US, Inc.
- 6.4.17 SoftBank Group Corp.
- 6.4.18 Swisscom AG
- 6.4.19 Reliance Jio Infocomm Limited
- 6.4.20 BT Group plc
- 6.4.21 Koninklijke KPN N.V.
- 6.4.22 Guardtime OU
- 6.4.23 Clear Projects Ltd.
- 6.4.24 Syntropy Technologies Ltd.
- 6.4.25 America Movil, S.A.B. de C.V. (Claro)
- 6.4.26 Rakuten Group, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

