PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114478

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114478
Gravity Die Casting - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, gravity die casting market size in 2026 is estimated at USD 27.13 billion, growing from 2025 value of USD 26.14 billion with 2031 projections showing USD 32.66 billion, growing at 3.79% CAGR over 2026-2031.
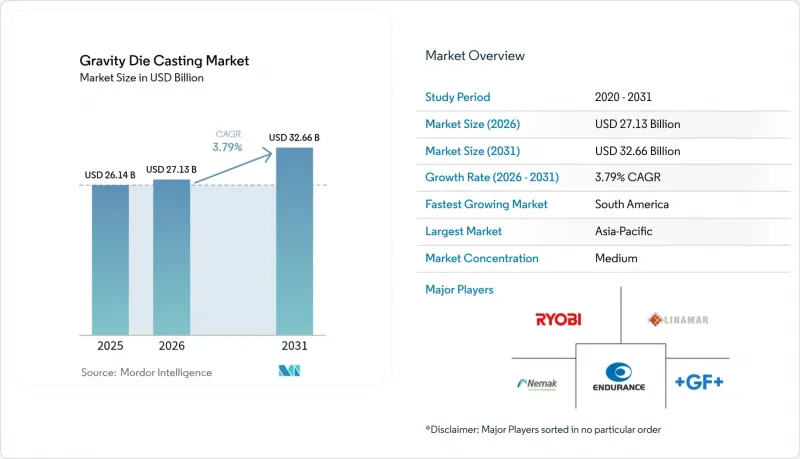
This report is Segmented by Material Type (Aluminum Alloys, and More), Application (Automotive Components, Electrical & Electronics, and More), Product Type (Engine Blocks, Transmission Housings, Wheels, and More), Process Type (Standard Gravity Die Casting and Tilt-Pouring Gravity Die Casting), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Gravity Die Casting Market Trends and Insights
Adoption of High-Strength Gravity-Cast Alloys
Advanced A356 and A380 formulations enhance fluidity while maintaining mechanical integrity, allowing designers to replace cast parts with forgings in chassis brackets and steering housings. Nanoparticle-reinforced AA7075 achieves near-wrought tensile properties and mass savings in thin-wall turbine wheels, illustrating how alloy innovations enable complex parts to remain within the gravity die casting market. By incorporating rare earth elements, developers of magnesium alloys have addressed concerns related to galvanic corrosion and flammability. This advancement paves the way for magnesium casting in aerospace structures and electric vehicle gearbox covers. Safran's patents on advanced super-alloy blade blanks underscore the growing dominance of gravity casting over investment casting in medium-temperature turbine stages. As more alloys become available for higher-temperature operations, the applications for gravity casting are expanding.
Automation and Tilt-Pour Productivity Gains
Servo-controlled tilt-pour cells cut fill turbulence and oxide inclusion, lifting first-pass yield rates and trimming cycle time . Across Europe and the United States, robotics is addressing skilled labor shortages, facilitating continuous unmanned operations, and boosting production flexibility. For instance, KUKA's automated cells are refining workflows by logging pour profiles and relaying them to cloud-based dashboards. Such insights enable predictive maintenance, which activates when thermal patterns shift, ensuring consistent quality and minimizing downtime. Additionally, Chinese manufacturers are enhancing material efficiency and cutting waste by adopting reverse-tilt casting techniques, especially for symmetric gear housings. This approach, which dispenses with extended runner systems, not only optimizes metal use but also streamlines production. Collectively, these innovations are transforming the die casting industry, combining automation, data analytics, and process advancements to enhance efficiency, reduce scrap, and meet the demands of high-mix manufacturing.
HPDC Substitution in High-Volume Parts
High-pressure die casting (HPDC) is increasingly used for producing components such as housings and brackets due to its fast cycle times and cost efficiency. Expanding manufacturing capacity enhances scalability, reduces unit costs, and makes HPDC a competitive alternative to gravity casting. Advancements in high-ductility alloys enable thinner walls that meet crash standards, supporting lightweighting without compromising safety. Global platform sharing among OEMs allows a single mold set to be used across multiple sites without requiring revalidation, streamlining logistics, and speeding up the time-to-market. HPDC's superior surface finishes often eliminate the need for secondary machining on components like wheels and brackets, further strengthening its cost advantage over gravity casting in high-volume, cost-sensitive applications.
Other drivers and restraints analyzed in the detailed report include:
- Automotive and EV Lightweighting Push
- Regulatory Fuel-Efficiency Mandates
- OEM Giga Casting Cannibalization Risk
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Aluminum held an 80.12% gravity die casting market share in 2025, driven by global recycling initiatives and standard alloys, which strike a balance between flow and tensile strength. Magnesium is set to outpace at a 4.68% CAGR through 2031 as breakthroughs in rare-earth alloying tackle flammability, pushing the gravity die casting market toward lighter drive casings in premium EVs. Aluminum benefits from a vast scrap network that supplies most of its foundry feedstock, dampening raw material cost swings and supporting sustainable product claims under EU ecodesign audits. Asian smelters offer low-carbon primary aluminum backed by hydroelectric power, raising interest from European OEMs seeking Scope 3 emission cuts.
Aluminum's dominance persists in heat-exchanger plates, cylinder heads, and inverter housing lids, where silicon additions confer casting fluidity and pressure tightness. Magnesium, meanwhile, is expanding beyond die-cast transmission cases into firewall stiffeners and seat frames, due to shot-peen surface hardening, which increases fatigue life to 10 million cycles at 100 MPa. Incentives in Europe for vehicles with a curb weight of under 1,000 kg add extra impetus for Mg penetration.
The automotive component accounted for 62.55% of the gravity die casting market size in 2025, primarily due to long-term contracts for engine blocks and transmission housings. In contrast, the aerospace parts are forecasted to grow at the fastest rate, with a 4.61% CAGR from 2026 to 2031. Automakers shifting to hybrid and battery platforms are maintaining gravity-cast engine blocks for range-extender modules and larger turbo-diesel programs aimed at commercial pickups. Structural vehicle parts, such as subframes and suspension knuckles, often justify gravity casting when the strength requirements exceed those of HPDC alloys.
In aerospace, cast aluminum ribs and winglet fittings reduce machining waste compared to billet routes, presenting a compelling cost case as airlines ramp up deliveries after a 2020-2023 downturn. Defense programs seeking higher thrust-to-weight turbines are evaluating gravity-cast super-alloy stator vanes that replace costlier investment-castings. Electronics castings are another bright spot; 5G base-station housings demand EMI shielding and thermal paths that gravity cast aluminum provides more efficiently than extruded boxes.
Complete Report Scope:
- By Material Type
- Aluminum Alloys
- Zinc Alloys
- Magnesium Alloys
- By Application
- Automotive Components
- Electrical and Electronics
- Aerospace Parts
- Industrial Machinery
- Consumer Goods
- By Product Type
- Engine Blocks
- Transmission Housings
- Wheels
- Die-Cast Housings
- Structural Components
- Others
- By Process Type
- Standard Gravity Die Casting
- Tilt-Pouring Gravity Die Casting
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Turkey
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific held 46.78% of the gravity die casting market share in 2025, anchored by China's extensive alloy supply chain and vertically integrated casting clusters. Regional governments subsidize Industry 4.0 retrofits that embed sensors in ladles and dies, driving digital adoption faster than in Europe. Japan's aerospace and precision electronics sectors sustain premium demand for high-integrity castings, while South Korea's Tier-1 suppliers leverage robotics to export e-axle housings to US transplants.
South America is expected to record the fastest CAGR of 4.78% through 2031, driven by automotive nearshoring to Brazil and Mexico as the United States OEMs diversify their sourcing. Mining expansions in Chile and Peru require large crusher frames and excavator arms, which favor thick-section, gravity-cast components over fabricated ones. Local content mandates in Brazil stimulate regional die design centers, shortening lead times and lowering import duties on critical tooling. North America prioritizes automation to counter skilled labor shortages, with Michigan and Ontario plants installing robotic tilt-pour lines linked to cloud-based quality dashboards. Environmental permitting processes remain comparatively lenient versus EU rules, yet rising energy costs encourage closed-loop furnace heat recovery projects. Europe tightens VOC and dust rules, raising compliance costs but creating opportunities for exporting low-carbon aluminum castings. The Middle East and Africa are emerging as key markets, focusing on aircraft MRO parts and defense shells.
- Nemak SAB de CV
- Endurance Technologies Ltd.
- Ryobi Ltd.
- Pace Industries LLC
- Bocar SA de CV
- Sundaram-Clayton Ltd.
- Shiloh Industries Inc.
- LTH Castings
- Rockman Industries
- Linamar Corporation
- Koch Enterprises (Gibbs)
- Hitchiner Mfg. Co.
- ATA Casting Technology Co.
- Georg Fischer AG
- Sunrise Metal Technology
- Alcoa Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Automotive and EV Lightweighting Push
- 4.2.2 Adoption of High-Strength Gravity-Cast Alloys
- 4.2.3 Regulatory Fuel-Efficiency Mandates
- 4.2.4 Automation and Tilt-Pour Productivity Gains
- 4.2.5 EU BAT-Driven Low-VOC Compliance Demand
- 4.2.6 AM-Enabled Complex Core Designs
- 4.3 Market Restraints
- 4.3.1 HPDC Substitution in High-Volume Parts
- 4.3.2 Aluminum and Mg Price Volatility
- 4.3.3 Skilled-Operator Shortage for Tilt-Pour Lines
- 4.3.4 OEM Giga Casting Cannibalization Risk
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value (USD))
- 5.1 By Material Type
- 5.1.1 Aluminum Alloys
- 5.1.2 Zinc Alloys
- 5.1.3 Magnesium Alloys
- 5.2 By Application
- 5.2.1 Automotive Components
- 5.2.2 Electrical and Electronics
- 5.2.3 Aerospace Parts
- 5.2.4 Industrial Machinery
- 5.2.5 Consumer Goods
- 5.3 By Product Type
- 5.3.1 Engine Blocks
- 5.3.2 Transmission Housings
- 5.3.3 Wheels
- 5.3.4 Die-Cast Housings
- 5.3.5 Structural Components
- 5.3.6 Others
- 5.4 By Process Type
- 5.4.1 Standard Gravity Die Casting
- 5.4.2 Tilt-Pouring Gravity Die Casting
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 South Africa
- 5.5.5.4 Turkey
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Nemak SAB de CV
- 6.4.2 Endurance Technologies Ltd.
- 6.4.3 Ryobi Ltd.
- 6.4.4 Pace Industries LLC
- 6.4.5 Bocar SA de CV
- 6.4.6 Sundaram-Clayton Ltd.
- 6.4.7 Shiloh Industries Inc.
- 6.4.8 LTH Castings
- 6.4.9 Rockman Industries
- 6.4.10 Linamar Corporation
- 6.4.11 Koch Enterprises (Gibbs)
- 6.4.12 Hitchiner Mfg. Co.
- 6.4.13 ATA Casting Technology Co.
- 6.4.14 Georg Fischer AG
- 6.4.15 Sunrise Metal Technology
- 6.4.16 Alcoa Corporation
7 Market Opportunities and Future Outlook

