PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114488

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114488
Die Casting Machinery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the die casting machinery market size is expected to grow from USD 3.83 billion in 2025 to USD 4.06 billion in 2026 and is forecast to reach USD 5.46 billion by 2031 at 6.09% CAGR over 2026-2031.
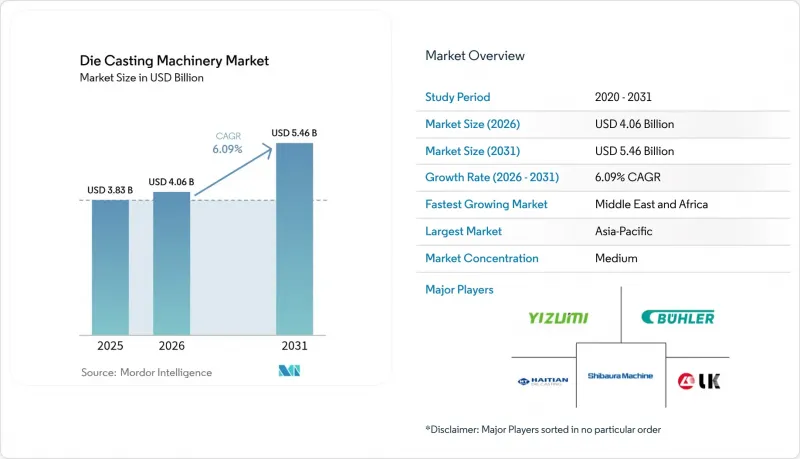
This report is Segmented by Machine Type (Hot Chamber Die Casting Machines and Cold Chamber Die Casting Machines), Material Type (Aluminum and More), End-User Industry (Automotive, Electrical and Electronics, and More), Punching Capacity (Below 50 Tons and More), Automation Level (Manual, Semi-Automated, and Fully Automated), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Die Casting Machinery Market Trends and Insights
EV-Led Mega-/Giga-Casting Demand Surge
High-tonnage presses produce single-piece rear underbody castings, replacing multiple components and streamlining production. Tesla's program success encouraged Ford, Volvo, and GM to commit to structural architectures that depend on giga-press supplies throughout the vehicle lifecycle. Chinese OEMs such as Wanfeng Aowe are expanding magnesium mega-cast trials, aiming to capitalize on chassis-integrated battery packs. As competition intensifies, the die casting machinery market is bifurcating into two distinct segments: conventional mid-tonnage lines and high-investment giga-press setups, which are tailored for significant structural components. Demand visibility extends beyond 2030 as battery-to-chassis integration becomes a design standard, ensuring multi-plant investment waves across three continents.
Electronics Miniaturization Boosting Hot-Chamber Demand
As semiconductor packaging evolves, the demand for precise die casting solutions surges. With bump pitches tightening, there's a heightened demand for casings and heat-spreaders that boast tight machining tolerances. To meet these exacting standards, fast-cycle hot-chamber systems, particularly those utilizing zinc and magnesium, are gaining traction. Foundries supporting major players like TSMC and Intel are adopting multi-slide casting cells, which offer superior melt temperature control and rapid cycle times to meet the needs of modern electronics manufacturing. In 5G infrastructure, large-scale magnesium casting lines are supplying lightweight components, such as antenna housings, which reinforces the case for hot-chamber casting technologies. Emerging applications in diamond semiconductors and quantum computing are expected to demand advanced thermal management, further solidifying the relevance of hot-chamber systems. Their quick adaptability to various product types makes them ideal for high-mix production environments that require flexibility and precision.
Aluminum and Magnesium Price Volatility
LME aluminum prices fluctuated between USD 2,100 and USD 2,400 per metric ton during 2024, while magnesium prices gyrated even more sharply due to heavy Chinese supply concentration. Raw materials, a significant cost component for finished components, are pressuring casting margins. Foundries are adopting hedging strategies to manage volatility. Despite higher production volumes, some manufacturers face revenue declines due to fluctuating input costs. Energy costs, particularly electricity for melt furnaces, have a significant impact on profitability. Price spikes lead to immediate financial strain. Foundries are using short-term measures, such as dual sourcing and alloy substitution, but these offer only temporary relief. Persistent cost instability is dampening investment in the die casting machinery market, with stakeholders adopting cautious approaches despite ongoing technological advancements.
Other drivers and restraints analyzed in the detailed report include:
- Industry 4.0 Retrofits Replacing Legacy Presses
- EU BAT-2024 Compliance Driving Energy-Efficient Upgrades
- Grid Amperage Deficits in Emerging Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cold-chamber units accounted for 63.72% of the die casting machinery market share in 2025, reflecting their suitability for high-temperature aluminum alloys. Hot-chamber machines, while smaller in installed base, are tracking a 6.58% CAGR as electronics contracts escalate. The die casting machinery market size attached to giga-press cold-chamber lines is growing as OEMs transition to single-piece EV body castings, driving the average tonnage upward. Integrated servo shot systems and closed-loop cooling now appear on both machine classes, signaling feature convergence.
In hot-chamber niches, zinc multi-slide platforms meet 30-second takt-time mandates for 5G radio casings, whereas magnesium systems win where weight trimming outranks corrosion concerns. Industry 4.0 modules retrofit across both types, collecting melt and plunger data for cloud analytics. Heat-recovery options and hybrid drive hydraulics cut power draw, improving total cost of ownership. As quality tolerance windows shrink, both machine types embrace inline X-ray and ultrasonic inspection to verify near-net geometry at the press exit. Dual-supplier sourcing strategies by OEMs sustain demand diversity across the die casting machinery market.
Aluminum held a commanding 72.75% share of the 2025 die casting machinery market size due to its favorable strength-to-weight ratio for EV platforms. Magnesium, which is 35% lighter, is on track for a 7.42% CAGR through 2031 as telecom gear and laptop frames pursue weight savings. Automotive giga-casting still relies on aluminum for crash energy absorption, but interior brackets and steering wheels are increasingly being made from magnesium.
Zinc remains vital for intricately detailed hardware and MEMS housings, as it is favored for its dimensional stability at low cycle times. New alloy families, such as aluminum-scandium, improve weldability in battery enclosures, broadening the application scope. Volatility in base-metal pricing prompts users to blend alloys based on forward contracts, but performance needs increasingly trump cost factors for mission-critical parts. Continuous melt-quality monitoring facilitates switching between alloys without contaminating holding furnaces, a practice gaining traction across the die-casting machinery market.
Complete Report Scope:
- By Machine Type
- Hot Chamber Die Casting Machines
- Cold Chamber Die Casting Machines
- By Material Type
- Aluminum
- Zinc
- Magnesium
- Others
- By End-User Industry
- Automotive
- Electrical and Electronics
- Aerospace
- Industrial Manufacturing
- Others
- By Punching Capacity
- Below 50 Tons
- 50 - 100 Tons
- Above 100 Tons
- By Automation Level
- Manual
- Semi-Automated
- Fully Automated
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Turkey
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific secured 46.55% of 2025 revenue, lifted by China's cost-efficient supply chain and India's ascending EV assembly footprint. Japanese firms sustain premium machine exports and diamond semiconductor research and development, undergirding regional innovation. South Korea's packaging giants are reinforcing demand for hot-chamber equipment, while ASEAN nations are incubating contract manufacturing hubs for mid-capacity lines.
Europe's growth rests on compliance-driven replacement as BAT-2024 forces energy-wasteful presses off the floor. Germany's ReGAIN consortium serves as a pilot, merging AI assistants with low-carbon electricity contracts. Italy's Lombardy cluster adopts conformal-cooling tooling at scale, while Nordic foundries push closed-loop water systems to align with strict emissions caps.
The Middle East and Africa, although still in its early stages in terms of absolute volume, is expected to record a 7.74% CAGR as economic diversification blueprints finance aluminum smelters, grid upgrades, and skill academies. Saudi Arabia's Vision 2030 triggers local automotive component programs, and Egypt courts electronics assemblers seeking tariff-free access to the EU. Grid limitations still hinder giga-press rollouts, but modular micro-grids and solar cogeneration projects aim to unlock large-scale press opportunities in the coming decade. North America trails Asia in tonnage additions but benefits from EV tax incentives that favor domestic structural casting capacity. Reshoring campaigns and Buy American clauses further bolster the regional share of the die casting machinery market.
- Buhler Group
- L.K. Technology Holdings Limited
- Shibaura Machine
- Haitian Die Casting
- Yizumi Holdings Co., Ltd.
- ItalpresseGauss
- Toyo Machine Manufacturing Co., Ltd
- UBE Machinery Inc.
- Birch Machinery Company
- Guangdong Hongtu Technology (Holdings) Co.,Ltd.
- Colosio Srl
- Zitai Precision Machinery Co., Ltd.
- Suzhou Sanji Foundry Equipment Co.,Ltd
- Wuxi Xinjiasheng
- Pace Industries LLC
- Dynacast (Form Technologies)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EV-Led Mega-/Giga-Casting Demand Surge
- 4.2.2 Electronics Miniaturization Boosting Hot-Chamber Demand
- 4.2.3 Industry 4.0 Retrofits Replacing Legacy Presses
- 4.2.4 EU BAT-2024 Compliance Driving Energy-Efficient Upgrades
- 4.2.5 Brown-Field Rheocasting Retro-Kits for Structural Parts
- 4.2.6 Additive Manufactured Conformal Dies Cutting Change-Over Time
- 4.3 Market Restraints
- 4.3.1 Aluminum and Mg Price Volatility
- 4.3.2 EUR 10 m-Plus Giga-Press CAPEX Barrier
- 4.3.3 Grid Amperage Deficits in Emerging Markets
- 4.3.4 Short Supply of Ultra-Premium Hot-Work Tool Steels
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value, USD)
- 5.1 By Machine Type
- 5.1.1 Hot Chamber Die Casting Machines
- 5.1.2 Cold Chamber Die Casting Machines
- 5.2 By Material Type
- 5.2.1 Aluminum
- 5.2.2 Zinc
- 5.2.3 Magnesium
- 5.2.4 Others
- 5.3 By End-User Industry
- 5.3.1 Automotive
- 5.3.2 Electrical and Electronics
- 5.3.3 Aerospace
- 5.3.4 Industrial Manufacturing
- 5.3.5 Others
- 5.4 By Punching Capacity
- 5.4.1 Below 50 Tons
- 5.4.2 50 - 100 Tons
- 5.4.3 Above 100 Tons
- 5.5 By Automation Level
- 5.5.1 Manual
- 5.5.2 Semi-Automated
- 5.5.3 Fully Automated
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Rest of North America
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 South Africa
- 5.6.5.4 Turkey
- 5.6.5.5 Rest of Middle East and Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Buhler Group
- 6.4.2 L.K. Technology Holdings Limited
- 6.4.3 Shibaura Machine
- 6.4.4 Haitian Die Casting
- 6.4.5 Yizumi Holdings Co., Ltd.
- 6.4.6 ItalpresseGauss
- 6.4.7 Toyo Machine Manufacturing Co., Ltd
- 6.4.8 UBE Machinery Inc.
- 6.4.9 Birch Machinery Company
- 6.4.10 Guangdong Hongtu Technology (Holdings) Co.,Ltd.
- 6.4.11 Colosio Srl
- 6.4.12 Zitai Precision Machinery Co., Ltd.
- 6.4.13 Suzhou Sanji Foundry Equipment Co.,Ltd
- 6.4.14 Wuxi Xinjiasheng
- 6.4.15 Pace Industries LLC
- 6.4.16 Dynacast (Form Technologies)
7 Market Opportunities and Future Outlook

