PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114658

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114658
Mining Lubricants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the mining lubricants market size was valued at 1.75 billion liters in 2025 and estimated to grow from 1.79 billion liters in 2026 to reach 2.01 billion liters by 2031, at a CAGR of 2.30% during the forecast period (2026-2031).
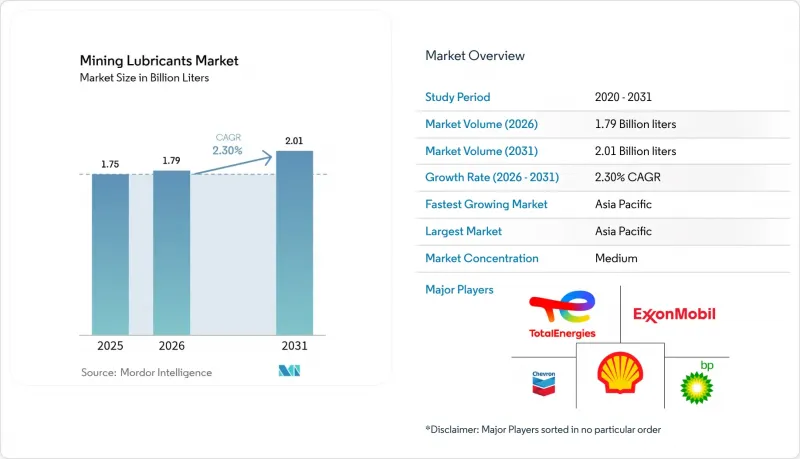
This report is Segmented by Base Stock (Mineral Oil, Other Base Stocks), Product Type (Engine Oil, Gear Oil, Hydraulic Fluids, Transmission Fluids, Other Product Types), and Geography (Asia-Pacific, North America, Europe, South America, Middle East and Africa). The Market Forecasts are Provided in Terms of Volume (Liters).
Global Mining Lubricants Market Trends and Insights
Expansion of Coal-Rich Mining Activities
Coal mine expansions extend fleet operating hours and raise lubricant loads as producers in Australia, China, India, and the United States keep thermal-coal output stable despite decarbonization pressure. Australia doubled mining-sector investment to lift iron ore and coal capacity, reinforcing volume demand for heavy-duty engine oils and greases used in draglines and haul trucks. Canadian oil-sands production climbed to 1.9 million b/d in late-2024, and debottlenecking projects raised upgrader capacity to 600,000 b/d, spurring lubricant needs for extreme-temperature and high-contamination conditions. Bigger equipment in coal pits relies on high-performance lubricants with longer service intervals to cut unscheduled stoppages. Yet global coal demand uncertainties tied to power-sector decarbonization may cap the longevity of this driver.
Rapid Capacity Additions in Hard-Rock Mines
New copper, gold, and rare-earth pits deploy automated, high-pressure equipment operating deeper underground, intensifying lubricant complexity. Operators install sensor-laden hydraulic shovels and high-ratio gearboxes that necessitate synthetic oils with superior thermal stability. Liebherr's zero-emission excavation roadmap, targeting fossil-free systems by 2030, illustrates the shift to electric and hybrid drive trains that still depend on tailored lubricants for transmissions and bearing sets. Predictive-maintenance platforms feed real-time friction and temperature data to optimize change intervals, reducing waste while safeguarding uptime. As hard-rock expansions proliferate in Chilean copper belts and Western Australian goldfields, specialized lubricants that manage high loads and temperature spikes command premium pricing.
Crude-Price Volatility Inflating Base-Oil Costs
Lubricant producers face margin pressure when crude prices spike since Group-II base stocks track petroleum benchmarks. Shell's conversion of a German hydrocracker to 300,000 t/y of Group-III base oils improves regional supply resilience and trims carbon emissions by 620,000 t/y, but cost pass-throughs to mine operators remain inevitable. Miners offset volatility by adopting condition-based maintenance that cuts oil use, pressuring suppliers to balance pricing with value-added technical support. Premium synthetics partially hedge margin swings through higher per-liter value.
Other drivers and restraints analyzed in the detailed report include:
- Modern, High-Horsepower Equipment Boosting Lube Intensity
- Autonomous Haulage Requiring Smart Centralized Lubrication
- Longer Drain Intervals from Real-Time Condition Monitoring
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Mineral oils retained 66.58% mining lubricants market share in 2025 owing to cost advantages and established supply. Synthetic variants, however, accelerate at a 3.03% CAGR to 2031 as high-horsepower machinery, deeper pits, and ambient extremes outstrip mineral capabilities. The synthetic slice of the mining lubricants market size benefits from stable viscosity, oxidation resistance, and extended drains that reduce service downtime. Chevron's heavy-duty synthetic and semi-synthetic rollout underscores OEM endorsement for longer-life fluids that deliver fuel efficiency gains. Bio-based lubricants remain a niche but grow where environmental permits require stringent biodegradability, particularly in Arctic, Amazon, and island mines.
The premium nature of synthetics narrows the cost differential versus mineral alternatives as drain intervals stretch, improving lifecycle economics. Coupled with autonomous haulage, synthetics' superior film retention lowers bearing failures, justifying higher upfront price and tilting procurement toward performance-based contracts that reward uptime.
Complete Report Scope:
- By Base Stock
- Mineral Oil
- Other Base Stocks (Synthetic Oils, Bio-based, etc.)
- By Product Type
- Engine Oil
- Gear Oil
- Hydraulic Fluids
- Transmission Fluids
- Other Product Types (Greases, Compressor Oils, etc.)
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific's 39.28% mining lubricants market share in 2025 reflects massive mineral output in Australia, Indonesia, and India. Ongoing investment keeps iron-ore and coal exports flowing from the Pilbara and Kalimantan, sustaining demand despite China's property slowdown. The Reserve Bank of Australia noted a doubling of mining capital expenditures that underpin lubricant volumes. Shell's grease plant in Thailand tripled to 15,000 t/y, becoming Southeast Asia's largest and anchoring regional supply. ExxonMobil's 20,000 b/d base-oil expansion in Singapore supplies advanced EHC grades and bolsters feedstock security. While China's import pull eases, India's urban growth helps compensate, anchoring a 3.68% CAGR through 2031.
North America remains technologically advanced, with autonomous fleets in Canadian oil sands and US copper pits pushing uptake of IoT-linked lubrication. Shell-Whitmore's joint venture offers turnkey reliability solutions spanning greases, oils, and automated delivery hardware, enhancing operational uptime for mine operators. Record 1.9 million b/d oil-sands production in 2024 and upgrader capacity hikes translate into steady lubricant demand across extreme cold operations. Environmental scrutiny encourages biodegradable fluids in regions adjacent to waterways, fostering niche synthetic and bio-oil uptake.
Europe's smaller mining footprint limits volume but leads in environmental compliance, driving early adoption of EU Ecolabel-certified lubricants. Shell's German base-oil project will meet 40% of domestic demand and 9% of EU requirements, easing Group-III supply tightness and cutting emissions. Scandinavian and Iberian mines fit advanced condition monitoring that extends drain intervals, underscoring the shift from litres sold to uptime delivered. The region's focus on circularity and carbon cuts positions high-performance synthetics and bio-oils for growth despite sluggish overall mining output.
- BP p.l.c.
- Chevron Corporation
- China Petrochemical Corporation (Sinopec)
- Engen Petroleum (PTY) LTD
- Exxon Mobil Corporation
- Freudenberg
- FUCHS
- Gulf Oil International
- Idemitsu Kosan Co.,Ltd.
- LUKOIL
- Petro-Canada Lubricants Inc.
- PetroChina Company Limited
- Quaker Houghton
- Shell plc
- Suncor Energy Inc.
- TotalEnergies
- Valvoline
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of coal-rich mining activities
- 4.2.2 Rapid capacity additions in hard-rock mines
- 4.2.3 Modern, high-horsepower equipment boosting lube intensity
- 4.2.4 Autonomous haulage requiring smart centralized lubrication
- 4.2.5 Environmental push for biodegradable lubricants in fragile biomes
- 4.3 Market Restraints
- 4.3.1 Crude-price volatility inflating base-oil costs
- 4.3.2 Group-II base-oil supply tightness from refinery rationalization
- 4.3.3 Longer drain-intervals from real-time condition monitoring
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Base Stock
- 5.1.1 Mineral Oil
- 5.1.2 Other Base Stocks (Synthetic Oils, Bio-based, etc.)
- 5.2 By Product Type
- 5.2.1 Engine Oil
- 5.2.2 Gear Oil
- 5.2.3 Hydraulic Fluids
- 5.2.4 Transmission Fluids
- 5.2.5 Other Product Types (Greases, Compressor Oils, etc.)
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 Japan
- 5.3.1.3 India
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Russia
- 5.3.3.7 NORDIC Countries
- 5.3.3.8 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 BP p.l.c.
- 6.4.2 Chevron Corporation
- 6.4.3 China Petrochemical Corporation (Sinopec)
- 6.4.4 Engen Petroleum (PTY) LTD
- 6.4.5 Exxon Mobil Corporation
- 6.4.6 Freudenberg
- 6.4.7 FUCHS
- 6.4.8 Gulf Oil International
- 6.4.9 Idemitsu Kosan Co.,Ltd.
- 6.4.10 LUKOIL
- 6.4.11 Petro-Canada Lubricants Inc.
- 6.4.12 PetroChina Company Limited
- 6.4.13 Quaker Houghton
- 6.4.14 Shell plc
- 6.4.15 Suncor Energy Inc.
- 6.4.16 TotalEnergies
- 6.4.17 Valvoline
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
- 7.2 Growing Demand for High Performance Lubricants

