PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114664

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114664
Space Robots - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
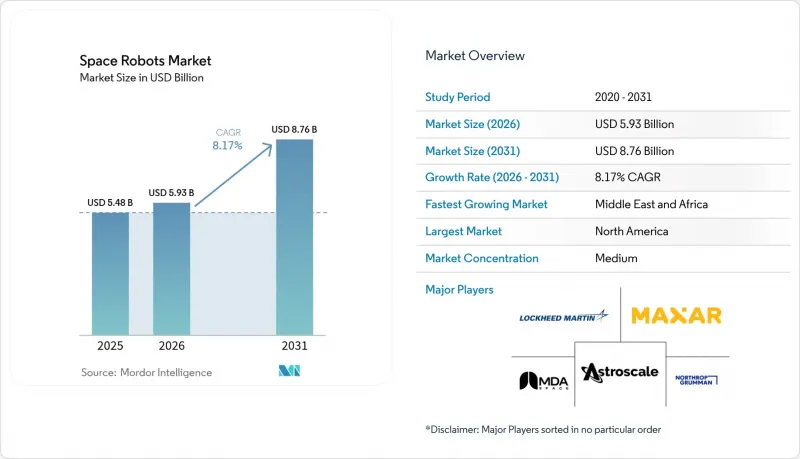
According to Mordor Intelligence, the space robots market size is expected to grow from USD 5.48 billion in 2025 to USD 5.93 billion in 2026 and is forecast to reach USD 8.76 billion by 2031 at 8.17% CAGR over 2026-2031.
This report is Segmented by Product (Rovers/Spacecraft Landers, Robotic Arms/Manipulator Systems, Space Probes, and More), Mission Type (Deep Space and Near Space), Application (Satellite Servicing and Life Extension, and More), End-User (Commercial and Government), Component (Hardware and Software), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Space Robots Market Trends and Insights
Surge in On-Orbit Satellite-Servicing Demand
High replacement costs for geostationary satellites, often surpassing USD 400 million, made life-extension missions economically compelling. Intelsat's 2024 agreement with Starfish Space set a commercial precedent for robotic servicing, with the first mission slated for 2026. Northrop Grumman progressed toward a 2026 robot-armed Mission Extension Pod launch, validating confidence in near-term revenue. Parallel activity at the European Space Agency, which advanced its Geostationary Servicing Vehicle toward a 2028 debut, signaled agency-wide endorsement. Collectively, these milestones underpinned recurring demand for refueling, relocation, and inspection services, boosting predictable cash flows for in-orbit robotics providers.
Government-Funded Lunar and Mars Exploration Programs
NASA's Artemis framework continued to allocate multi-year funding to robotic systems, evidenced by the CADRE rover network that passed integrated testing in March 2025. ESA's Argonaut lunar lander target for 2031 introduced a 1,500 kg cargo capacity, supporting large-scale surface logistics. China accelerated its robotic lunar research outpost timeline by 2035, intensifying technology competition. These parallel programs stimulated demand for rugged manipulators, autonomous navigation software, and modular mobility platforms tailored to harsh lunar and Martian environments.
High Development and Qualification Costs
Space-qualified components required extensive radiation testing, fault-tolerant design, and niche manufacturing, inflating non-recurring engineering expenses. Smaller entrants faced capital hurdles exceeding USD 50 million before first revenue, limiting new competition. Government cost-sharing grants alleviated some burden, yet long design cycles still restrained near-term market acceleration.
Other drivers and restraints analyzed in the detailed report include:
- Falling Launch Costs from Reusable Launchers
- Expansion of Commercial Lunar Logistics Corridors
- Export-Control Complexities
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Robotic arms dominated 2025 revenue, generating 41.72% of total sales from critical station maintenance and satellite capture assets. The space robots market size for manipulator systems is forecast to expand steadily through 2031 on the back of the Canadarm3 program. Complex joints, multi-sensor end-effectors, and radiation-hardened electronics supported premium pricing. Growth also stemmed from planetary rovers using lightweight arm variants to collect regolith and deploy instruments.
On-orbit servicing vehicles posted the quickest 9.33% CAGR outlook, reflecting operator interest in modular spacecraft hosting robotic arms and refueling pods. Service providers secured anchor customers through multi-year performance-based contracts, signaling confidence in pay-per-thrust business models. Gripping and docking mechanisms gained traction as agencies converged on standard interfaces, while emerging concepts such as surgical robots aboard the ISS captured niche R&D budgets.
Near-space activities within Earth's gravitational sphere attained a 65.12% market share in 2025 thanks to high satellite density and immediate revenue opportunities. Robust demand for inspection, relocation, and station upkeep kept fleet operators focused on reliable robotic assets. As governments prioritize orbital safety, the market share for space robots for near-space platforms will remain elevated through mid-decade.
Deep-space missions recorded a smaller base but posted a leading 9.86% CAGR forecast. Investments in autonomous navigation, radiation-tolerant actuators, and adaptive AI allowed spacecraft to operate with longer communication delays. NASA's Mars Ascent Vehicle program advanced reinforcement-learning algorithms for off-world ascent guidance. ESA's 2028 ExoMars Rosalind Franklin rover and China's sample-return initiatives defined sustained demand for sophisticated robotic explorers.
Complete Report Scope:
- By Product
- Rovers/Spacecraft Landers
- Robotic Arms/Manipulator Systems
- Space Probes
- Gripping and Docking Systems
- On-Orbit Servicing Vehicles
- Others Products
- By Mission Type
- Deep Space
- Near Space
- By Application
- Satellite Servicing and Life Extension
- Active Debris Removal
- On-Orbit Assembly and Manufacturing
- Exploration and Scientific Research
- Cargo and Logistics
- By End-User
- Commercial
- Commercial Satellite Operators
- Research Institutes
- NewSpace Start-ups
- Government
- Space Agencies
- Defence and Intelligence
- Commercial
- By Component
- Hardware
- Manipulators
- Structural and Mobility Platform
- Sensor and Vision Systems
- Power Subsystems
- Commuincation System
- Software
- Autonomy and Navigation Software
- Sensor Fusion and Data Processing
- Commuincation and Data Management Software
- Others
- Hardware
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- Israel
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained a 55.97% market share in 2025, supported by NASA's Artemis contracting pipeline and a vibrant commercial launch ecosystem. In June 2025, SpaceX secured a USD 843 million contract to build an ISS deorbit vehicle. Canadian expertise in robotic manipulators, anchored by MDA Space's Canadarm heritage, further reinforced regional leadership.
Asia-Pacific sustained strong double-digit growth as China funded six-legged asteroid-mining robots to cut reliance on terrestrial rare metals. Japan's JAXA awarded GITAI a concept study for a lunar rover arm in April 2025. India prepared its next generation of autonomous lunar rovers, while Australian startups explored robotic regolith processing, collectively widening the regional supplier base.
The Middle East and Africa region achieved the fastest 11.78% CAGR outlook. The UAE advanced sovereign AI-enabled spacecraft through state-backed programs, including secure communication contracts worth USD 5.1 billion. The African Space Agency, inaugurated in Cairo in May 2025, coordinated continental R&D objectives for satellite production and orbital debris management.
Europe maintained stable expansion, supported by ESA's PERASPERA initiative, which pooled EU funding for modular servicing vehicles and dexterous manipulators. Regulatory clarity under the EU Space Law proposal bolstered investor confidence in cross-border robotics projects. Cooperative missions such as Hera, targeting asteroid-deflection rehearsals with robotic probes, underscored the region's emphasis on planetary defense.
South America represented an early-stage opportunity. Brazil renewed discussions with ESA on hosting autonomous robotic testbeds at the Alcantara launch site, yet funding constraints limited near-term deliveries. Emerging public-private consortia signaled intent to participate once launch prices ease.
- Northrop Grumman Corporation
- Maxar Technologies Holdings Inc.
- Lockheed Martin Corporation
- MDA Space Ltd.
- Astroscale Holdings Inc.
- Blue Origin Enterprises, L.P.
- Redwire Corporation
- ASTROBOTIC TECHNOLOGY, INC.
- GITAI USA Inc.
- Starfish Space Inc.
- D-Orbit S.p.A
- ClearSpace SA
- Metecs, LLC.
- Motiv Space Systems, Inc.
- Space Applications Services NV/SA
- Oceaneering International, Inc.
- iSpace, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in on-orbit satellite-servicing demand
- 4.2.2 Government-funded lunar and Mars exploration programs
- 4.2.3 Falling launch costs from reusable launchers
- 4.2.4 Expansion of commercial lunar logistics corridors
- 4.2.5 Growth in in-space manufacturing and 3-D printing needs
- 4.2.6 Defense-led demand for autonomous ISR rendezvous
- 4.3 Market Restraints
- 4.3.1 High development and qualification costs
- 4.3.2 Export-control (ITAR/EAR) complexities
- 4.3.3 Legal liability over active-debris-removal missions
- 4.3.4 Lack of open interface standards for servicing ports
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product
- 5.1.1 Rovers/Spacecraft Landers
- 5.1.2 Robotic Arms/Manipulator Systems
- 5.1.3 Space Probes
- 5.1.4 Gripping and Docking Systems
- 5.1.5 On-Orbit Servicing Vehicles
- 5.1.6 Others Products
- 5.2 By Mission Type
- 5.2.1 Deep Space
- 5.2.2 Near Space
- 5.3 By Application
- 5.3.1 Satellite Servicing and Life Extension
- 5.3.2 Active Debris Removal
- 5.3.3 On-Orbit Assembly and Manufacturing
- 5.3.4 Exploration and Scientific Research
- 5.3.5 Cargo and Logistics
- 5.4 By End-User
- 5.4.1 Commercial
- 5.4.1.1 Commercial Satellite Operators
- 5.4.1.2 Research Institutes
- 5.4.1.3 NewSpace Start-ups
- 5.4.2 Government
- 5.4.2.1 Space Agencies
- 5.4.2.2 Defence and Intelligence
- 5.4.1 Commercial
- 5.5 By Component
- 5.5.1 Hardware
- 5.5.1.1 Manipulators
- 5.5.1.2 Structural and Mobility Platform
- 5.5.1.3 Sensor and Vision Systems
- 5.5.1.4 Power Subsystems
- 5.5.1.5 Commuincation System
- 5.5.2 Software
- 5.5.2.1 Autonomy and Navigation Software
- 5.5.2.2 Sensor Fusion and Data Processing
- 5.5.2.3 Commuincation and Data Management Software
- 5.5.2.4 Others
- 5.5.1 Hardware
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Russia
- 5.6.3.5 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 Israel
- 5.6.5.1.3 United Arab Emirates
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Northrop Grumman Corporation
- 6.4.2 Maxar Technologies Holdings Inc.
- 6.4.3 Lockheed Martin Corporation
- 6.4.4 MDA Space Ltd.
- 6.4.5 Astroscale Holdings Inc.
- 6.4.6 Blue Origin Enterprises, L.P.
- 6.4.7 Redwire Corporation
- 6.4.8 ASTROBOTIC TECHNOLOGY, INC.
- 6.4.9 GITAI USA Inc.
- 6.4.10 Starfish Space Inc.
- 6.4.11 D-Orbit S.p.A
- 6.4.12 ClearSpace SA
- 6.4.13 Metecs, LLC.
- 6.4.14 Motiv Space Systems, Inc.
- 6.4.15 Space Applications Services NV/SA
- 6.4.16 Oceaneering International, Inc.
- 6.4.17 iSpace, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

