PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114713

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114713
Bioanalytical Testing Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, bioanalytical testing services market size in 2026 is estimated at USD 4.68 billion, growing from 2025 value of USD 4.29 billion with 2031 projections showing USD 7.23 billion, growing at 9.08% CAGR over 2026-2031.
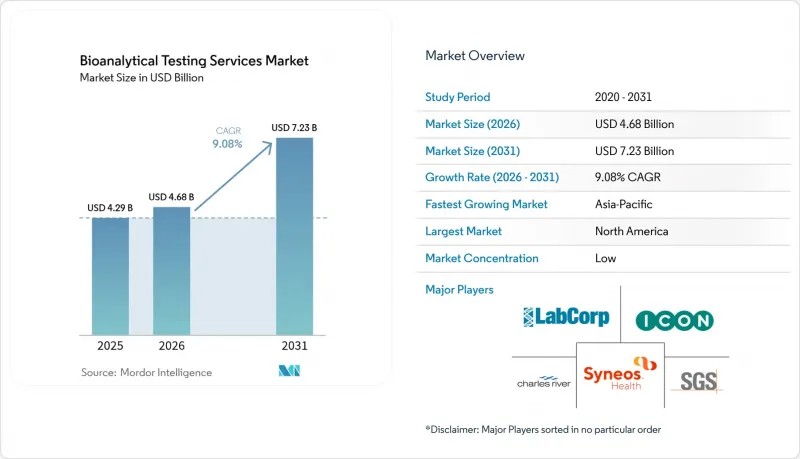
This report is Segmented by Molecule Type (Small Molecules, Large Molecules), Test Type (Bioavailability & Bioequivalence, Pharmacokinetics, and More), End User (Pharmaceutical Companies, Biopharmaceutical & Biotech Firms, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Bioanalytical Testing Services Market Trends and Insights
Rising outsourcing of analytical testing
Pharmaceutical sponsors are reallocating capital from fixed laboratories to flexible, tech-enabled partnerships, lifting outsourcing penetration to unprecedented levels. Biologics workflows requiring sub-ppm impurity detection and multiplex ligand-binding assays now sit almost entirely with CROs. Pandemic restrictions intensified the shift as in-house labs shut down while CRO networks stayed operational through disaster-recovery protocols. Access to high-resolution mass spectrometers costing USD 500,000 per unit and automated sample-preparation robots remains a decisive factor for smaller biotech firms seeking rapid data readouts.
Expansion of biologics & biosimilars pipeline
Large-molecule approvals comprised 46% of FDA clearances in 2025, propelled by monoclonal antibodies, fusion proteins, and antibody-drug conjugates that require orthogonal assays to evaluate potency, glycosylation, and host-cell-protein content. Over 240 biosimilars are in active development, reinforcing demand for comparative analytics that focus on molecular similarity rather than expensive efficacy trials. Regulators such as the UK MHRA signal readiness to waive certain efficacy studies when analytical evidence is compelling, accelerating uptake of advanced biophysical techniques and multivariate statistics.
Complex & rapidly-evolving global regulations
Differing regional expectations continue to generate multi-protocol validation plans, inflating development budgets by 15-20%. Potential FDA oversight of laboratory-developed tests (LDTs) will pull clinical labs into drug-style GMP systems, demanding capital upgrades in documentation, change control, and data-integrity architecture. Smaller providers lacking embedded regulatory teams face competitive headwinds as compliance overhead rises.
Other drivers and restraints analyzed in the detailed report include:
- Growing global clinical-trial volumes
- Stringent PK/PD & BE regulatory mandates
- Shortage of skilled bioanalytical scientists
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Large molecules generated rapid momentum, even though small molecules still held 63.62% of the bioanalytical testing services market share in 2025. The large-molecule segment is expanding at an 11.12% CAGR due to monoclonal antibodies, fusion proteins, and peptide therapeutics that necessitate ligand-binding assays, cell-based potency tests, and immunogenicity evaluations. This demand compels laboratories to install high-throughput Gyrolab immunoassay platforms and multi-attribute-method mass-spectrometry workflows that identify structural variants within minutes.
Investment intensity continues to rise. WuXi AppTec, for example, lifted peptide-manufacturing capacity to 32,000 L of solid-phase synthesis reactors, underpinning a surge in comparative analytical requests from biosimilar developers. Sponsors favor analytical similarity packages over long efficacy studies, pushing advanced orthogonal techniques into routine service. As the pipeline diversifies, the bioanalytical testing services market will rely heavily on cross-disciplinary skillsets spanning biochemistry, statistics, and automation to match rising complexity.
Complete Report Scope:
- By Molecule Type
- Small Molecules
- Large Molecules
- By Test Type
- Bioavailability & Bioequivalence
- Pharmacokinetics
- Pharmacodynamics
- Absorption-Distribution-Metabolism-Excretion
- Immunogenicity & Neutralizing-Antibody Assays
- Biomarker & Omics-Based Assays
- Other Tests
- By End User
- Pharmaceutical Companies
- Biopharmaceutical & Biotech Firms
- Contract Development & Manufacturing Organizations
- Academic & Government Institutes
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 41.92% of global revenue in 2025, underpinned by concentrated pharmaceutical headquarters, FDA proximity, and extensive GLP infrastructure. Major providers such as Labcorp deploy more than 14,000 employees across domestic labs that underpin top-selling drug programs. Yet, talent shortages and elevated labor costs pressure margins and drive selective outsourcing to lower-cost regions. Canadian facilities complement US capacity with bilingual submissions, while Mexico's near-shoring momentum is prompting fresh investment in GLP sites aligned with US import rules.
Europe ranks second due to cohesive EMA frameworks and leadership in biosimilars. Germany, France, and the United Kingdom host clusters of CRO and CDMO facilities that collaborate with academic hubs, and Eurofins Scientific alone runs over 900 European laboratories performing 450 million tests annually. Post-Brexit, the UK fast-tracked biosimilar pathways to sustain competitiveness, demonstrating a flexible regulatory posture that continues to attract biopharma analytical work. EU investments in biopharmaceutical manufacturing hubs and Horizon Europe R&D grants will keep demand buoyant. Asia-Pacific represents the fastest-growing zone at 11.74% CAGR, driven by clinical-trial migration, expanding manufacturing capacity, and supportive government incentives. China leads sample volumes as local CROs scale capacity, while Japan's status as the third-largest pharmaceutical market ensures a steady flow of complex submissions requiring bilingual documentation. South Korea and Taiwan leverage tax credits and expedited reviews, luring multinationals searching for efficient enrollment and cost controls. India's national push for GLP compliance and Australia's biotechnology cluster diversify regional capabilities. As a result, the bioanalytical testing services market will see APAC revenue converge with Western levels during the second half of the decade.
- LabCorp
- Charles River
- Thermo Fisher - PPD
- Eurofins
- ICON
- Syneos Health
- SGS
- Intertek Group
- WuXi App Tec
- Medpace Holdings
- BioAgilytix Labs
- Frontage Labs
- Toxikon Corp.
- Covance-Monogram
- Altasciences
- SGS Vitrology
- Eurofin-Advinus
- Analytical Bio-Clear
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Outsourcing of Analytical Testing
- 4.2.2 Expansion of Biologics & Biosimilars Pipeline
- 4.2.3 Growing Global Clinical-Trial Volumes
- 4.2.4 Stringent PK/PD & BE Regulatory Mandates
- 4.2.5 Adoption of Microsampling & DBS in Decentralized Trials
- 4.2.6 AI-Driven Analytics Cutting Assay Turnaround Time
- 4.3 Market Restraints
- 4.3.1 Complex & Rapidly-Evolving Global Regulations
- 4.3.2 Shortage of Skilled Bioanalytical Scientists
- 4.3.3 High Capex for HR-Mass-Spectrometry Platforms
- 4.3.4 Sample-Integrity Risks in At-Home Collections
- 4.4 Porter's Five Forces Analysis
- 4.4.1 Threat of New Entrants
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Bargaining Power of Suppliers
- 4.4.4 Threat of Substitutes
- 4.4.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Molecule Type
- 5.1.1 Small Molecules
- 5.1.2 Large Molecules
- 5.2 By Test Type
- 5.2.1 Bioavailability & Bioequivalence
- 5.2.2 Pharmacokinetics
- 5.2.3 Pharmacodynamics
- 5.2.4 Absorption-Distribution-Metabolism-Excretion
- 5.2.5 Immunogenicity & Neutralizing-Antibody Assays
- 5.2.6 Biomarker & Omics-Based Assays
- 5.2.7 Other Tests
- 5.3 By End User
- 5.3.1 Pharmaceutical Companies
- 5.3.2 Biopharmaceutical & Biotech Firms
- 5.3.3 Contract Development & Manufacturing Organizations
- 5.3.4 Academic & Government Institutes
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Labcorp Drug Development (Covance)
- 6.3.2 Charles River Laboratories
- 6.3.3 Thermo Fisher - PPD
- 6.3.4 Eurofins Scientific
- 6.3.5 ICON plc
- 6.3.6 Syneos Health
- 6.3.7 SGS SA
- 6.3.8 Intertek Group plc
- 6.3.9 WuXi AppTec
- 6.3.10 Medpace Holdings
- 6.3.11 BioAgilytix Labs
- 6.3.12 Frontage Labs
- 6.3.13 Toxikon Corp.
- 6.3.14 Covance-Monogram
- 6.3.15 Altasciences
- 6.3.16 SGS Vitrology
- 6.3.17 Eurofin-Advinus
- 6.3.18 Analytical Bio-Clear
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

