PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114876

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114876
Bleaching Clay - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the bleaching clay market size is expected to grow from 2.38 Million tons in 2025 to 2.49 Million tons in 2026 and is forecast to reach 3.12 Million tons by 2031 at 4.62% CAGR over 2026-2031.
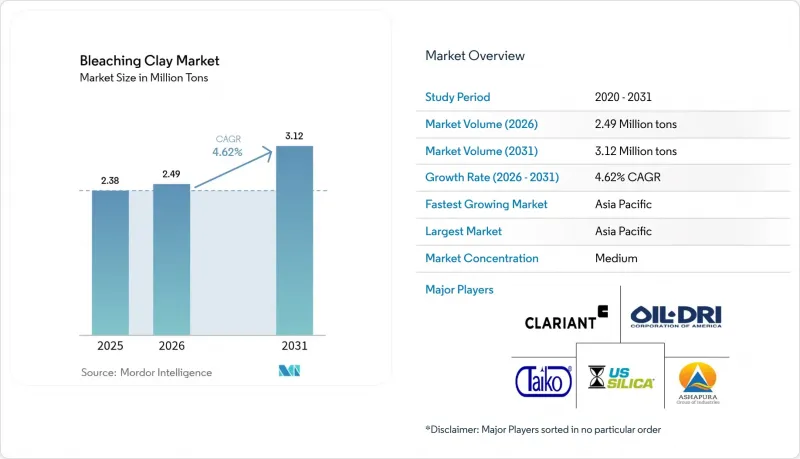
This report is Segmented by Type (Fuller's Earth, Activated Clays, and Activated Bauxite), Application (Mineral Oil and Waxes, Industrial Oil, and Vegetable Oil and Animal Fats), End-User Industry (Food and Beverage Processing, Cosmetics and Personal Care, and More), and Geography (Asia-Pacific, North America, and More). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Bleaching Clay Market Trends and Insights
Accelerating Consumption of Refined Vegetable Oils
Global oilseed output is set to touch 680 million tons in the 2024/25 season, lifting demand for specialized bleaching formulations that remove chlorophyll, carotenoids, and trace metals from solvent-extracted oils. Asia-Pacific refiners, supported by favorable logistics and expanding crushing capacity, represent the largest incremental volume. The segment also benefits from dietary shifts toward soybean and sunflower oil, both of which require higher clay dosage rates than cold-pressed alternatives. Producers that can tailor pore structure for specific oil chemistries capture procurement preference, especially as OPEC projects 19.2 million barrels per day of new refining capacity in developing regions by 2050. This structural uplift secures long-run volume visibility for the bleaching clay market.
Rising Demand from Cosmetics and Personal Care Formulations
Cosmetic brands increasingly replace synthetic absorbents with naturally derived clays to meet clean-label expectations and regulatory pressure over microplastics. High surface area and cation exchange capacity allow bleaching clays to act both as oil absorbers and as stabilizers for ultraviolet filters, encouraging wider use in sun-care and matte-finish products. Clariant's acquisition of Lucas Meyer Cosmetics strengthens value-added supply for this high-margin end-use, evidenced by the firm's Care Chemicals profitability increase in 2024. Premium formulations demand low-heavy-metal content clays, which supports price differentiation and compensates for the smaller tonnage relative to edible oils.
Strict Environmental Regulations on Mining and Acid Activation Waste
EPA discharge revisions and EU hazardous waste designation for spent bleaching earth add USD 50-100 per ton to processing costs, prompting facilities to invest in zero-liquid-discharge systems. Smaller operators struggle to finance such upgrades, leading to capacity rationalization and potential consolidation. Conversely, the push for sustainability accelerates R&D into solvent extraction and pyrolysis routes that recover up to 35% oil from certain clay types, cutting waste volumes and generating secondary products.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Biodiesel and Renewable Diesel Refining
- Increasing Need for Ultra-Low-Sulfur Mineral Oils and Lubricants
- Competition from Synthetic Adsorbents (Silica Gels)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fuller's Earth captured 40.68% of bleaching clay market share in 2025 by delivering 15-20% lower oil loss than attapulgite or sepiolite alternatives, a saving that can reach USD 3 million annually for a refinery processing 1 million tons of soybean oil. The segment benefits from abundant global deposits and simple activation requirements, supporting cost leadership. Activated clays, however, are forecast to outpace Fuller's Earth at 5.21% CAGR as producers refine acid activation to raise surface area beyond 250 m2/g, unlocking higher adsorption capacity essential for pharmaceutical and cosmetic oils. Over the forecast period, refiners will balance unit cost with performance, keeping both segments relevant to the bleaching clay market.
Activated bauxite serves a focused subset of petroleum applications where processing temperatures exceed 200 °C. Although supply is limited, its stable lattice earns preference in transformer oil and aviation lubricant purification. Continued R&D shows that optimal bleaching capacity lies in a 50-60 A average pore radius, encouraging investments in controlled activation technology that narrows performance variance. These advances underpin enduring, if modest, contribution from niche grades to the bleaching clay market size.
Complete Report Scope:
- By Type
- Activated Clays
- Fuller's Earth
- Activated Bauxite
- By Application
- Mineral Oil and Waxes
- Industrial Oil
- Vegetable Oil and Animal Fats
- By End-user Industry
- Food and Beverage Processing
- Cosmetics and Personal Care
- Chemicals
- Other End-user Industries (Energy and Power, etc.)
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific's 47.10% volume share in 2025 stems from vast refining footprints in China, India, Indonesia, and Malaysia, each benefitting from proximity to oilseed production and large consumer markets. The region's 4.95% CAGR forecast links to OPEC-projected incremental refining capacity of up to 4.9 million barrels per day by 2028. Indonesia alone uses roughly 200,000 tons of bentonite annually in cooking-oil refining, illustrating the scale advantage that supports dedicated clay activation facilities. Local universities collaborate with industry on spent earth recycling methods achieving 85% biodiesel yield, reinforcing supply security and environmental compliance.
North America combines technological leadership with regulatory discipline. Refiners use low-metal clays to protect hydrotreating catalysts in renewable diesel, and lubricant blenders demand grades delivering parts-per-billion sulfur removal. Oil-Dri's price adjustment of 5-8% in late 2024 shows the region's ability to pass on cost inflation amid persistent demand. Europe's stringent waste regulation raises compliance costs yet accelerates investment in closed-loop processing. Recycling techniques that recover 35% oil from sepiolite illustrate the region's innovation pace. High-precision German and Swiss cosmetic manufacturers source ultra-pure clays under pharmacopeia specifications, adding premium tonnage.
South America benefits from Brazil's dominance in soybean cultivation, offering synergies between crushing capacity and local clay demand. Middle-East and Africa present emerging potentials, especially where governments push for downstream mineral processing. South Africa's mining contribution of 8.3% GDP and Nigeria's sector modernization foster local beneficiation that can reduce import reliance. These developments diversify the bleaching clay market supply chain and add resilience against regional disruptions.
- 20 Microns Ltd
- American Colloid Company
- Ashapura Group
- Clariant AG
- HRP Industries
- Minerals Technologies Inc.
- Musim Mas Group
- Oil-Dri Corporation of America
- Refoil Earth Pvt Ltd
- Shell plc
- Taiko Clay
- The W Clay Industries Sdn Bhd
- U.S. Silica
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating Consumption of Refined Vegetable Oils
- 4.2.2 Rising Demand from Cosmetics and Personal Care Formulations
- 4.2.3 Growth Of Biodiesel and Renewable Diesel Refining
- 4.2.4 Increasing Need for Ultra-Low-Sulfur Mineral Oils and Lubricants
- 4.2.5 Pharmaceutical-Grade Cannabinoid Oil Purification Adoption
- 4.2.6 Local Beneficiation of Bentonite Deposits In Africa
- 4.3 Market Restraints
- 4.3.1 Strict Environmental Regulations on Mining and Acid Activation Waste
- 4.3.2 Competition from Synthetic Adsorbents (Silica Gels)
- 4.3.3 Volatile Bentonite Prices Due to Supply Concentration
- 4.4 Value Chain Analysis
- 4.5 Porters Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Type
- 5.1.1 Activated Clays
- 5.1.2 Fuller's Earth
- 5.1.3 Activated Bauxite
- 5.2 By Application
- 5.2.1 Mineral Oil and Waxes
- 5.2.2 Industrial Oil
- 5.2.3 Vegetable Oil and Animal Fats
- 5.3 By End-user Industry
- 5.3.1 Food and Beverage Processing
- 5.3.2 Cosmetics and Personal Care
- 5.3.3 Chemicals
- 5.3.4 Other End-user Industries (Energy and Power, etc.)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 Japan
- 5.4.1.3 India
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 NORDIC Countries
- 5.4.3.8 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 20 Microns Ltd
- 6.4.2 American Colloid Company
- 6.4.3 Ashapura Group
- 6.4.4 Clariant AG
- 6.4.5 HRP Industries
- 6.4.6 Minerals Technologies Inc.
- 6.4.7 Musim Mas Group
- 6.4.8 Oil-Dri Corporation of America
- 6.4.9 Refoil Earth Pvt Ltd
- 6.4.10 Shell plc
- 6.4.11 Taiko Clay
- 6.4.12 The W Clay Industries Sdn Bhd
- 6.4.13 U.S. Silica
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

