PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114880

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2114880
Rubber Bonded Abrasive - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
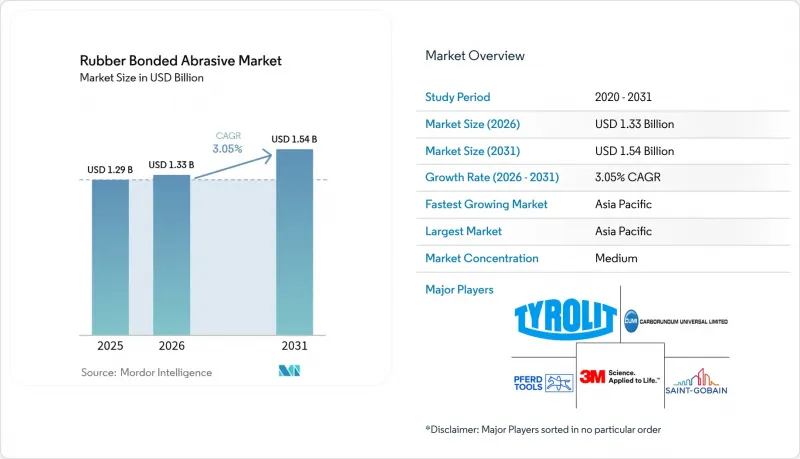
According to Mordor Intelligence, the rubber bonded abrasive market size is expected to grow from USD 1.29 Billion in 2025 to USD 1.33 Billion in 2026 and is forecast to reach USD 1.54 Billion by 2031 at 3.05% CAGR over 2026-2031.
This report is Segmented by Product Type (Wheels, Points and Sticks, and More), Rubber Type (Natural Rubber and More), Application (Gears, Bearings, Turbines, and More), End-User Industry (Industrial Machinery, Automotive, Healthcare, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Rubber Bonded Abrasive Market Trends and Insights
Rising Demand for Metal and Steel Fabrication
Steel capacity additions for infrastructure and shipbuilding amplify the need for compliant grinding tools to prevent thermal distortion. Rubber bonded wheels withstand the high pressures of plate grinding, where vitrified alternatives can fracture. Synthetic-enhanced compounds now extend wheel life, balancing productivity with cost control. Localization of fabrication in North America and Europe opens new demand pockets as buyers seek alternatives to imported grains. Automated grinding lines favor rubber bonded designs because their predictable wear supports longer unattended runs .
Expanding Automotive OEM Production Capacities
Global automakers are enlarging facilities to serve electric vehicle programs that call for precise finishing of powertrain and battery housings. Fine-grit rubber bonded wheels deliver mirror finishes without subsurface damage on steel and aluminum components. Investment announcements in Europe and the United States point to long-term grinding infrastructure upgrades. The segment's tilt toward lightweight materials enhances rubber bonded traction because the same wheel can shift from steel to composites with minor parameter changes.
Environmental Regulations on Rubber and VOC Emissions
Proposed United States Maximum Achievable Control Technology (MACT) standards and tighter European Registration, Evaluation, Authorization and Restriction of Chemicals (REACH) rules are elevating compliance costs for rubber compounders. Manufacturers are reformulating with low-VOC curatives and investing in thermal oxidizers to capture hazardous air pollutants. Small producers may struggle with the capital burden, accelerating consolidation. R&D pipelines now prioritize bio-based alternatives that maintain elasticity while reducing emissions, positioning early adopters for future growth .
Other drivers and restraints analyzed in the detailed report include:
- Process-automation and CNC Integration Boosting Productivity
- Rapid Uptake in 3D-Printed Metal Finishing
- Raw-material Price Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Wheels represented 47.72% of the Rubber Bonded Abrasive market size in 2025, reflecting their indispensability in high-volume heavy-duty grinding. Their broad contact surface supports rapid stock removal on crankshafts and steel plates. Points and sticks, although smaller in volume, are climbing at 3.92% CAGR as electronics and medical plants require pinpoint accuracy for finishing delicate parts. Blocks and segments serve niche applications such as turbine blade root grinding where geometry flexibility is paramount.
CNC adoption is reinforcing demand for shape-stable points that uphold tolerances across extended cycles. Hybrid wheel designs that integrate segment adaptability within a wheel body are emerging, offering shops the productivity of wheels and the finesse of points without tool changeovers.
Complete Report Scope:
- By Product Type
- Wheels
- Points and Sticks
- Blocks and Segments
- Others
- By Rubber Type
- Natural Rubber
- Nitrile (NBR)
- Neoprene
- Other Rubber Types (Silicone, etc.)
- By Application
- Powertrain
- Gears
- Bearings
- Turbines
- Other Applications (Cutting and Forming Tools, etc.)
- By End-user Industry
- Industrial Machinery
- Automotive
- Electrical and Electronics
- Healthcare
- Other End-user Industries (Aerospace, etc.)
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 39.25% of the Global Rubber Bonded Abrasive market share in 2025 and is on course for 4.02% CAGR to 2031. China's vast automotive, electronics, and machinery sectors anchor demand, while national programs encouraging high-quality manufacturing are elevating precision grinding standards. Japan's advanced electronics industry requires high-purity wheels, and South Korea's semiconductor surge is lifting ultra-precision point consumption.
North America is witnessing a rebound as reshoring and defense investments spur the adoption of specialty wheels capable of processing advanced alloys. The United States is particularly active in integrating smart grinding solutions that tie rubber bonded wheel performance data into plant-wide digital twins. Europe shows steady demand but stands out for its leadership in low-VOC formulations to comply with stringent environmental frameworks.
South America and the Middle East and Africa trail in volume yet present upside potential. Brazil's automotive rebuild and Gulf infrastructure megaprojects are spurring procurement of heavy-duty wheels. Technology transfer from global suppliers, coupled with foreign direct investment, is laying the foundation for local finishing capacity, positioning these regions for incremental uptake of rubber bonded products.
- 3M
- ABRASIVOS MANHATTAN S.A.
- Atto Abrasive Ltd.
- Buehler
- Buffalo Abrasives, Inc.
- CUMI.
- KINIK COMPANY
- Klingspor Abrasives, Inc.
- Marrose Abrasives
- Osborn
- Pacer Industries Inc.
- PFERD INC.
- Saint-Gobain
- Schwarzhaupt GmbH & Co. KG
- Tyrolit - Schleifmittelwerke Swarovski AG & Co KG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Metal and Steel Fabrication
- 4.2.2 Expanding Automotive OEM Production Capacities
- 4.2.3 Process-automation and CNC Integration Boosting Productivity
- 4.2.4 Rapid Uptake in 3D-printed Metal Finishing
- 4.2.5 Increase in Electronics and Semiconductors Manufacturing
- 4.3 Market Restraints
- 4.3.1 Environmental Regulations on Rubber and VOC Emissions
- 4.3.2 Raw-material Price Volatility
- 4.3.3 Shift Toward Super-abrasives in Precision Grinding
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitute Products
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Wheels
- 5.1.2 Points and Sticks
- 5.1.3 Blocks and Segments
- 5.1.4 Others
- 5.2 By Rubber Type
- 5.2.1 Natural Rubber
- 5.2.2 Nitrile (NBR)
- 5.2.3 Neoprene
- 5.2.4 Other Rubber Types (Silicone, etc.)
- 5.3 By Application
- 5.3.1 Powertrain
- 5.3.2 Gears
- 5.3.3 Bearings
- 5.3.4 Turbines
- 5.3.5 Other Applications (Cutting and Forming Tools, etc.)
- 5.4 By End-user Industry
- 5.4.1 Industrial Machinery
- 5.4.2 Automotive
- 5.4.3 Electrical and Electronics
- 5.4.4 Healthcare
- 5.4.5 Other End-user Industries (Aerospace, etc.)
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 Japan
- 5.5.1.3 India
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN Countries
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 NORDIC Countries
- 5.5.3.8 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 3M
- 6.4.2 ABRASIVOS MANHATTAN S.A.
- 6.4.3 Atto Abrasive Ltd.
- 6.4.4 Buehler
- 6.4.5 Buffalo Abrasives, Inc.
- 6.4.6 CUMI.
- 6.4.7 KINIK COMPANY
- 6.4.8 Klingspor Abrasives, Inc.
- 6.4.9 Marrose Abrasives
- 6.4.10 Osborn
- 6.4.11 Pacer Industries Inc.
- 6.4.12 PFERD INC.
- 6.4.13 Saint-Gobain
- 6.4.14 Schwarzhaupt GmbH & Co. KG
- 6.4.15 Tyrolit - Schleifmittelwerke Swarovski AG & Co KG
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
- 7.2 Biodegradable and Recyclable Rubber Materials

