PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115000

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115000
Poly Aluminum Chloride - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the poly aluminum chloride market size was valued at USD 2.05 billion in 2025 and estimated to grow from USD 2.14 billion in 2026 to reach USD 2.62 billion by 2031, at a CAGR of 4.20% during the forecast period (2026-2031).
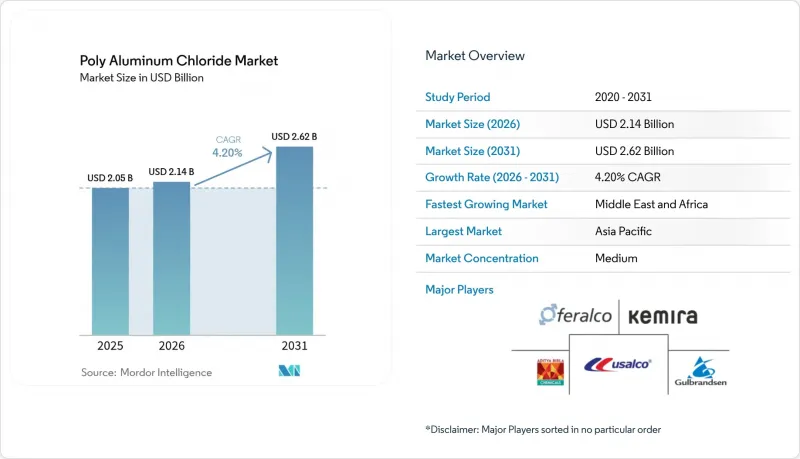
This report is Segmented by Form (Liquid, Powder, and Granular), Basicity Level (Low, Medium, and High), End-User Industry (Water Treatment, Paper Industry, Cosmetics and Personal Care, Oil and Gas, and Other End-User Industries), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Poly Aluminum Chloride Market Trends and Insights
Tightening Discharge Norms Drive Advanced Coagulation Adoption
Environmental agencies in the European Union, the United States, and advanced Asia-Pacific economies have introduced sharper chemical oxygen demand and total suspended solids thresholds that compel operators to adopt higher-performance coagulants. The forthcoming revision of the EU Urban Wastewater Treatment Directive in late 2025 formalizes enhanced nutrient removal targets, reinforcing preference for PAC, whose broader pH window and lower sludge generation reduce downstream handling costs. Industrial segments such as textiles and food processing now favor pre-polymerized aluminum chemistry that meets multiple discharge parameters concurrently, emphasizing PAC's versatility. The combined regulatory momentum adds roughly EUR 40 million in annual chemical demand across EMEA treatment plants, underpinning steady procurement contracts despite commodity-price volatility.
APAC Desalination Expansion Fuels Coagulant Demand
Asia-Pacific governments continue to approve large-scale desalination and municipal reuse projects to counter water scarcity, positioning the region as the largest demand hub for PAC. China's industrial water-reuse mandates, India's Smart Cities initiative, and Southeast Asian infrastructure programs rely on high-basicity PAC for stable floc formation in saline feedwater. Mega-projects such as Malaysia's RAPID complex and Indonesia's new industrial corridors incorporate water-treatment trains that specify PAC at the pretreatment stage, ensuring compliance with feedwater quality requirements for downstream membranes. Suppliers respond by expanding regional manufacturing footprints to safeguard supply continuity and mitigate shipping costs.
Raw-Material Price Volatility Pressures Margins
Alumina spot prices in China climbed 35% year-to-date during 2024 as Guinea export disruptions hit global bauxite supply, creating the steepest cost spike since 2012. Hydrochloric acid values experienced parallel volatility tied to refinery operating rates, forcing PAC producers to renegotiate quarterly contracts. Large integrated suppliers partially absorb the impact through hedging strategies, but smaller regional firms without captive alumina supply face squeezed margins and may accelerate consolidation. Customers with long-term framework agreements gain price stability, yet competitive tenders increasingly incorporate cost-pass-through clauses to reflect raw-material dynamics.
Other drivers and restraints analyzed in the detailed report include:
- Cost Optimization Drives PAC Adoption Over Conventional Coagulants
- High-Basicity Formulations Enable Microplastics Removal
- Aluminum Residual Limits Challenge Product Positioning
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
because large municipal plants value turnkey bulk-delivery infrastructure that minimizes on-site handling. The segment's entrenched position stems from decades-old procurement frameworks, proximity to producers, and immediate solubility that avoids sediment risks inside storage tanks. Even as feedstock prices fluctuate, utilities locked into long-term supply agreements maintain consistent order volumes, which stabilizes plant utilization rates for liquid lines.
Powder grades, however, are forecast to expand at a 4.52% CAGR through 2031 as transportation costs rise and exporters seek higher value density per container. Recent advances in spray-drying and anti-caking additives lengthen shelf life and strengthen moisture resistance, allowing powder to move deeper into land-locked markets without quality loss. Small community plants and industrial users with limited storage increasingly prefer concentrated powder that reconstitutes on demand, especially where road infrastructure restricts tanker access. As a result, global producers invest in modular powder plants that can be co-located with alumina sources to decouple production from end-market geography.
Complete Report Scope:
- By Form
- Liquid
- Powder
- Granular
- By Basicity Level
- Low (less than 40% basicity)
- Medium (40-60%)
- High (more than 60%)
- By End-user Industry
- Water Treatment
- Paper Industry
- Cosmetics and Personal Care
- Oil and Gas
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- Turkey
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held a dominant 49.10% share of the poly aluminum chloride market in 2025 on the back of unparalleled water-infrastructure investment, rapid urbanization, and a dense industrial base across China, India, and Southeast Asia. China alone accounts for over 40% of global consumption, underpinned by extensive municipal expansion and its position as the leading PAC exporter.
Middle East and Africa is forecast to record the highest regional CAGR at 4.38% through 2031 as desalination continues to pivot from thermal to membrane-based technologies that require precise coagulation pretreatment. Gulf Cooperation Council states invest in smart-city projects such as Saudi Arabia's NEOM, each embedding large treatment plants that prefer high-basicity PAC for saline feedwater. Sub-Saharan African countries, meanwhile, channel World Bank financing into municipal projects where PAC's broad pH window shields operators from variable raw-water chemistry, even as supply chains rely on imported product.
North America and Europe see modest but resilient growth driven by infrastructure rehabilitation and regulatory tightening. United States utilities facing aging pipe networks integrate PAC dosing optimization with digital sensors to meet revised Lead and Copper Rule guidelines, while European operators align with the updated Urban Wastewater Treatment Directive's nutrient-removal stipulations. Although total volume expansion lags emerging regions, these mature markets prize premium, low-residual grades with full traceability and lifecycle documentation, sustaining healthy margins for suppliers with robust quality systems.
- Aditya Birla Chemicals (India) Limited
- Airedale Chemical
- Central Glass Co. Ltd.
- Feralco AB
- GEO Specialty Chemicals Inc.
- Gujarat Alkalies and Chemicals Limited (GACL)
- Gulbrandsen
- HOLLAND COMPANY
- IXOM
- Kemira
- Liyuan
- Pacific Chemicals Co.
- Shandong Tenor Water Treatment Technology Co., Ltd.
- Summit Chemical Specialty Products LLC
- Synergy Multichem Pvt. Ltd
- TAKI CHEMICAL CO., LTD.
- USALCO LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Tightening discharge norms for COD/TSS in municipal and industrial effluents
- 4.2.2 Rapid capacity additions in APAC desalination and municipal reuse plants
- 4.2.3 Cost advantage versus alum and ferric salts at equivalent turbidity removal
- 4.2.4 High-basicity PAC grades proving superior for micro-plastics capture
- 4.2.5 On-site PAC electro-synthesis systems cutting bulk-haul logistics emissions
- 4.3 Market Restraints
- 4.3.1 Volatile alumina and hydrochloric acid feed-stock prices
- 4.3.2 Regulatory scrutiny on residual Al in drinking water (<0.05 mg/L future limits)
- 4.3.3 Uptake of low-chemical membrane and electro-coag technologies in OECD plants
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Form
- 5.1.1 Liquid
- 5.1.2 Powder
- 5.1.3 Granular
- 5.2 By Basicity Level
- 5.2.1 Low (less than 40% basicity)
- 5.2.2 Medium (40-60%)
- 5.2.3 High (more than 60%)
- 5.3 By End-user Industry
- 5.3.1 Water Treatment
- 5.3.2 Paper Industry
- 5.3.3 Cosmetics and Personal Care
- 5.3.4 Oil and Gas
- 5.3.5 Other End-user Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Spain
- 5.4.3.5 Italy
- 5.4.3.6 Russia
- 5.4.3.7 NORDIC Countries
- 5.4.3.8 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 Turkey
- 5.4.5.3 South Africa
- 5.4.5.4 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Aditya Birla Chemicals (India) Limited
- 6.4.2 Airedale Chemical
- 6.4.3 Central Glass Co. Ltd.
- 6.4.4 Feralco AB
- 6.4.5 GEO Specialty Chemicals Inc.
- 6.4.6 Gujarat Alkalies and Chemicals Limited (GACL)
- 6.4.7 Gulbrandsen
- 6.4.8 HOLLAND COMPANY
- 6.4.9 IXOM
- 6.4.10 Kemira
- 6.4.11 Liyuan
- 6.4.12 Pacific Chemicals Co.
- 6.4.13 Shandong Tenor Water Treatment Technology Co., Ltd.
- 6.4.14 Summit Chemical Specialty Products LLC
- 6.4.15 Synergy Multichem Pvt. Ltd
- 6.4.16 TAKI CHEMICAL CO., LTD.
- 6.4.17 USALCO LLC
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

